
OMRON (TSE:6645) Could Be 35% Above Fair Value Following Its OnLogic Deal
OMRON (TSE:6645) just agreed to buy US industrial PC maker OnLogic for $675 million in cash, a move that pushes the Japanese automation specialist deeper into industrial edge computing and physical AI.
The acquisition headlines arrive after a sharp pullback, with OMRON’s share price falling 7.57% over the last trading day and 6.59% over the past week. However, the 90-day share price return of 11.53% and year-to-date gain of 48.17% point to stronger underlying momentum than the 5-year total shareholder return, which is down 38.59%.
See how OMRON’s move into industrial edge computing compares with other robotics and automation plays by checking the hand picked 90 robotics and automation stocks in this space.
OMRON now trades with fresh deal risk, a strong year to date run, and a big push into edge computing all colliding. Does that mix still leave enough upside potential to compensate for the new uncertainties?
Preferred P/E of 29x: Is it justified?
Valuation on OMRON now hinges on a P/E of 29x, which sits well above the wider JP Electronic industry but still below closer peers in its own group.
P/E compares the current share price to earnings per share and is often used for established manufacturers with consistent profit streams. For an automation and industrial technology player like OMRON, that ratio effectively reflects what investors are willing to pay today for each unit of current earnings.
The stock trades on 29x earnings, while the estimated fair P/E from the SWS model sits at 22.1x. This points to a rich tag compared with where the multiple could ultimately drift. Against that, similar companies in OMRON’s peer set trade on an average P/E of 44.7x, which means the market is assigning the group a much higher earnings premium than this stock currently enjoys.
The broader JP Electronic industry runs on a P/E of 17.1x, so OMRON’s 29x level looks materially more expensive than the sector backdrop, even if it appears relatively cheaper beside its closest competitors.
Explore the SWS fair ratio for OMRON.
Result: Price-to-Earnings of 29x (OVERVALUED)
Still, OMRON carries clear risk that the integration of OnLogic drags on earnings, while a 29x P/E leaves little room for disappointment if growth cools.
Find out about the key risks to this OMRON narrative.
Another view on OMRON’s value
The SWS DCF model paints a different picture from the 29x P/E debate. On that cash flow view, OMRON at ¥6,406 is above an estimated future cash flow value of ¥4,161.88, which points to an overvalued signal rather than a bargain. How should an investor weigh that against the peer discount story?
Look into how the SWS DCF model arrives at its fair value.
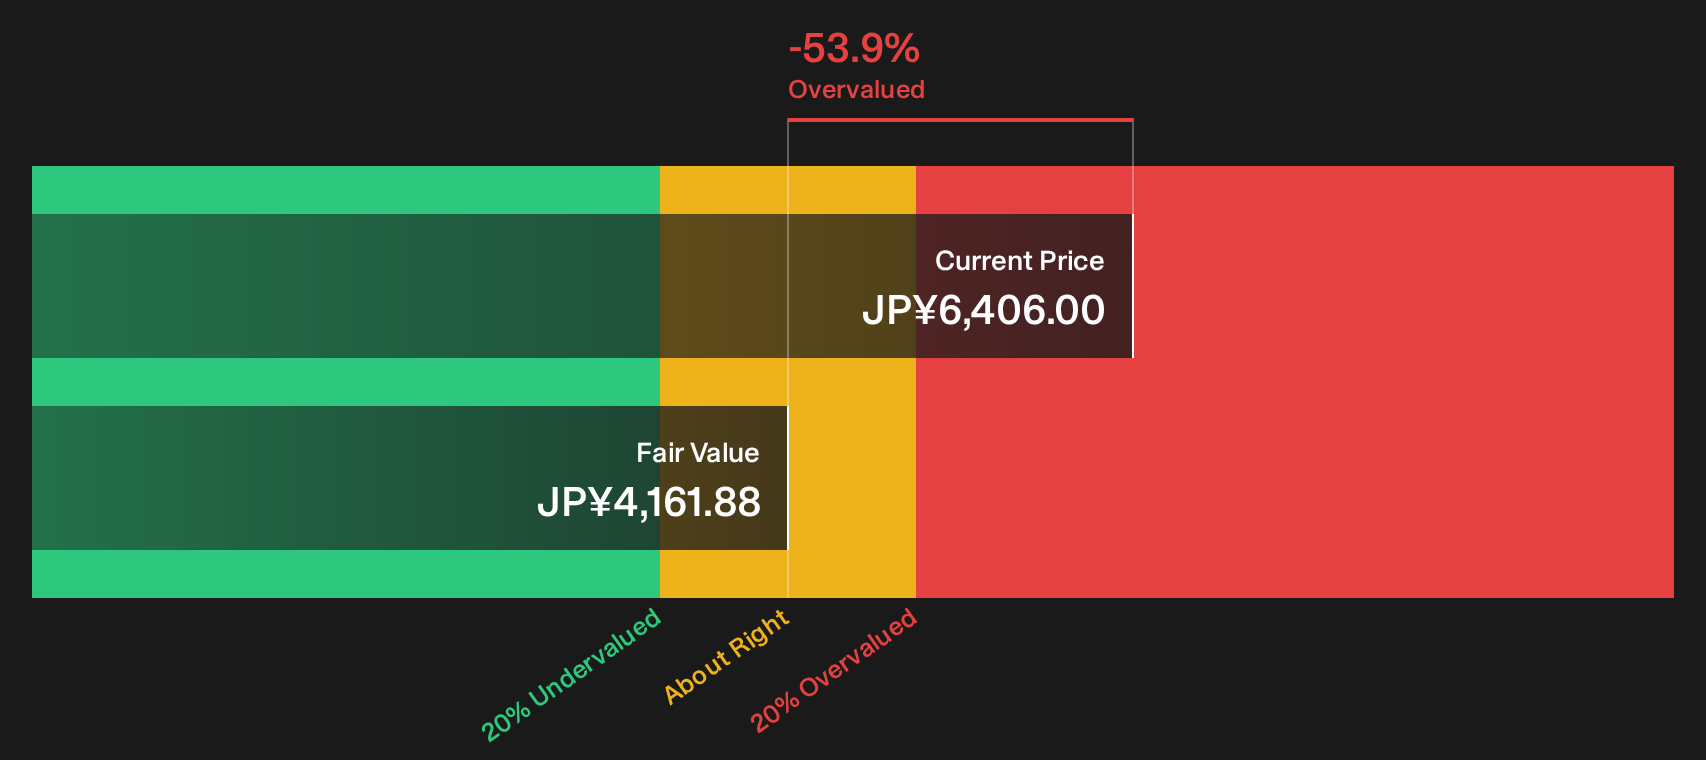
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out OMRON for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around OMRON is mixed after the OnLogic deal, so timing matters when you weigh fresh risks against long term potential. Act quickly, review both the downside flags and upside drivers, and ground your own view in the full picture by checking the 2 key rewards and 1 important warning sign.
Looking for more OMRON sized ideas?
If OMRON is on your radar, do not stop here. Broaden your watchlist now with other opportunities filtered by quality, value, and resilience.
- Target potential bargains that combine quality fundamentals with appealing valuations by reviewing the 15 high quality undervalued stocks.
- Lock in income focused opportunities by scanning the 29 dividend fortresses.
- Prioritise resilience and capital protection by working through the 23 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com