
Caught Out By Cogent Communications' 83% Fall? What Bears Saw
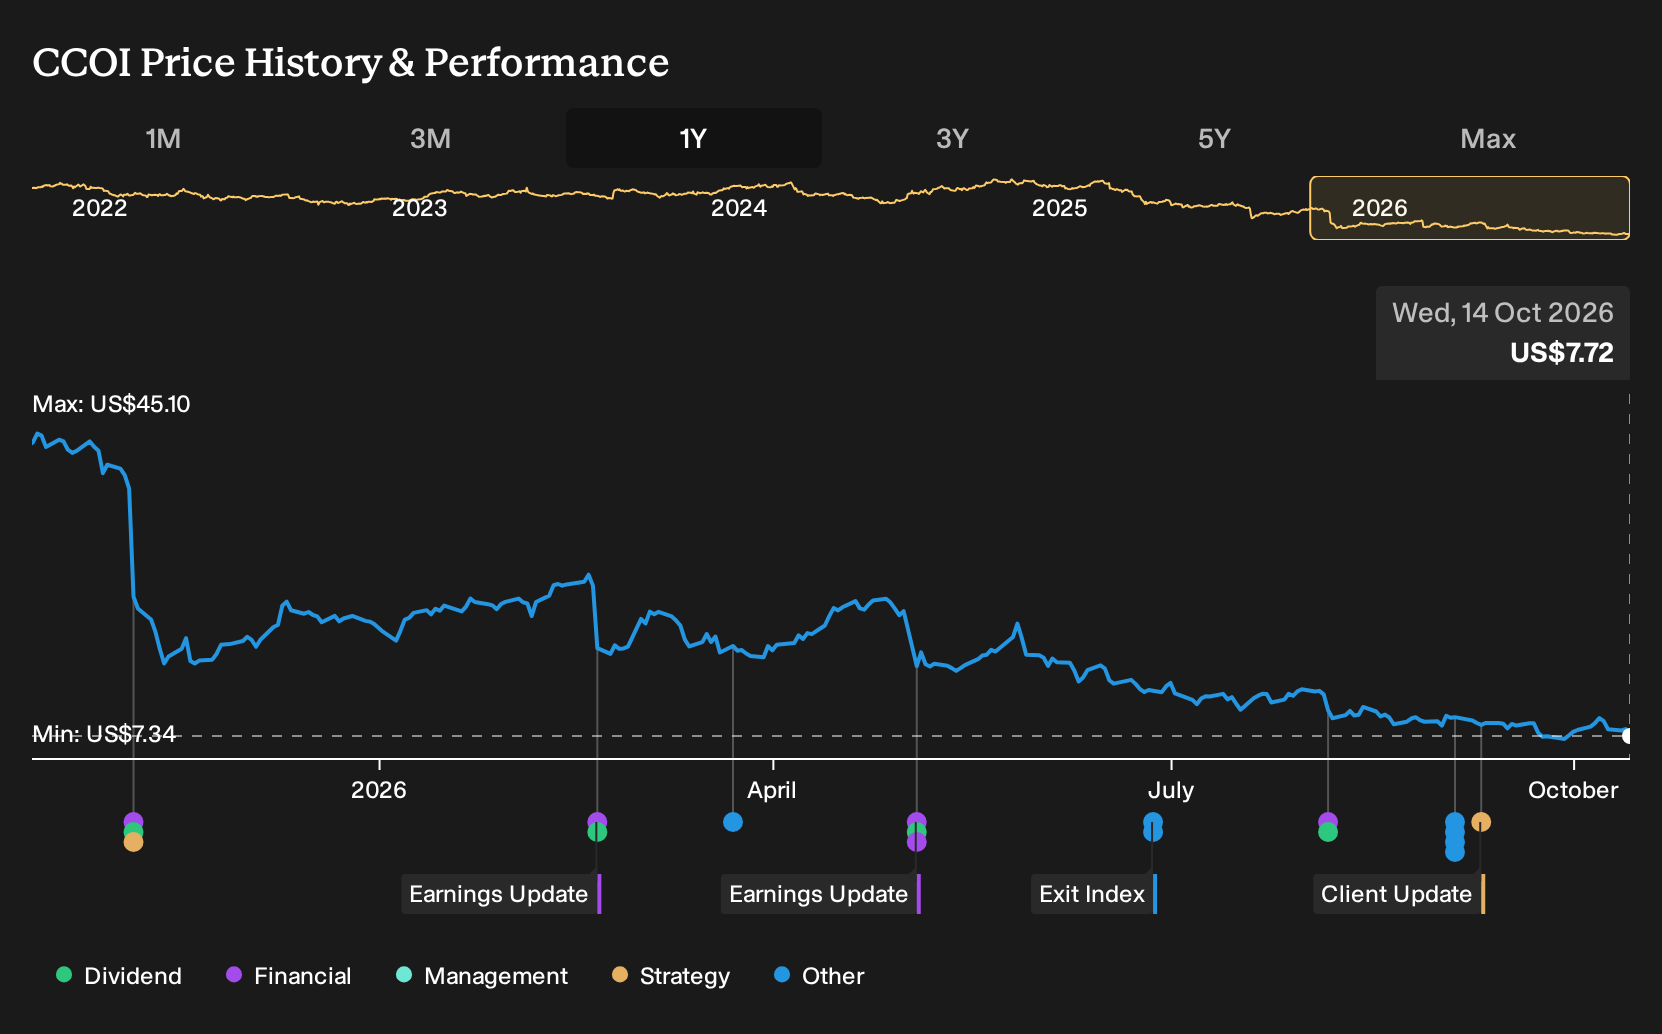
If you backed Cogent Communications for its growing wavelength pipeline and on-net focus, the payoff has been harsh. Investors who held Cogent Communications over the past year are down 82.8%, including dividends. Earnings calls flagged a shift toward higher-margin services, and analysts had detailed revenue and profit margin assumptions for 2028. If you had bought on those expectations in October 2025, which of those specific growth and margin assumptions now looks most exposed?
Cogent Communications has already moved. Pinpoint other ways to investigate the theme among 92 AI infrastructure stocks.
The Argument Investors Faced On Cogent Communications
The shares cost US$44.01 at the start of the period, and investors in Cogent Communications were weighing two very different stories about what that price implied.
The optimistic camp anchored on a Fair Value of US$47.73, a notional target price tied to assumptions such as 10.4% annual revenue growth and profit margins rising toward 12.8% by 2028, as high-capacity data traffic and wavelength demand fed into a richer on-net mix.
The cautious view pointed to a Fair Value of US$41.25, again a modelled outcome, and focused on falling bandwidth prices, reliance on T Mobile transition payments, and execution risk around selling noncore data center assets as key threats to Cogent Communications.
What The Results Changed For Cogent Communications
Cogent Communications reported Q2 2026 revenue of US$216.7m compared with US$226.2m a year earlier, which challenged the optimistic 10.4% annual growth story. At the same time, net income moved from a loss of US$57.8m to a profit of US$66.6m and net margin shifted from a 25.6% loss to a 30.8% profit, so the evidence cut both ways.
The key assumption was not just faster growth but profitable growth. When you see a pitch built on margin expansion, keep tracking net margin and absolute earnings against the original forecast, not just the revenue line.
What Cogent Communications' New Price Is Really Asking You To Believe
Cogent Communications now trades at US$7.72, after the shares fell 82.8% over the past year. The selected Narrative sees Fair Value above that quote, based on the idea that refinancing, asset sales and mix shift can matter more than recent revenue pressure.
The core bet is that Cogent Communications turns the Sprint wireline footprint into a larger, higher margin on-net and wavelength business while managing the 2027 refinancing without eroding economics too far.
"The main thing that has to go right is that Cogent Communications Holdings converts the Sprint network and asset base into a higher mix of on-net and wavelength revenue, while using data center and note monetisations to reduce leverage before the 2027 maturity. The current numbers on revenue mix, EBITDA margin expansion and deleveraging progress imply a share price that does not fully reflect the potential benefits from a structurally larger AI-driven bandwidth market and further monetisation of legacy Sprint assets."
One Narrative disagrees with today's price. → See where this Narrative says Cogent Communications should trade
Looking One Step Beyond Cogent
Cogent Communications depends on bandwidth hungry customers who rarely scale back usage. You are effectively assuming that connectivity demand continues to stretch higher over time.
That same appetite for capacity appears elsewhere in the sector. Another operator leans on broadband, mobile networks and enterprise links to keep service revenue resilient.
Its task is not just adding connections. It bundles wireless access, fiber broadband and business connectivity into stickier, higher value relationships.
Enterprise buyers want private networks, secure connections and links ready for intensive computing. If those needs keep deepening, this parallel connectivity play could matter more than headline mobile plans suggest.
That argument has a Narrative and a number behind it. → See the company one Narrative values 16% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com