
Did Soft Q2 Results Just Shift Cooper Companies' (COO) Investment Narrative?
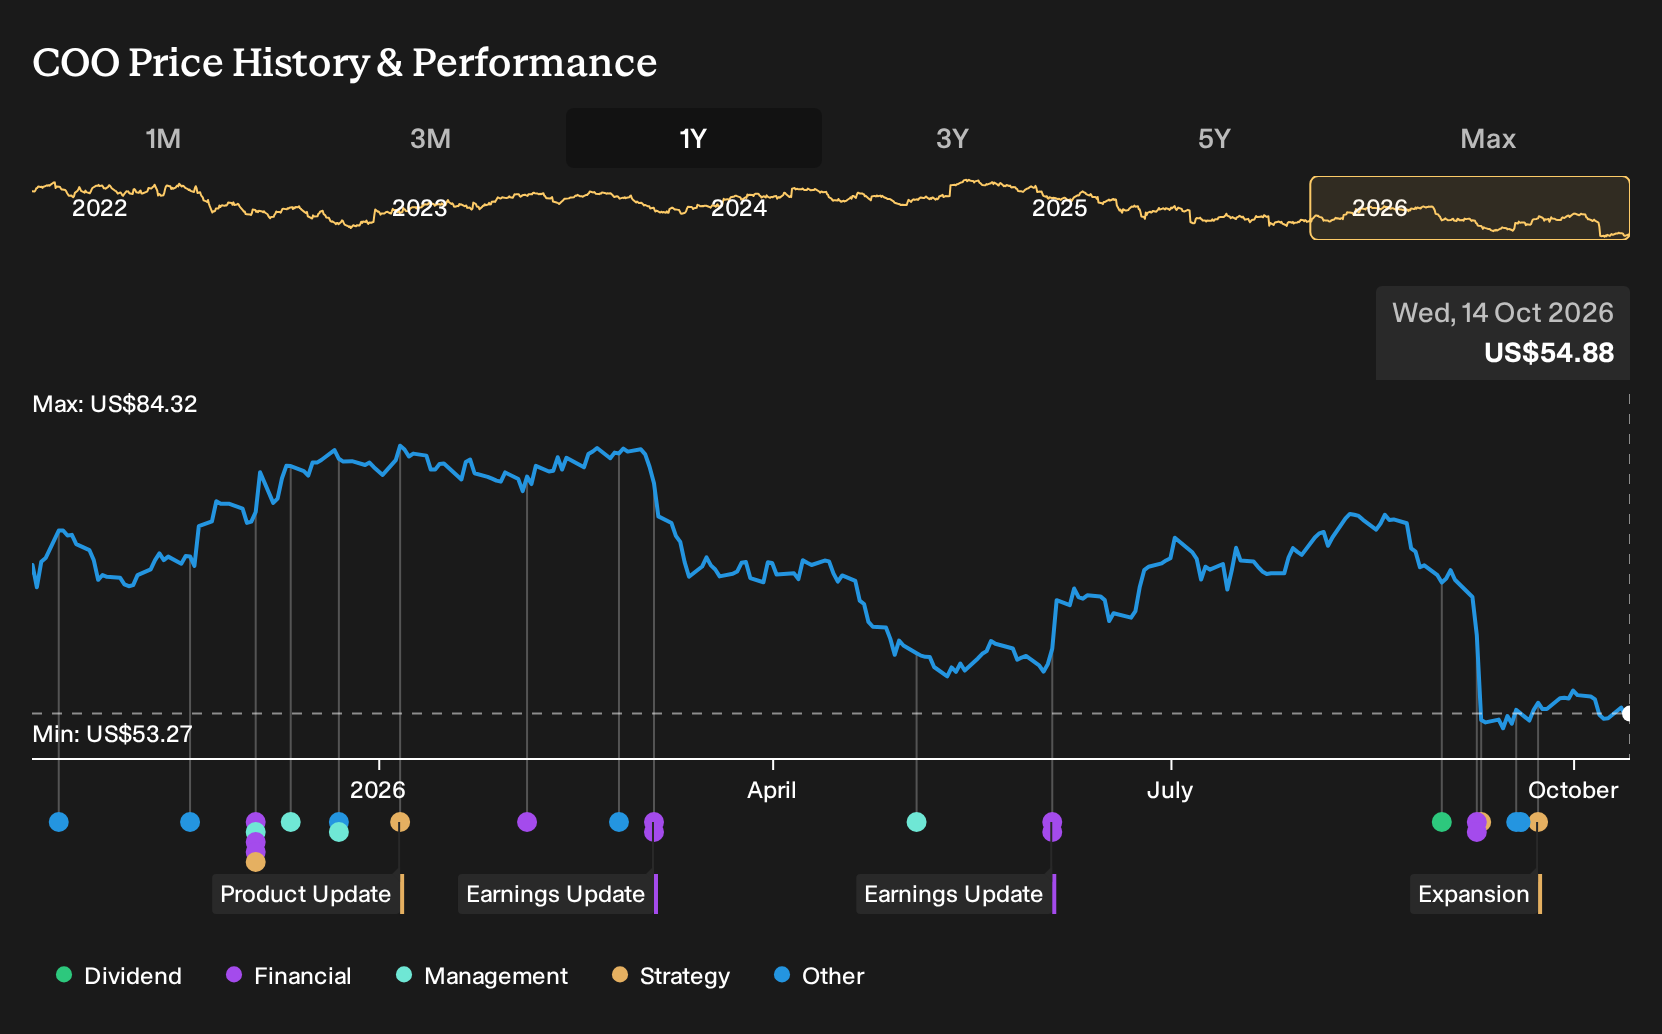
- Cooper Companies recently reported a softer Q2, with revenue coming in 2.9% below analyst expectations and full year EPS guidance revised to a more cautious level, as reduced U.S. channel inventory at CooperVision weighed on results.
- The business is now emphasizing profitable growth, cash generation, and shareholder value after a strategic review. At the same time, a securities law firm investigation into alleged misleading disclosures adds legal overhang and raises questions about how clearly prior challenges were communicated to investors.
- We will look at how Cooper Companies' weaker Q2 and softer EPS guidance reshape the existing investment narrative around premium lenses.
Stress test your thesis on Cooper Companies against other high quality ophthalmic and healthcare stocks by screening for list of solid balance sheet and fundamentals (25 results) before the next earnings season reshapes expectations.
Cooper Companies Investment Narrative Recap
To stay invested in Cooper Companies, you need to believe the shift toward premium daily silicone hydrogel lenses and myopia management can keep reshaping the product mix, while CooperSurgical fertility and women’s health add a second leg of growth. The weaker Q2 and softer EPS guidance mainly affect how quickly that mix upgrade shows up in reported numbers.
The key near term catalyst is execution at CooperVision as U.S. channel inventory normalizes and premium franchises like MyDay and MiSight work to offset legacy hydrogel rationalization. The biggest risk right now is that weaker reported growth and lower guidance point to a more persistent drag, particularly if Asia Pacific softness and CooperSurgical legal issues continue.
The Rosen Law Firm investigation into alleged misleading business information adds a separate layer of risk on top of the operating story. It follows a sharp share price decline after weak guidance and the decision not to sell CooperSurgical, which already increased scrutiny on how Cooper Companies presents its outlook and portfolio choices.
For you as an investor, this legal overhang matters because it could absorb management attention and, depending on outcomes, lead to additional cash costs. It sits alongside existing litigation and regulatory issues at CooperSurgical and may influence how quickly Cooper Companies can fully refocus on premium lens execution, fertility growth, and capital returns as the primary catalysts.
Cooper Companies' narrative projects US$4.9b revenue and US$779.8 million earnings by 2029. This assumes 4.8% yearly revenue growth and an earnings increase of about US$209.5 million from US$570.3 million today.
Uncover why Cooper Companies' fair value indicates a 21% potential upside to its current price before that discount narrows.
Exploring Other Perspectives
For Cooper Companies, the alternate narrative focuses on weaker operating leverage as the key risk. The most cautious analysts were only penciling in roughly US$4.7b of revenue and about US$705.4 million of earnings by 2029 before this Q2 update. That is a far more restrained path than consensus. It shows how far opinions can spread, so treat this softer quarter as a prompt to compare several viewpoints rather than anchor on a single story.
Explore 5 other Cooper Companies fair value estimates, including one that suggests as much as 21% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Cooper Companies research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Cooper Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cooper Companies' overall financial health at a glance.
Looking for more Cooper Companies style ideas?
Once you have refreshed your view on Cooper Companies, it can help to cross check your thinking against a broader watchlist so you are not relying on a single stock to carry your thesis.
- If capital preservation is high on your list, start with a 32 resilient stocks with low risk scores that keeps the focus on resilient balance sheets and steadier business profiles.
- If you want quality at a discount, scan a 32 high quality undervalued stocks that filters for strong fundamentals trading at what may be appealing prices.
- If you are hunting for companies the market may not be paying close attention to yet, sort through a 20 high quality undiscovered gems that highlight strong underlying metrics before they are widely talked about.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com