
Undiscovered Gems In Asia To Watch This October 2026
As global markets navigate a landscape marked by volatility in energy prices and geopolitical tensions, the Asian market remains a focal point for investors seeking opportunities beyond the conventional. With small-cap stocks often overlooked amid broader market movements, identifying promising companies in this sector requires an understanding of their potential to adapt and thrive under current economic conditions.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Apex Mining | 22.02% | 24.39% | 37.14% | ★★★★★★ |
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Goodbaby International Holdings | 6.30% | -1.33% | 24.07% | ★★★★★★ |
| Eurocharm Holdings | 2.66% | 3.48% | 7.39% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Here we highlight a subset of our preferred stocks from the screener.
Wuhan Hvsen BiotechnologyLtd (SZSE:300871)
Simply Wall St Value Rating: ★★★★★☆
Overview: Wuhan Hvsen Biotechnology Co., Ltd. engages in the research, development, and manufacture of macrolides APIs and preparations both in China and internationally, with a market cap of CN¥3.94 billion.
Operations: The company's primary revenue stream is from its pharmaceuticals segment, generating CN¥1.72 billion. The financial performance highlights a focus on this core area without diversifying into unrelated segments.
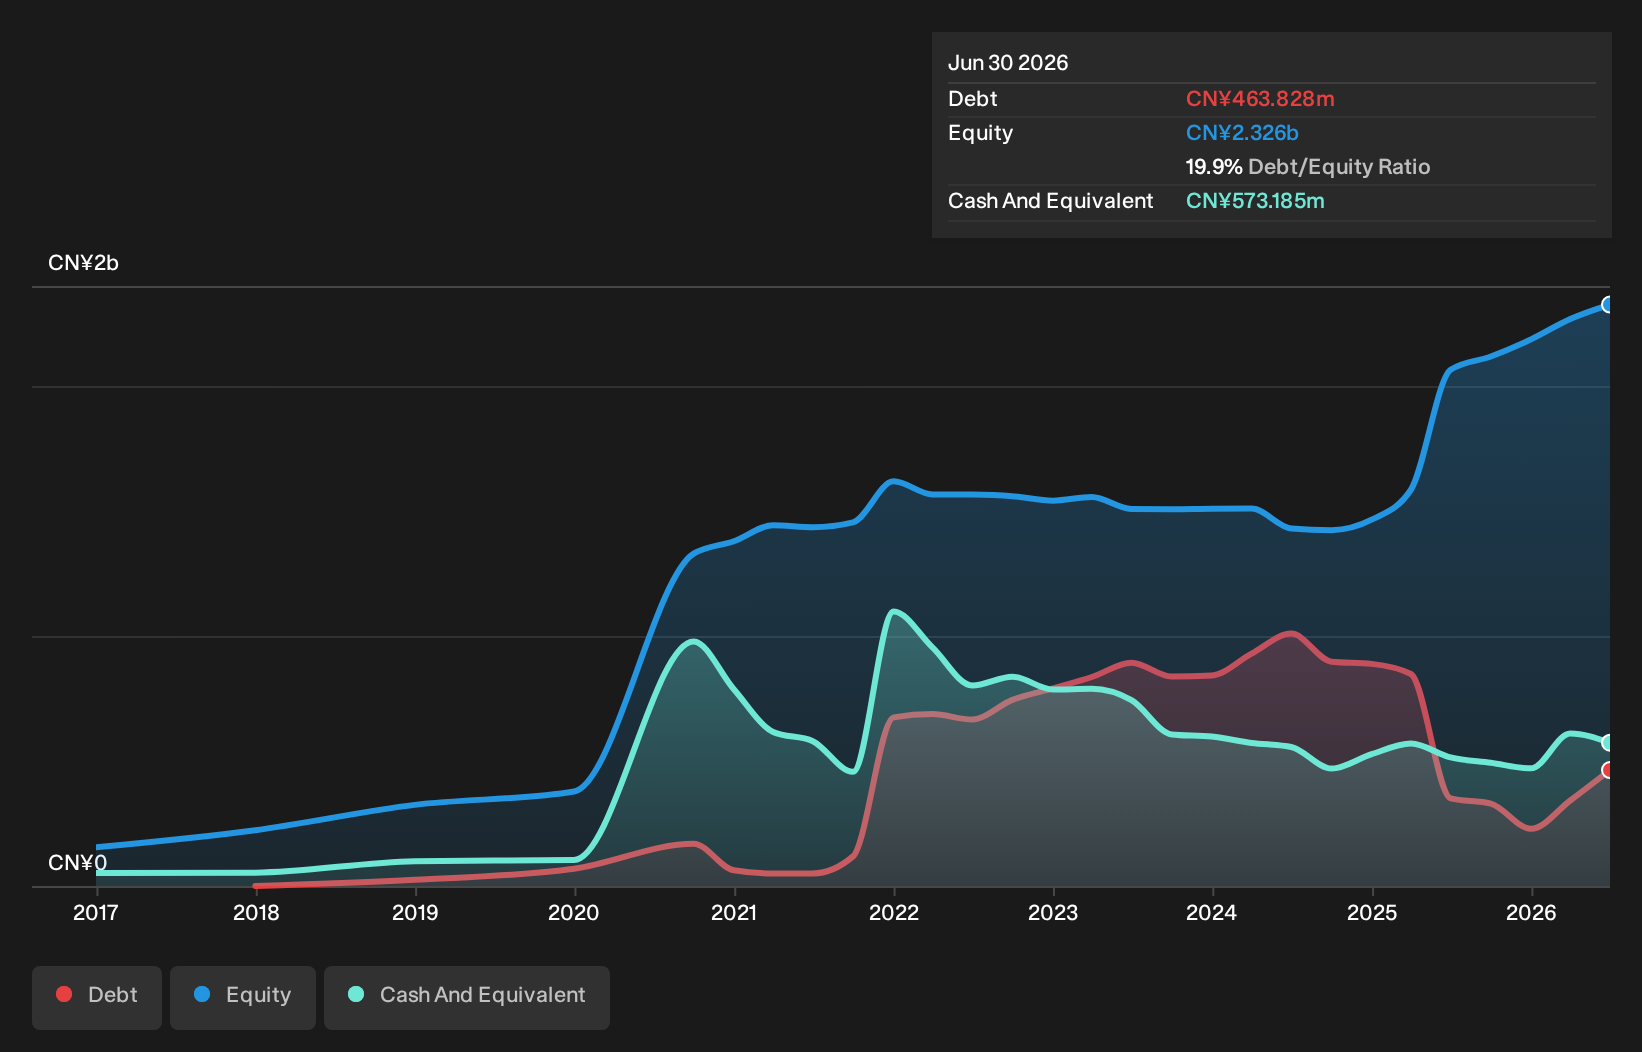
Wuhan Hvsen Biotechnology, a small player in the biotech sector, has shown impressive financial performance recently. Earnings surged by 129.5% over the past year, significantly outpacing the broader pharmaceuticals industry. The company reported a net income of CN¥205.76 million for the first half of 2026, compared to CN¥117.18 million last year, alongside revenue growth to CN¥864.93 million from CN¥822.2 million previously. Despite a debt-to-equity ratio increase from 3.5% to 19.9% over five years, it holds more cash than total debt and trades at an attractive value relative to peers and industry standards.
- Dive into the specifics of Wuhan Hvsen BiotechnologyLtd here with our thorough health report.
Learn about Wuhan Hvsen BiotechnologyLtd's historical performance.
JirFine Intelligent Equipment (SZSE:301603)
Simply Wall St Value Rating: ★★★★★★
Overview: JirFine Intelligent Equipment Co., Ltd. specializes in the research, development, production, and sale of CNC machine tools both domestically and internationally, with a market capitalization of CN¥12.84 billion.
Operations: JirFine generates revenue primarily from the sale of CNC machine tools. The company experiences fluctuations in its net profit margin, which is a key indicator of its profitability.
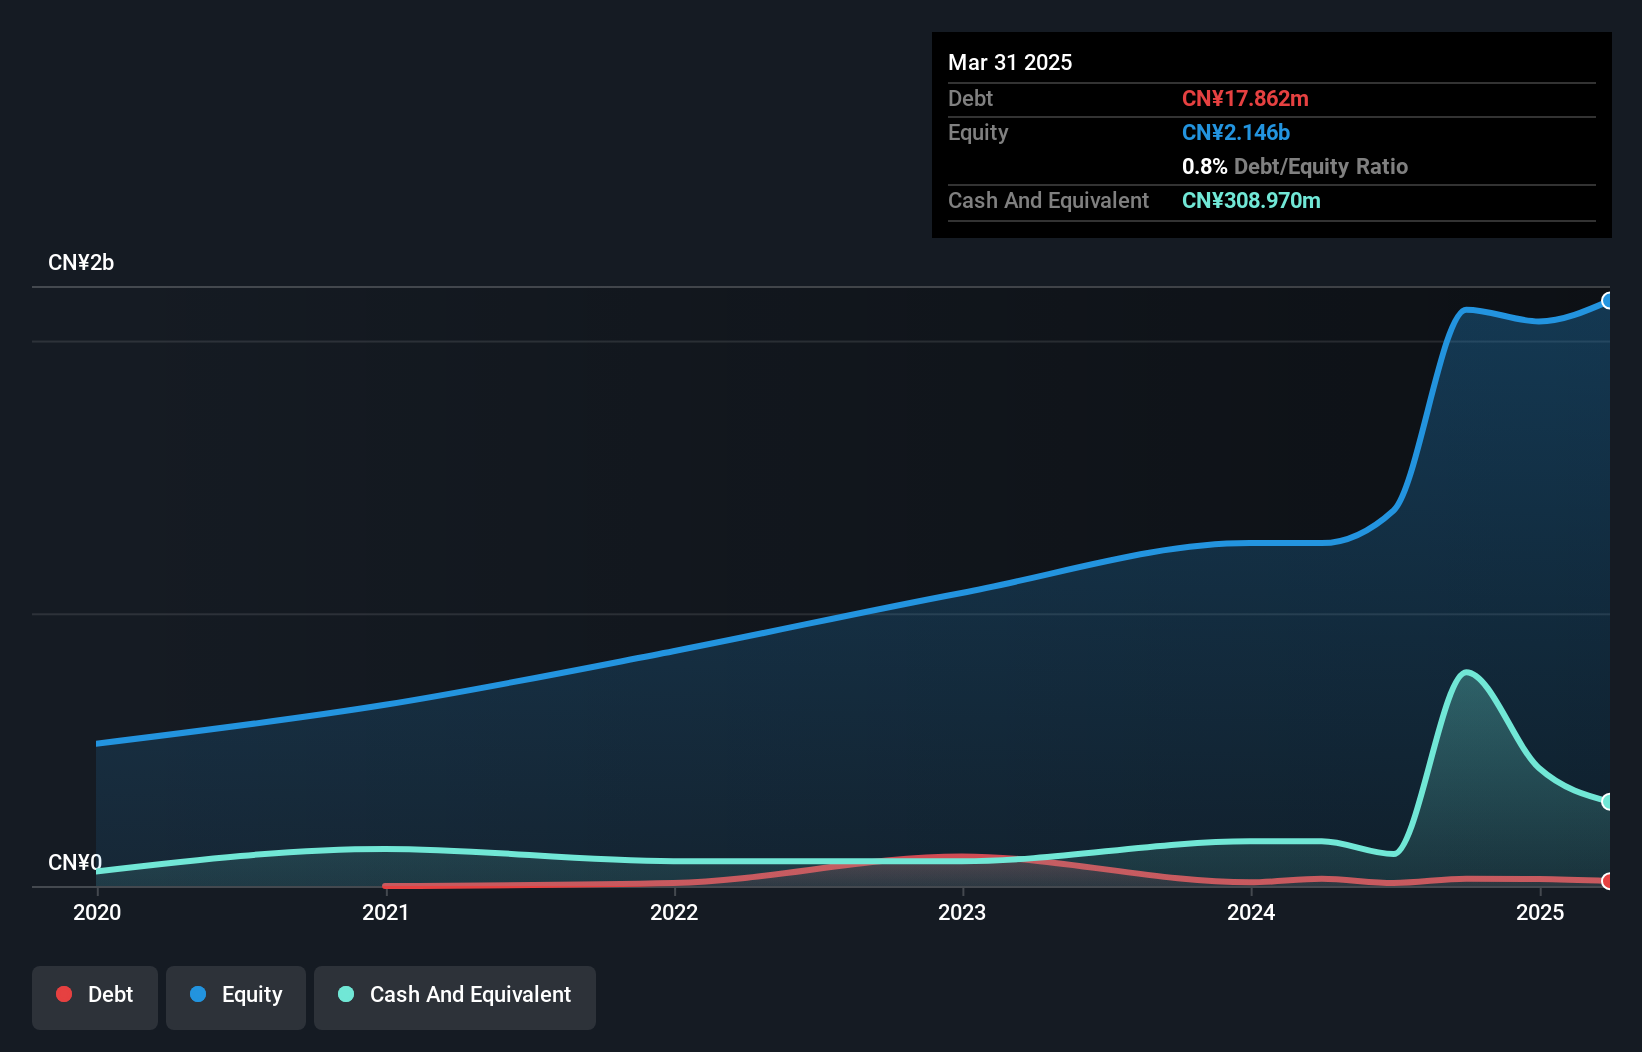
JirFine Intelligent Equipment, a nimble player in the machinery sector, has seen its earnings surge by 65% over the past year, outpacing industry growth of 0.7%. The company's debt to equity ratio impressively decreased from 2% to 0.8% over five years, reflecting prudent financial management. Recently reported half-year sales climbed to CNY 1.64 billion from CNY 1.10 billion last year, with net income rising to CNY 273 million from CNY 179 million. Despite volatile share prices recently, JirFine's earnings are expected to grow at an annual rate of about 37%, suggesting robust future potential amidst current market dynamics.
gremsInc (TSE:3150)
Simply Wall St Value Rating: ★★★★★★
Overview: grems,Inc., with a market cap of ¥55.41 billion, operates in Japan's energy sector focusing on providing energy solutions and retailing electricity.
Operations: The company's revenue streams are derived from its Energy Solutions Business, contributing ¥14.34 billion, and its Retail Electricity Business, generating ¥20.16 billion.
GremsInc, a nimble player in the commercial services sector, has shown promising financial health. Its debt-to-equity ratio has impressively decreased from 30.5% to 17.1% over five years, reflecting prudent financial management. The company trades at a notable discount of 51.4% below its estimated fair value, suggesting potential upside for investors seeking value opportunities. With earnings growing at an annual rate of 25.4%, GremsInc showcases robust performance but slightly lags behind industry growth rates in the past year (9.1% vs 9.9%). Additionally, it maintains high-quality earnings and remains free cash flow positive, indicating solid operational efficiency.
- Click to explore a detailed breakdown of our findings in gremsInc's health report.
Evaluate gremsInc's historical performance by accessing our past performance report.

Summing It All Up
- Take a closer look at our Asian Undiscovered Gems With Strong Fundamentals list of 116 companies by clicking here.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Unlock the power of informed investing with Simply Wall St, your free guide to navigating stock markets worldwide.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com