
Google Gemini Integration Could Be A Game Changer For Xero (ASX:XRO)
- Xero announced a new connected app for Google Gemini, allowing small businesses and advisors to pull live Xero financial data into Gemini chats to view reports, manage receivables and payables, and organize key business information without leaving the conversational interface.
- The integration is powered by Xero’s agentic platform, JAX. It keeps real-time data synchronized while Gemini generates interactive visual reports and supports emerging workflow automation across tools like Gmail.
- We will now look at how Xero’s investment narrative could be affected by embedding real-time financial workflows directly inside Google Gemini.
Scan how Xero’s Gemini tie-up fits into a wider shift toward AI-enabled workflows by reviewing our hand-picked 39 profitable AI stocks that aren't just burning cash.
Xero Investment Narrative Recap
To own Xero, you need to believe its cloud tools can keep pulling in more small businesses and accountants while lifting ARPU through richer workflows like AI, payments and payroll. The Gemini integration fits that story but does not fundamentally change it on its own. The more pressing short term focus is execution on product bundling and pricing without confusing or alienating users.
The biggest near term risk still sits around profitability and churn. Profit margins at 6.1% are below last year, and promotional pricing or complex packaging could pressure both ARPU and retention. The Gemini launch may help user engagement, but any financial impact or cost drag will take time to show up clearly in reported numbers.
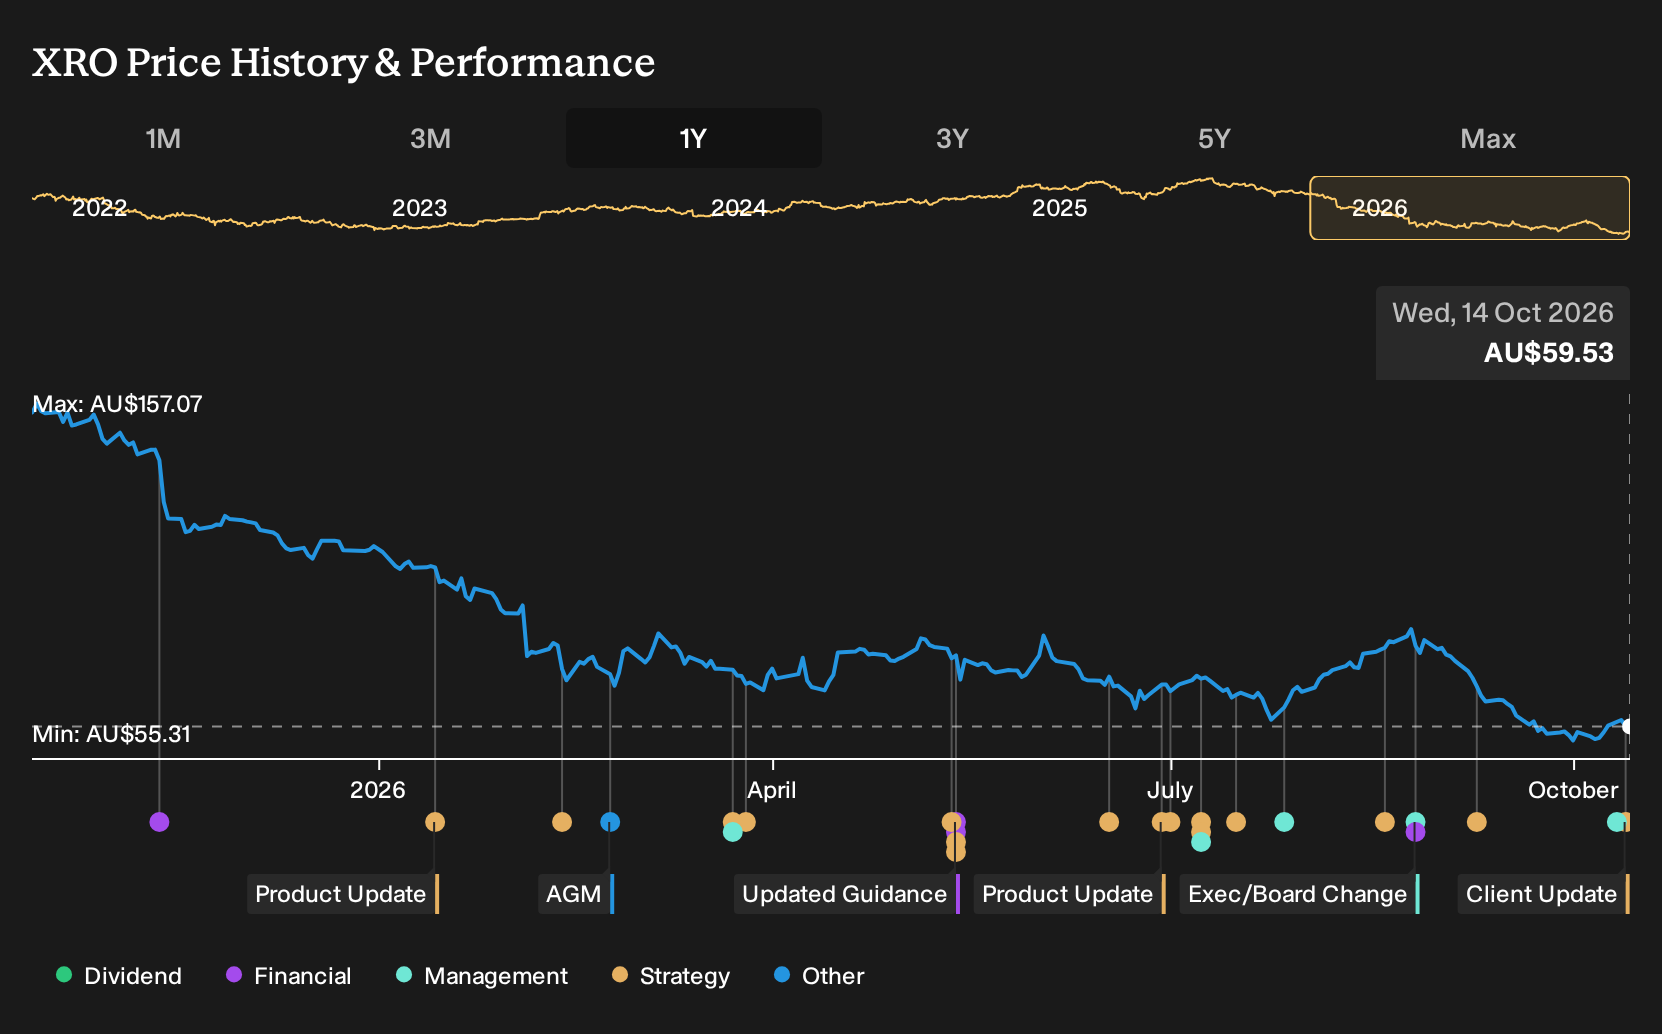
The most relevant side announcement here is the appointment of Mark Durcan as an independent Non Executive Director on 12 October 2026. Xero is leaning harder into AI driven features, and a board member with long experience at Micron and current roles at ASML and Cencora adds extra technical depth to governance as those bets scale.
For you as a shareholder, the key question is whether product decisions around Gemini, JAX and other AI tooling translate into stickier usage rather than simply generating headlines. Board refresh supports oversight, but execution risk remains around rising operating expenses, particularly where hiring specialist talent in high cost markets could run ahead of revenue and keep return on equity low at 3.1%.
Xero's current analyst narrative points to NZ$5.2b in revenue and NZ$611.1m in earnings by 2029, based on expectations of 24.0% yearly top line growth. That profile assumes earnings rise by about NZ$443.7m from NZ$167.4m today to the 2029 consensus level.
Uncover why Xero's fair value indicates a 105% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view treats the Gemini integration as potential fuel for the most optimistic Xero story. Bullish analysts were already building in NZ$6.2b of revenue and NZ$788.5m of earnings by 2029, far above consensus. You can read that as a sign opinions diverge sharply and that Gemini era workflows might push those narratives to shift again.
Explore 7 other Xero fair value estimates, including one that suggests potential upside of as much as 238% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Xero research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Xero. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Xero's overall financial health at a glance.
Looking For More Investment Ideas Beyond Xero?
If the Xero story has you thinking about where else AI, balance sheet strength, or income resilience might matter, it can help to widen the lens and scan a broader watchlist using the Simply Wall St Screener.
- For investors who want potential mispricings backed by solid fundamentals, start with a curated group of 4 high quality undervalued stocks that may warrant a closer look.
- If capital preservation sits high on your priority list, focus on businesses that score well on financial strength and risk, using a 6 resilient stocks with low risk scores to narrow the field.
- Those hunting for quality that is not already crowded can review a 15 high quality undiscovered gems that filters for strong fundamentals without heavy market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com