
Kingfisher (LSE:KGF) Names New CEO On Questions Over Whether The Stock Is Fully Valued
Kingfisher (LSE:KGF) put succession firmly on the agenda after naming Sebastian Gundel as its next chief executive, with interim leadership in place ahead of his February 2027 start.
Recent trading has been upbeat for Kingfisher, with a 30 day share price return of 14.97% and a 90 day gain of 11.41% at a latest share price of £3.31. The 1 year total shareholder return of 14.22% and 3 year total shareholder return of 84.14% point to momentum that investors appear to be reassessing in light of the CEO transition and ongoing execution on its home improvement focus.
Spot similar home improvement and retail stories in motion by scanning our curated list of 5 high quality undiscovered gems, which, like Kingfisher, connect operational execution to evolving leadership and digital execution themes.Kingfisher looks like a solid home improvement retailer with clear leadership plans and recent share price strength. The real issue now is whether that quality and momentum are already fully reflected in the £3.31 valuation.
Most Popular Narrative: 6% Overvalued
Kingfisher’s most followed valuation storyline puts fair value at £3.12, slightly below the latest £3.31 close. This raises a simple question for investors about how much optimism is already in the price.
Kingfisher's e-commerce growth and increased penetration, aiming for 30% of total sales, along with the implementation of new technologies and marketplaces, is projected to significantly boost revenue and margin given the higher profitability of online sales compared to traditional retail.
See why 18 investors see Kingfisher as 6% overvalued.
Result: Fair Value of £3.12 (OVERVALUED)
Still, softer like-for-like sales and restructuring costs in France and Turkey could pressure Kingfisher’s margins and challenge the current overvaluation story.
Find out about the key risks to this Kingfisher narrative.
Another View on Kingfisher’s Valuation
The first storyline has Kingfisher looking slightly overvalued at £3.12 against a £3.31 share price. A different lens tells a sharper story. Our DCF model points to a future cash flow value of £3.78, which implies the current quote sits below that estimate and presents today’s price as a potential gap for you to examine.
Look into how the SWS DCF model arrives at its fair value.
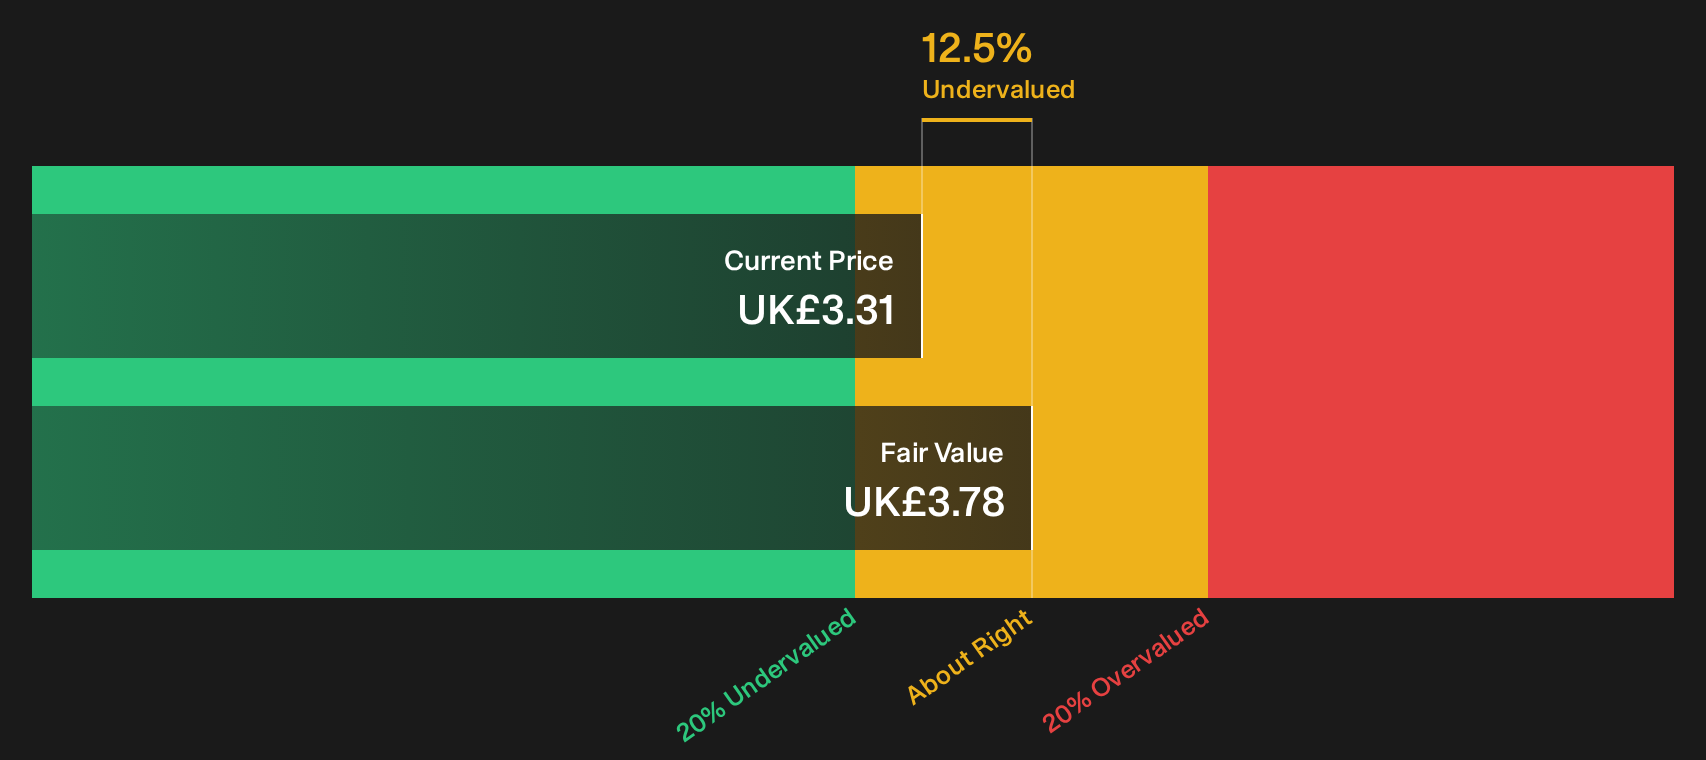
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kingfisher for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 8 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
That mix of enthusiasm and caution around Kingfisher only matters if you put the numbers in context for yourself and act while the narrative is still evolving. Weigh both the upside and the red flags directly through the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Kingfisher?
If you only stop at Kingfisher, you miss a wider field of opportunities that could better match your risk tolerance, dividend needs, or value focus.
- Target stronger payouts by reviewing companies in our 3 dividend fortresses to see which businesses pair income potential with balance sheet support.
- Hunt for mispriced quality by working through the 8 high quality undervalued stocks that surfaces stocks with solid fundamentals at compressed valuations.
- Prioritise capital preservation and steadier compounding by scanning the 4 resilient stocks with low risk scores that filters for resilient operations and more contained risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com