
Atalaya Mining Copper (LSE:ATYM) Gets EU Backing For Proyecto Touro But Is The Valuation Priced In
Why Proyecto Touro’s EU Status Matters For Atalaya Mining Copper
Atalaya Mining Copper (LSE:ATYM) recently had its Proyecto Touro asset recognised as a Strategic Project under the EU’s Critical Raw Materials Act, putting official weight behind its role in Europe’s copper supply chain.
This label points to potential tailwinds for permitting timelines, financing options and technical support. For shareholders, the news places a regulatory spotlight on a project that had already been central to Atalaya’s growth narrative.
Investors have already been pricing in some of this story, with Atalaya Mining Copper’s share price advancing over the past quarter and year to date. The 1-year and 3-year total shareholder returns of 55.51% and about 2.7x highlight how momentum has been building rather than fading.
Scan a curated group of copper producers benefiting from similar EU and electrification tailwinds by reviewing the 16 top copper producer stocks alongside Atalaya Mining Copper’s latest catalyst.
After a 55.51% 1-year total return and fresh momentum around Proyecto Touro, does stepping into Atalaya Mining Copper at £10.27 still stack up, or does it pay to wait for a better entry before the next leg of the thesis?
Most Popular Narrative: 20% Undervalued
Against a narrative fair value of about £12.88, Atalaya Mining Copper at £10.27 screens as discounted, with that gap largely hinging on whether growth projects and cash generation play out as expected.
Atalaya is nearing key milestones on growth projects, notably the expected permitting and subsequent 18-month development of Proyecto Touro. The project is projected to add 30,000 tonnes of copper per year at significantly lower cash costs than current operations, which in turn is expected to materially increase future revenues and improve consolidated net margins by lowering the company's overall unit cost base.
See why 38 investors see Atalaya Mining Copper as 20% undervalued.
Result: Fair Value of £12.88 (UNDERVALUED)
Still, Atalaya Mining Copper’s story depends heavily on obtaining timely permits at projects such as Proyecto Touro and on avoiding cost or currency pressures that could squeeze margins.
Find out about the key risks to this Atalaya Mining Copper narrative.
Another View: What The P/E Says About Atalaya Mining Copper
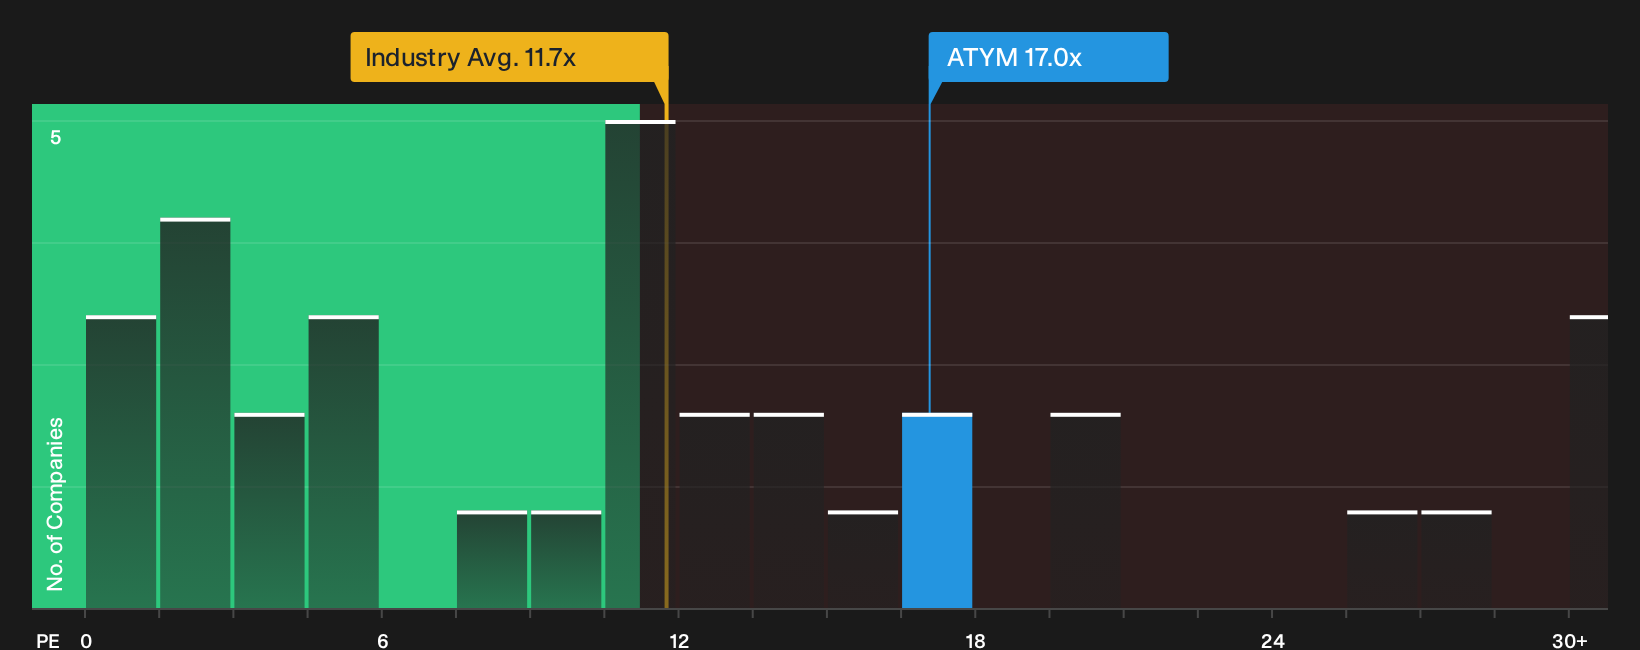
Analyst models point to a fair value of £12.88, yet the market is currently pricing Atalaya Mining Copper on a P/E of about 17x. That is higher than the 11.7x average for the UK Metals and Mining group, although it sits below the peer average of 20.1x and close to a fair ratio of 18.8x.
For you as a shareholder, that mix means the stock is more expensive than the wider industry but not stretched against similar businesses or the fair ratio the market could drift toward. The question is whether you view that gap as valuation risk if expectations cool, or as room for the P/E to catch up if the growth story holds.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Atalaya Mining Copper story leans positive, yet the decision still comes down to your own homework and timing. Put the recent gains and project headlines in context by weighing the potential upside against the risks highlighted in the data, and then dig into the 3 key rewards.
Looking for more investment ideas beyond Atalaya Mining Copper?
If Atalaya Mining Copper already sits on your radar, rounding out your watchlist with a few targeted themes can help you spot opportunities you might otherwise miss.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive valuations through the 8 high quality undervalued stocks.
- Strengthen your income stream by reviewing the 3 dividend fortresses that focus on sizeable yields backed by robust payouts.
- Prioritise resilience by checking the 4 resilient stocks with low risk scores that flag businesses with relatively lower risk scores and steadier profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com