
Hydro One (TSX:H) Could Be 8% Below Fair Value On Its 5 Year Investment Plan
Hydro One (TSX:H) has popped back onto investor radars after winning major Ontario Energy Association awards for supply chain leadership and diversity, along with fresh attention on its new five year investment plan and upcoming earnings.
Recent trading has been choppy for Hydro One, with the share price down about 11% over the past 90 days and roughly 4% lower year to date. However, the 1 year total shareholder return of 3.4% and 5 year total shareholder return of about 2x suggest longer term holders have seen steadier gains.
Scan beyond Hydro One and see how other regulated utilities and infrastructure players stack up in our curated 43 power grid technology and infrastructure stocks.
Hydro One trades around CA$52 after a choppy few months, which leaves you weighing two paths: lean into the pullback now, or wait and see what the current valuation actually implies.
Most Popular Narrative: 8% Undervalued
On the most followed view, Hydro One’s fair value sits around CA$56.67, which is modestly above the latest close near CA$52.24. That gap rests on a long list of grid projects, regulatory assumptions and funding choices that need to line up over time.
Hydro One’s proposed $37b of transmission and distribution investments for 2028 to 2032, aimed at modernizing aging infrastructure and connecting about 6,000 MW of new demand, would add materially to the regulated rate base and support future revenue and earnings growth.
See why 33 investors see Hydro One as 8% undervalued.
Result: Fair Value of CA$56.67 (UNDERVALUED)
Still, the story around Hydro One can change quickly if regulators stay tough on cost recovery, or if the C$37b build program faces timing or approval setbacks.
Find out about the key risks to this Hydro One narrative.
Another View: Hydro One Through The P/E Lens
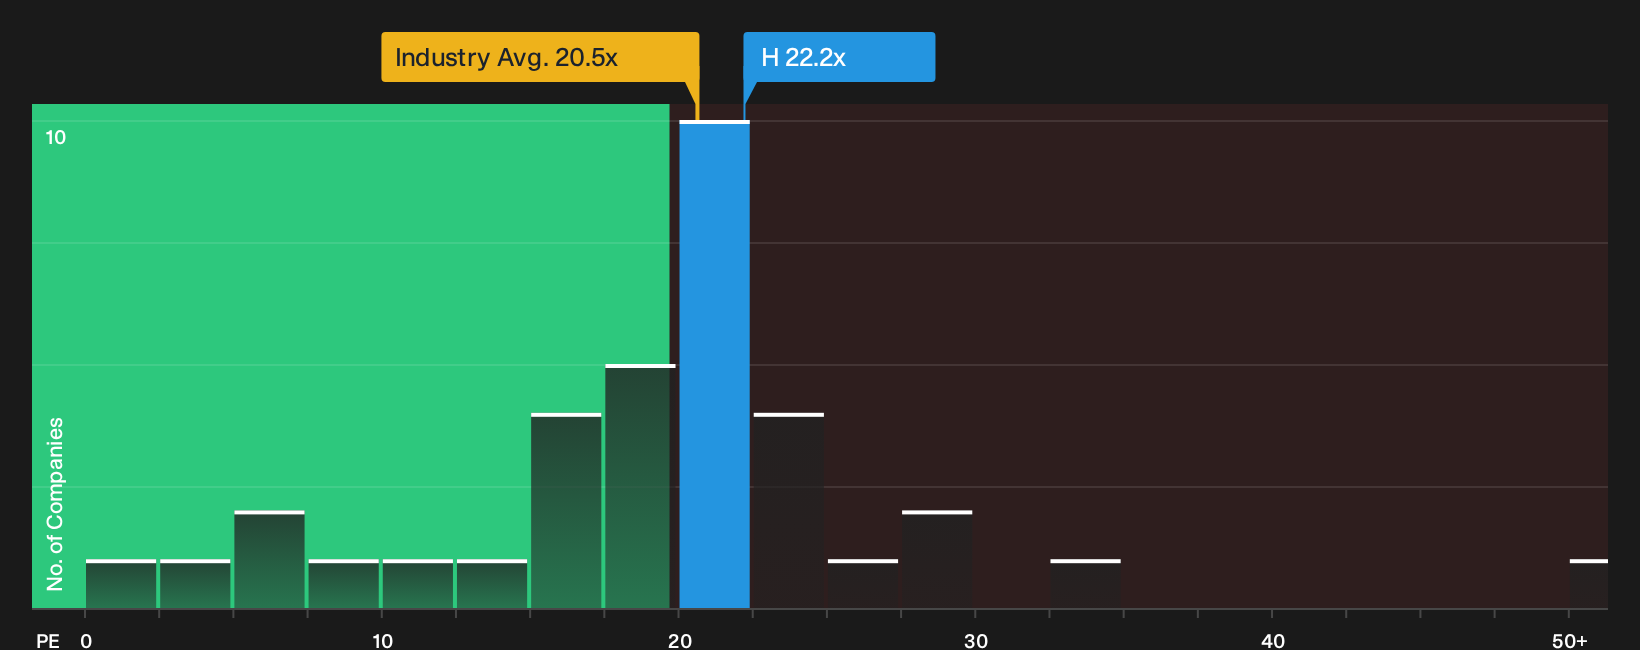
Analyst models lean toward Hydro One being undervalued, yet the market is asking you to pay a P/E of about 22.2x. That is higher than both the North American electric utilities group on 20.5x and the fair ratio estimate of 27.4x, which suggests less of a clear bargain and more of a debate about how much safety you really get at this price.
To understand how that gap between current P/E, peers and the fair ratio could close, and what it might mean for upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Hydro One so far. If you want to move quickly and build your own take from the ground up, start with the 3 key rewards and 2 important warning signs.
Looking for more Hydro One style investment ideas?
Do not stop your work at Hydro One alone. Broaden your watchlist with fresh ideas built from powerful screeners that highlight different types of opportunities.
- Target stronger upside potential with companies that combine quality fundamentals and attractive pricing by checking the 7 high quality undervalued stocks.
- Lock in income focused opportunities by reviewing the 3 dividend fortresses before the next round of payouts passes you by.
- Lower portfolio stress by filtering for sturdier businesses on the 8 resilient stocks with low risk scores so you are not scrambling after the next market shock.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com