
State Street (STT) Stock Falls Despite Fee Growth And EPS Strength
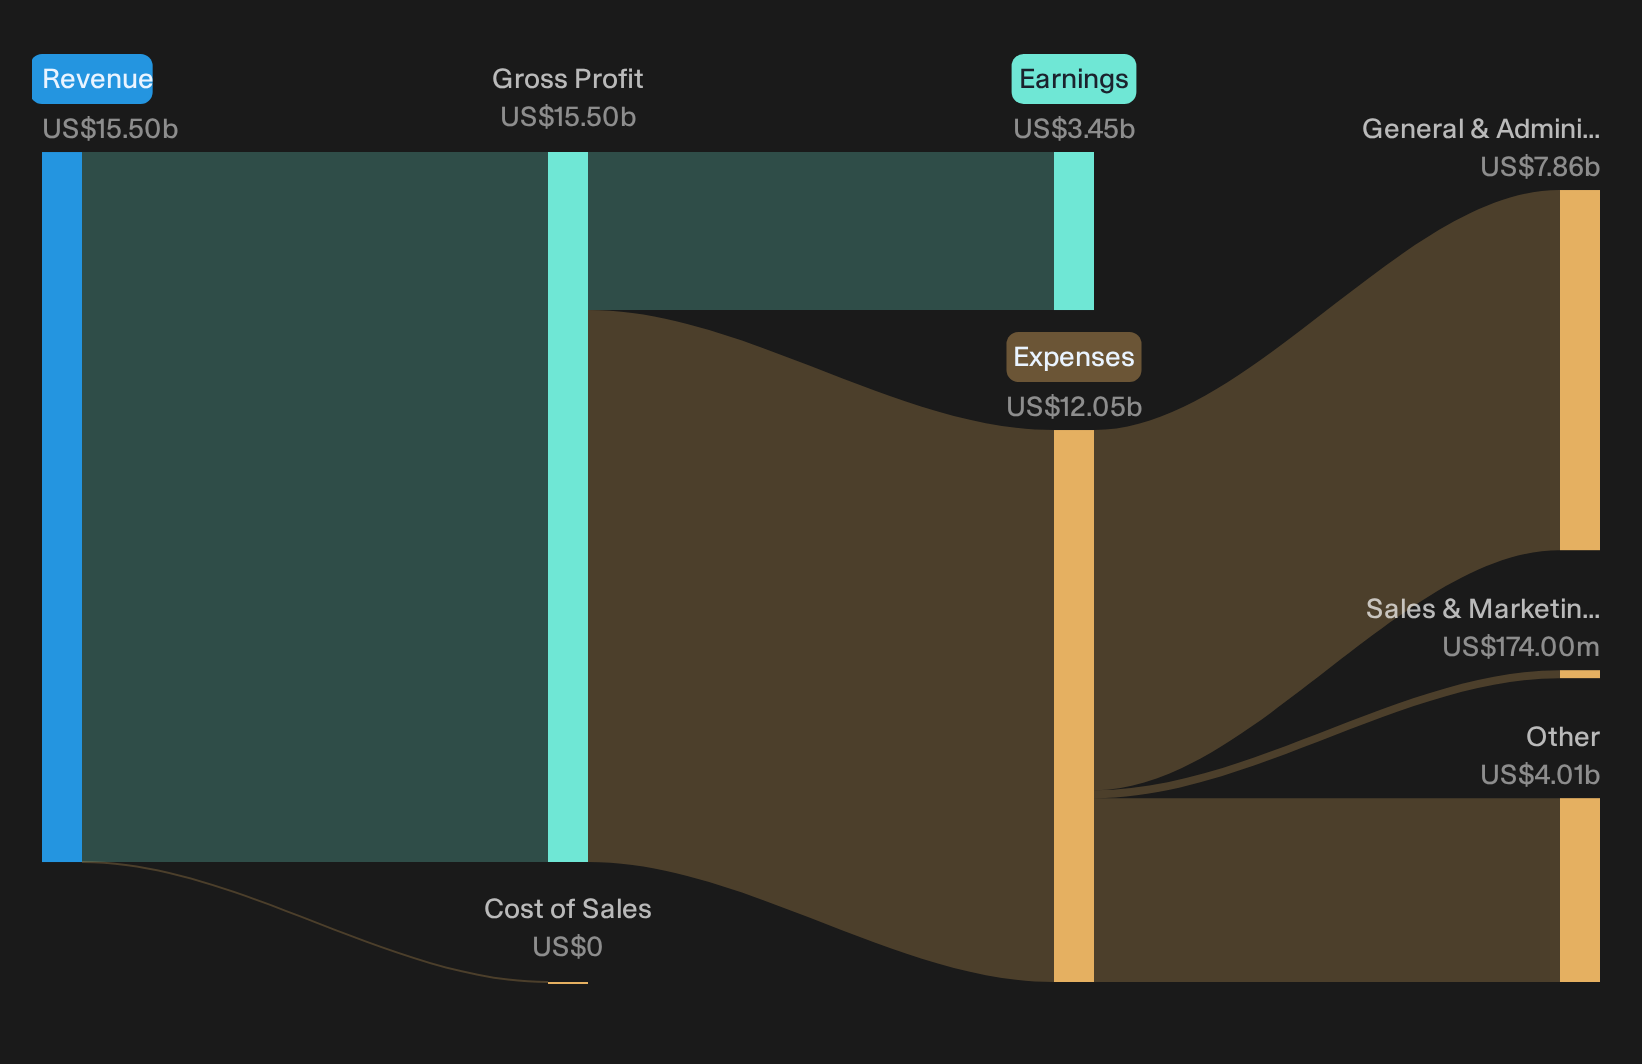
State Street entered this quarter with a stock that had already cooled, down over 10% across the past month, then it dropped another 4% today after the release. That slide jars with the headline story. The bank reported about US$4.0b of quarterly revenue and roughly US$3.76 of basic earnings per share, both tied to strong fee and net interest income engines that management has been working to scale.
For investors, the real surprise is not weak earnings. It is the gap between a firm talking about double digit fee growth, rising net interest income and a market that is still hitting the sell button.
Is State Street a genuine bargain after this 10% slide, or is the lower price simply catching up with the story in the numbers? See how the current multiple compares to intrinsic value in our independent valuation analysis for State Street.
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$4,008m vs. US$3,536m (up about 13%)
- Net Income excl. Extra Items (Q3 2026 vs. Q3 2025): US$1,030m vs. US$802m (up about 28%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$3.76 vs. US$2.83 (up about 33%)
- Assets Under Management, AUM (End of Period, Q3 2026 vs. Q3 2025): US$6,278,000m vs. US$5,446,000m (up about 15%)
Prefer clean charts over another wall of earnings tables and filings for State Street? View the full visual picture of the business, including how valuation compares with recent results, in the interactive company report for State Street.
State Street bull case hits scale, questions durability
Bulls argue State Street’s scale and One State Street model can turn record assets and fee pools into steadily rising, high quality earnings. Q3 does hit several checkpoints. Servicing fees reached about US$1.5b, with assets under custody and administration climbing to US$59.2t. Management fees also set a new high at US$797m on US$6.3t of AUM, helped by six straight quarters of net inflows and record ETF assets of US$2.3t. That supports the idea that SPDR, co branded ETFs and cross selling are gaining traction. Efficiency targets also look supported. The firm delivered a 35% pretax margin and cited roughly 530 bps of positive operating leverage with adjusted expenses rising slower than total revenue. So the bullish story around scale, product breadth and cost discipline finds real backing, even if the reset in fee guidance hints that growth may come through a bumpier path than fans of the story hoped.
Bear case flags fee pressure and expectations reset
Skeptics worry that fee compression, product churn and high expectations leave State Street exposed when growth cools. This quarter gives them some support. The share price dropped about 4% today and is down roughly 10% over 90 days, and management cut full year fee revenue guidance to a range of 13% to 14%, which they framed as below earlier investor expectations. Total revenue fell short of what many were looking for even as EPS beat, helped by a 25% ROTCE and firm cost control. That mix fuels the concern that earnings are leaning more on net interest income and buybacks, with less comfort on long run fee momentum. Product level moves like ETF closures and sales lumpiness also feed the idea that growth is patchy rather than smooth. Bears do not get a clear structural break, but they do get evidence that the easy part of the fee recovery is likely behind the business.
Compare State Street’s internal story of scale, record AUM and fee engines with the external verdict from Wall Street. See the consensus price target analysis for State Street to check how analyst targets line up with the latest selloff.Stay Ahead Of Your Next Move
State Street just delivered strong Q3 headline numbers while the share price fell, which is exactly the kind of disconnect you want to track closely. Register for free with Simply Wall St and add it to a Watchlist to keep an eye on price versus fair value and watch for an entry point that fits your plan. Once you own it, use the Portfolio Command Center to cut through noise and focus on the key updates that actually affect your holdings. Round that out with crowd insight by tapping into the Community so you can spot hidden catalysts and risks early and stay a step ahead of the market.
Seeking Alternatives Beyond State Street?
Fresh ideas move fast. Stocks building quiet momentum today can be flying or dropping out of reach once the crowd catches on. Scan these focused shortlists and consider getting in early.
- Spot sturdier balance sheets before stress hits by reviewing the list of solid balance sheet and fundamentals stocks (25 results) and see which businesses still look ready to hold up when conditions change.
- Explore potential income plus price swings by using the 7 dividend fortresses and focus on higher yield opportunities that others may be overlooking for now.
- Track early movers in automation by scanning the 90 robotics and automation stocks so you are not caught watching tomorrow’s industrial leaders from the sidelines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com