
Citigroup (C) Stock Cools As Profit Strength Meets Regulatory Drag
Citigroup went into this earnings print with a stock that had already cooled, down about 10% over the past month, and the immediate reaction stayed cautious as shares slipped another 1.8% today. That market chill sits alongside a quarter where net income reached about US$4.8b and basic earnings per share came in near US$2.90, supported by a cost to income ratio of 58.5% that keeps efficiency in focus.
Love Citigroup's earnings power but uneasy about the recent share pullback and sector overhangs on big banks? Check out the list of solid balance sheet and fundamentals stocks (25 results) for a basket of stocks built around balance sheet strength and disciplined cost control.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$21,423m vs. US$19,836m (up about 8%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$4,840m vs. US$3,439m (up about 41%)
- Basic EPS (Q3 2026 vs Q3 2025): US$2.90 vs. US$1.89 (up about 53%)
- Cost to Income Ratio (Q3 2026 vs Q3 2025): 58.5% vs. 64.7% (improved efficiency)
Prefer clear visuals instead of scrolling through dense tables of bank ratios and capital metrics? Get a full picture of Citigroup, including how the market is valuing the business today, in an easy-to-scan visual format with our company report for Citigroup.
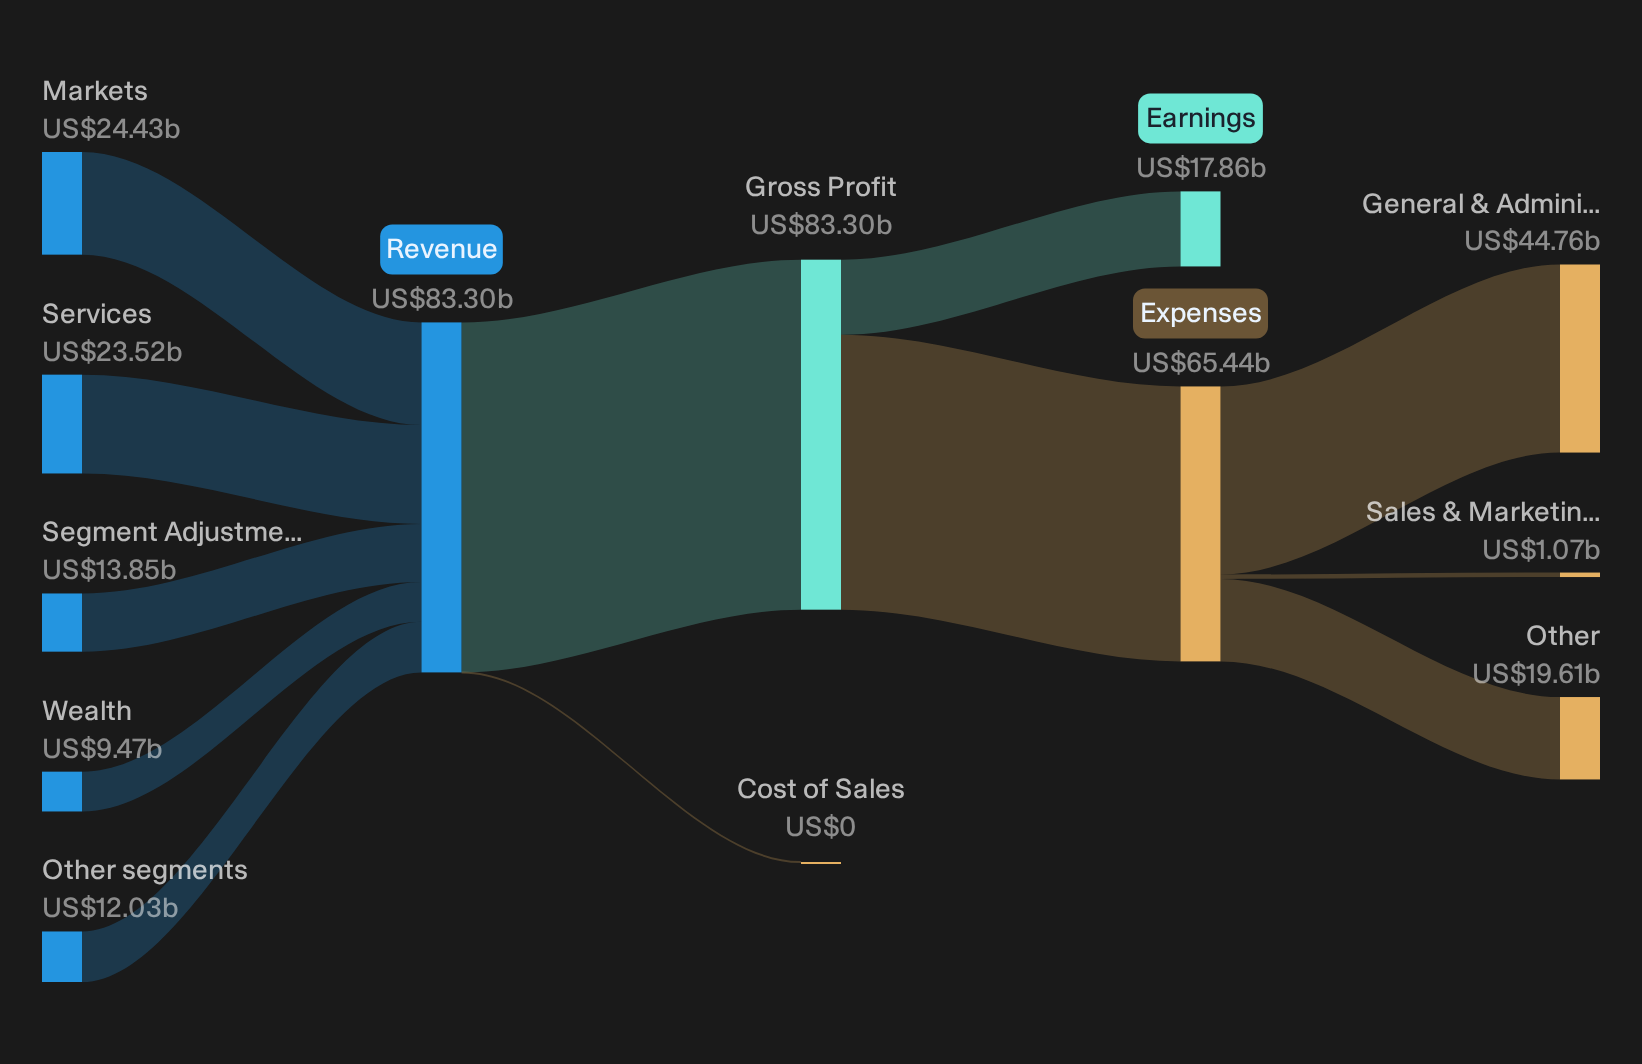
Citi’s Bulls Lean On Revenue Power And Efficiency
Citigroup gives the more optimistic story real backing. Net income around US$5.2b, EPS near US$2.85 and revenue of US$23.8b for Q3, described as the best third quarter in a decade, line up with a value turnround pitch built on earnings power rather than hype. A cost to income ratio under 60% and positive operating leverage support the idea that the broad global platform, from Services to Wealth, is now generating more profit from each dollar of income.
Regulation, Credit And Market Reaction Temper The Bulls
There is still plenty for cautious investors to point to. The share price slipped about 2% on the day and is down roughly 10% over 30 days, which indicates the market is not rushing to reward Citigroup for stronger results. Regulatory fines and ongoing consent orders, plus a US$9b Banamex charge expected in 2027, keep the legacy complexity story alive. A firm wide reserve build of US$369m and US$22b of total reserves also indicates that credit risk remains a central focus.
Reveal how that mix of stronger Q3 earnings, a tighter cost base and a share price that just declined 1.8% today compares with Wall Street sentiment by checking the consensus price target analysis for Citigroup
Own Your Next Investing Move
Citigroup just delivered stronger Q3 numbers while the share price pulled back, which can create opportunity if you time your entry carefully, so register for free with Simply Wall St and add it to a Watchlist to track price against fair value and wait for conditions that fit your plan. Once you are invested, keep your decisions grounded in data by using the Portfolio Command Center that cuts through market noise and surfaces the updates that matter most to your holdings. For longer term decisions, tap into the Community to see how other investors are interpreting the same results and risks. That mix of tools helps you spot potential catalysts and red flags early so you can stay a step ahead of the broader market.
Seeking Fresh Alternatives Beyond Citigroup
Fresh opportunities do not wait. Breakout moves, fading entries and dropping risk rewards tend to get caught early by investors who act before the crowd while it matters, so get in early.
- Spot early momentum in companies quietly building earnings strength by running the 32 resilient stocks with low risk scores before those stories move from under the radar to the front page.
- Track cash rich businesses where dividends may help steady returns and potential upside may come from renewed buying pressure using the curated 7 dividend fortresses list.
- Target upcoming infrastructure and hardware beneficiaries of AI demand by scanning the hand picked 92 AI infrastructure stocks that focuses on reported revenues, not just headlines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com