
Alkane Resources (ASX:ALK) Just Gave The Market Something To Think About
Alkane Resources updates production, sales and guidance
Alkane Resources (ASX:ALK) has put fresh numbers on the table, reporting first quarter gold production of 40,740 AuEq oz and sales of 38,348 Au oz, while it reaffirmed its FY27 output and cost guidance.
Recent trading shows Alkane Resources giving back some ground in the short term, with the 1 month share price return down 7.18% and the 7 day move lower as well. However, the 90 day share price return of 25.54% and 1 year total shareholder return of 52.68% point to momentum that has been building over a longer stretch.
Scan for other gold producers showing similar operational updates and price momentum to Alkane Resources by running our curated 35 elite gold producer stocks alongside this announcement.
Alkane Resources now trades well below both analyst targets and one estimate of intrinsic value, yet the recent pullback hints at caution. Is that discount compensation for risk, or hesitation that the numbers do not fully support?
Most Popular Narrative: 79.6% Undervalued
On the latest numbers, Alkane Resources closed at A$1.75, while the most followed narrative pegs fair value at A$8.54, implying a very wide gap between price and that assessment.
The bull case is simple, Alkane is no longer just a developer or single-mine producer. It is now a cash-generating multi-mine platform with gold production, antimony exposure, copper optionality, a stronger balance sheet, and one large-scale development asset in Boda-Kaiser. The company reported record Q3 FY2026 production of 45,776 gold-equivalent ounces and maintained FY2026 group guidance of 160,000 to 175,000 gold-equivalent ounces at AISC of A$2,600 to A$2,900 per ounce.
See why 13 investors see Alkane Resources as 80% undervalued.
According to RTRockeTeller, who authored the narrative, that valuation rests on Alkane Resources already operating three mines, holding A$374m in cash, bullion and listed investments, and having long dated growth potential through the Boda Kaiser gold copper project rather than on a single deposit story.
The same narrative also leans on very strong recent earnings momentum alongside a 24.4% net margin and 20.5% return on equity, with earnings growth over the past year described as much higher than the 5 year average. This helps support the idea that the current P/E of 10.4x could be low compared with an estimated fair P/E of 16x for this business profile.
Set against that, the writer flags real pressure points for Alkane Resources including higher cost output at the Bjorkdal mine, the A$1.8b pre production capex estimate for Boda Kaiser and post merger complexity across three jurisdictions. These factors may help explain why the market is assigning a steep discount to that A$8.54 narrative fair value.
Result: Fair Value of A$8.54 (UNDERVALUED)
Still, Alkane Resources faces clear swing factors, including Bjorkdal’s higher cost base and the A$1.8b Boda Kaiser capex, which could stretch the balance sheet.
Find out about the key risks to this Alkane Resources narrative.
Another View: Alkane Resources through the earnings lens
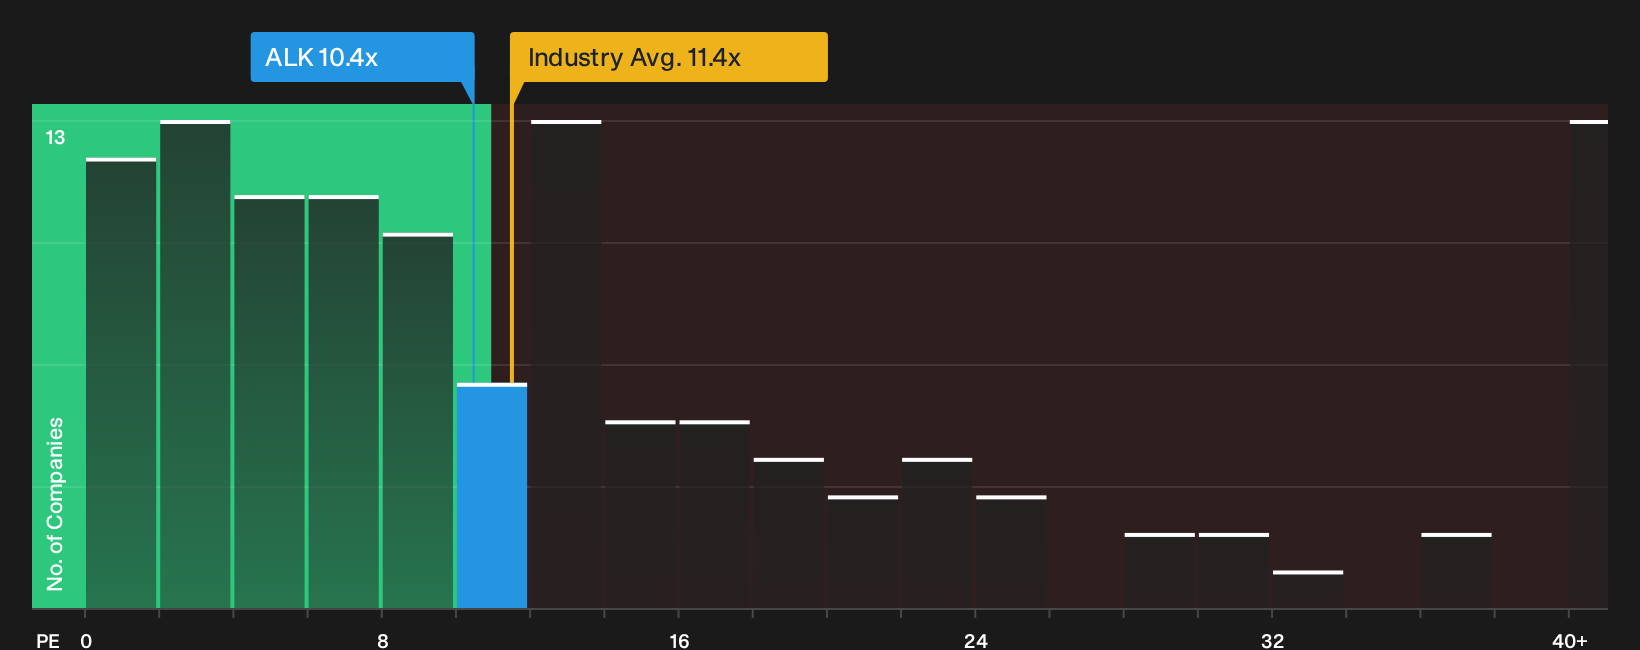
The narrative fair value for Alkane Resources leans on high gold-price scenarios and asset depth. A simpler yardstick is the current P/E of 10.4x, which sits above a 7.8x peer average, yet below the Australian metals and mining sector on 11.4x and the 16x fair ratio estimate.
That mix points to a stock that screens expensive versus closer peers, but cheaper than the wider industry and well under a ratio the market could move toward if earnings quality and returns on equity stay where they are. Does that blend of caution and potential appeal to you, or does it feel like valuation risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Alkane Resources so far, right, with clear risk flags on one side and meaningful upside arguments on the other. Move fast and pressure test the data yourself by weighing up the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Alkane Resources?
Do not park all your attention on Alkane Resources when there are other opportunities that might better match your goals and risk comfort.
- Hunt for quality at a discount by scanning our hand picked pool of 4 high quality undervalued stocks that pair stronger fundamentals with appealing pricing signals.
- Strengthen your income mix by reviewing a focused set of 3 dividend fortresses that combine higher yields with defensiveness on payouts.
- Sleep easier at night by filtering for 6 resilient stocks with low risk scores that score well on resilience and financial robustness so surprises are less likely.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com