
Antofagasta (LSE:ANTO) Strike Deepens At Centinela, Is The Stock Already Fully Valued?
Workers at Antofagasta (LSE:ANTO)'s Centinela copper mine have escalated a three day strike into a hunger strike by several union members, raising fresh questions for investors around production continuity and sector wide copper supply.
Recent trading shows some pressure on Antofagasta’s share price, with a 7 day share price return of 3.25% and a 30 day share price return of 0.39% in the context of a £35.72 last close. Longer term performance remains strong given a 1 year total shareholder return of 30.66% and a 5 year total shareholder return of 181.20%, suggesting momentum has built over time even as near term events such as the Centinela strike have sharpened focus on operational risk.
Compare how Antofagasta’s strike related risk stacks up against other copper producers by scanning our hand picked 16 top copper producer stocks in one place.
Recent gains and a live strike leave Antofagasta looking finely balanced between earnings risk and a £35.72 price tag that already reflects a strong five year run. This raises the question of how much upside the current valuation still suggests.
Most Popular Narrative: 8% Undervalued
Set against Antofagasta’s £35.72 last close, the most followed narrative anchors on a fair value of about £38.88, which implies a modest discount and puts fresh weight on how the copper growth story holds up against current risks.
Antofagasta's ongoing brownfield expansions at Centinela and Los Pelambres (including new concentrator, water system upgrades, and pipeline replacements) are projected by management to increase copper production by approximately 30% upon completion, which would support higher revenues and operating leverage if achieved.
See why 19 investors see Antofagasta as 8% undervalued.
Result: Fair Value of £38.88 (UNDERVALUED)
Still, Antofagasta’s heavy reliance on copper and exposure to Chilean water constraints mean that any disruption to output or costs could quickly challenge this undervaluation story.
Find out about the key risks to this Antofagasta narrative.
Another View: Antofagasta Through The P/E Lens
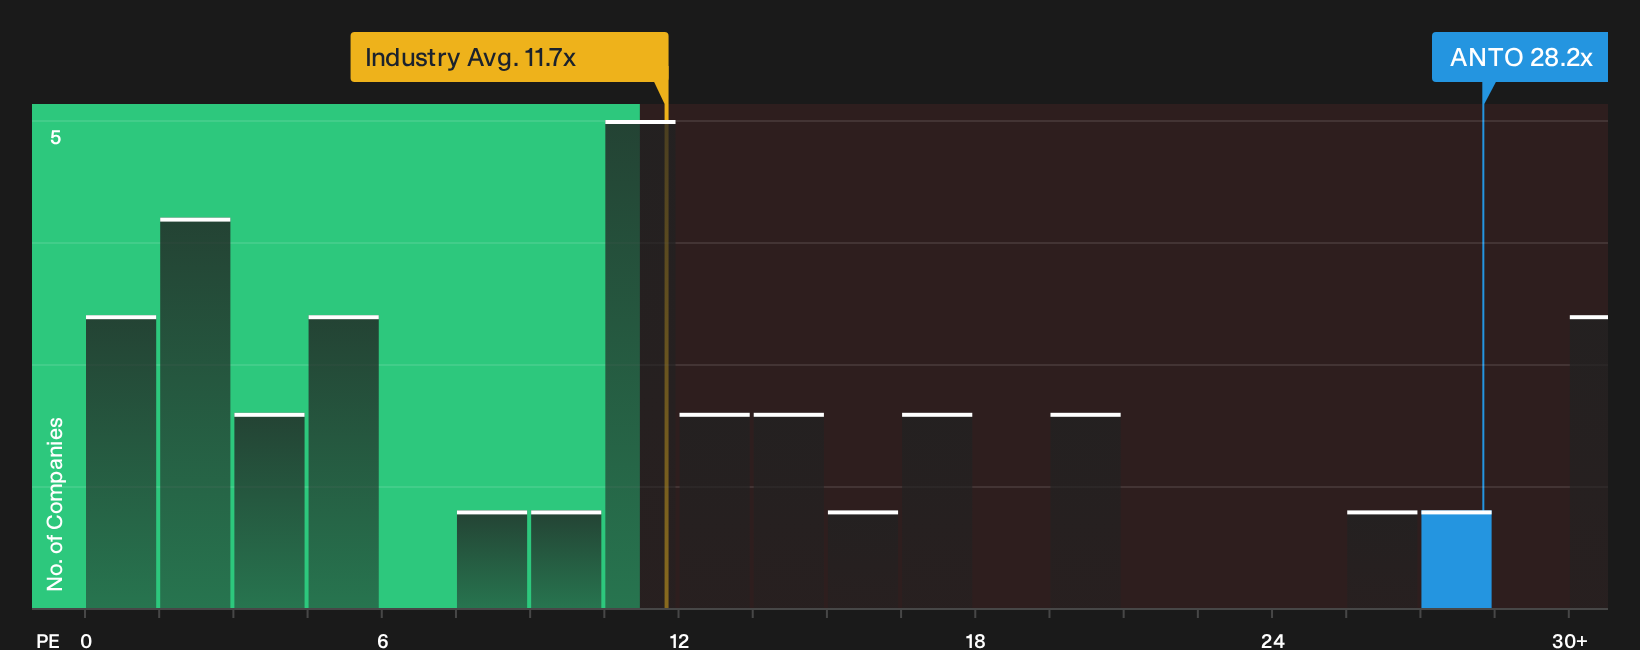
The earlier fair value of £38.88 paints Antofagasta as modestly undervalued, yet the earnings multiple tells a different story. The shares trade on a P/E of 28.2x, which is very rich compared with the UK Metals and Mining sector on 11.7x and a peer group on 14.3x.
Even against an estimated fair ratio of 21.4x, the current P/E looks stretched. This points to less room for disappointment if copper volumes, costs, or project delivery wobble. For an investor weighing these signals, the question is which lens feels more realistic when a live strike is in the mix.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Strikes, valuations, and copper exposure all spark strong opinions. Use this as a starting point, then move quickly to stress test your own thesis with 3 key rewards
Looking for more Antofagasta sized ideas?
If you only stop at Antofagasta, you risk missing other opportunities. Use the screener to spot setups that better match your own risk and return goals.
- Target resilient income by reviewing 2 dividend fortresses that aim to combine higher yields with balance sheets that can better support ongoing payouts.
- Hunt for mispriced potential through 5 high quality undiscovered gems, where strong fundamentals have not yet attracted broad attention.
- Prioritise capital preservation with 4 resilient stocks with low risk scores, focused on businesses that score well on financial strength and volatility checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com