
Will Board Appointment Change Rathbones Group's (LSE:RAT) Integration Story
- Rathbones Group has added Michelle Sylvia Scrimgeour to its board as a director, with her appointment effective from 1 October 2026.
- The new board member arrives while Rathbones Group is still working through the complex integration of Investec Wealth & Investment and related cost and client pressures.
- We will now explore how Rathbones Group's investment narrative could shift as a new director joins during the Investec integration.
Scan for other asset and wealth managers facing similar integration and valuation questions by checking our curated list of 8 high quality undervalued stocks while you assess what this new director means for Rathbones Group.
Rathbones Group Investment Narrative Recap
To own Rathbones Group, you need to believe the Investec Wealth & Investment integration can still translate scale into healthier margins despite the share price being down 18.2% year to date and revenue forecast to drift lower. The key near term swing factor remains how effectively management turns the enlarged platform into stable, fee based earnings while keeping one off costs contained.
The biggest risk is that client outflows, pressure from lower fee products and integration friction erode returns on capital faster than efficiencies arrive. Michelle Scrimgeour joining the board does not materially change that equation in the short run. Execution discipline on costs, service quality and digital delivery still drives the outcome.
Among the recent information, the clearest operational reference point is management’s target of a 28% operating margin by Q4 2026 and full Investec synergy benefits of about £60m annualised by the end of 2025. That ambition sits against current concerns about revenue softness, margin compression in multi asset funds and sensitivity to market moves.
For you as a shareholder, those margin goals effectively act as a scoreboard for both the integration and any governance refresh such as Scrimgeour’s appointment. If Rathbones Group edges closer to those targets while stabilising assets and defending fee rates, investors are likely to focus more on earnings resilience. If outflows and pricing pressure persist, the risk side of the story will stay front of mind.
Rathbones Group is currently framed around analysts expecting fairly flat revenue over the next few years, with forecasts pointing to about £991.3 million of revenue and £152.2 million of earnings by 2029. This would mean earnings rising by roughly £39.9 million from £112.3 million today.
Uncover why Rathbones Group's fair value indicates a 28% potential upside to its current price that may not last much longer.
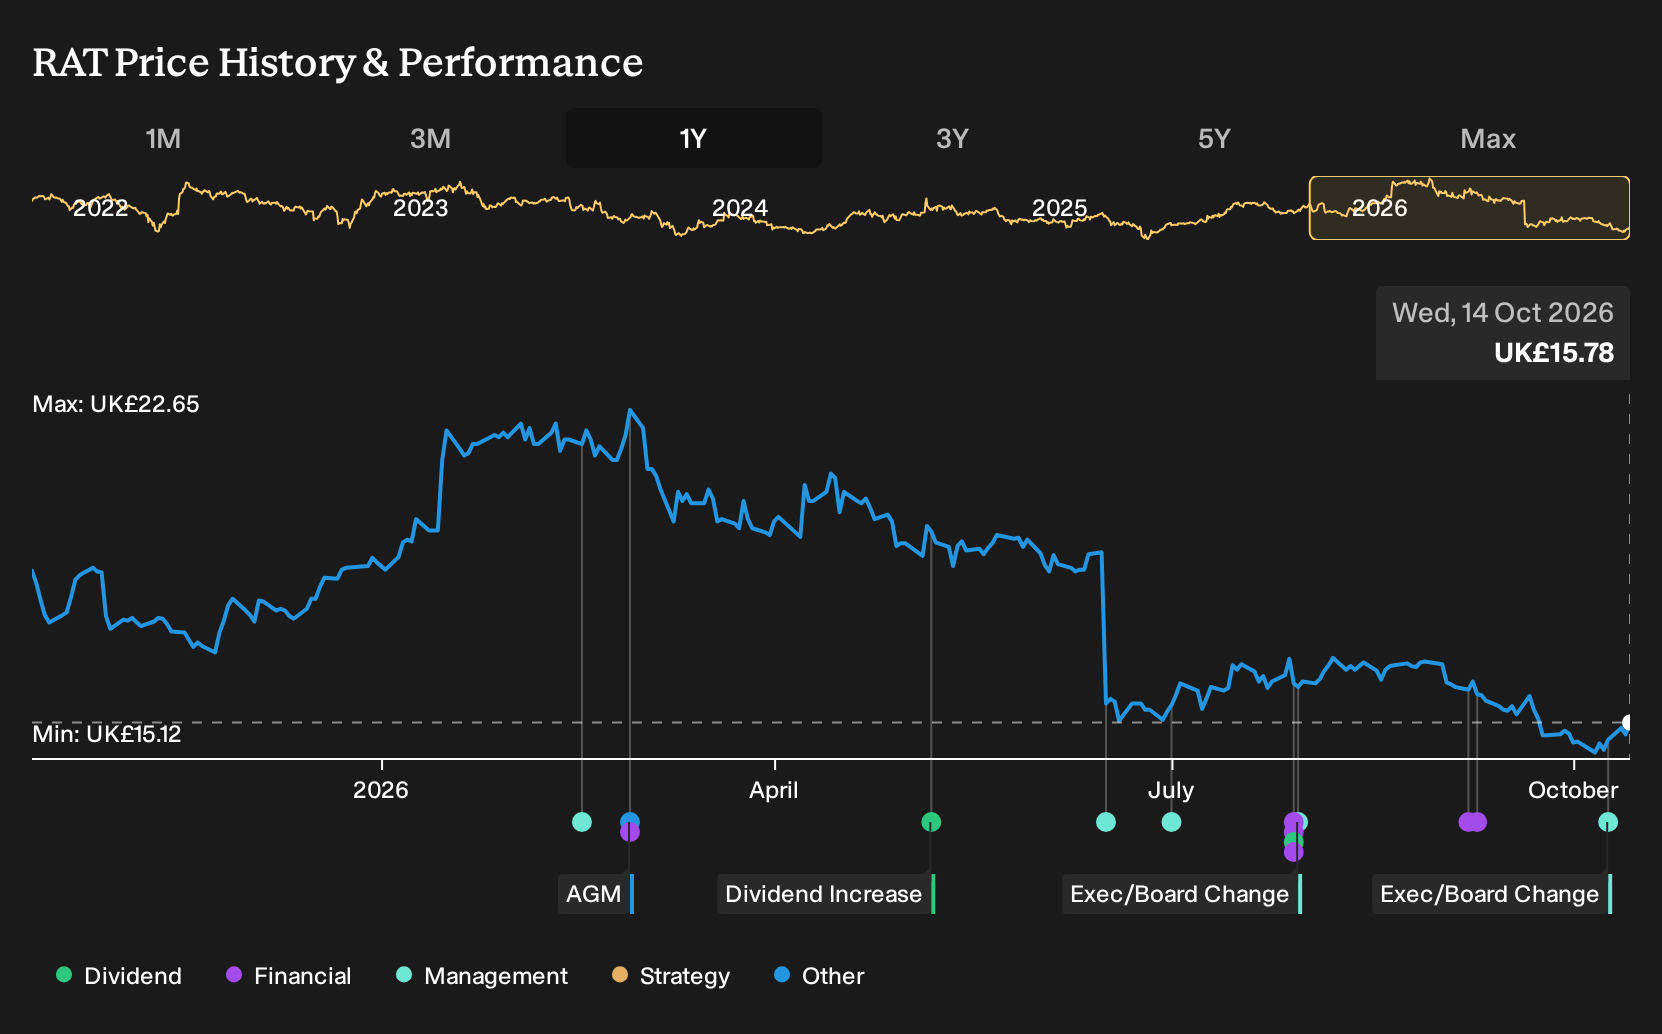
Exploring Other Perspectives
One alternate view puts technology execution risk at the centre of the Rathbones Group story. The most pessimistic analysts, working off pre appointment data, were modelling revenue drifting to about £859.7 million and earnings near £142.3 million by 2029. That is well below consensus and shows how far opinions can spread. Use this board change as a prompt to compare those scenarios yourself and decide which assumptions align most closely with your own expectations.
Explore 2 other Rathbones Group fair value estimates, including one that suggests as much as 14% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Rathbones Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Rathbones Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rathbones Group's overall financial health at a glance.
Looking for more Rathbones Group style ideas?
Once you have formed a view on Rathbones Group, it can help to pressure test that thinking against other listed wealth and asset managers that share similar balance sheet, income and risk profiles.
- For investors who want potential mispricing combined with quality fundamentals, review our hand picked set of 8 high quality undervalued stocks that may warrant a spot on your watchlist.
- If capital preservation and financial resilience matter most to you, focus on businesses screened for strong finances through our list of solid balance sheet and fundamentals (9 results).
- For those hunting for less crowded ideas with stronger underlying metrics, scan through the 5 high quality undiscovered gems to see which under followed stocks match your criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com