
What Early Mega Lifesciences Buyers Saw
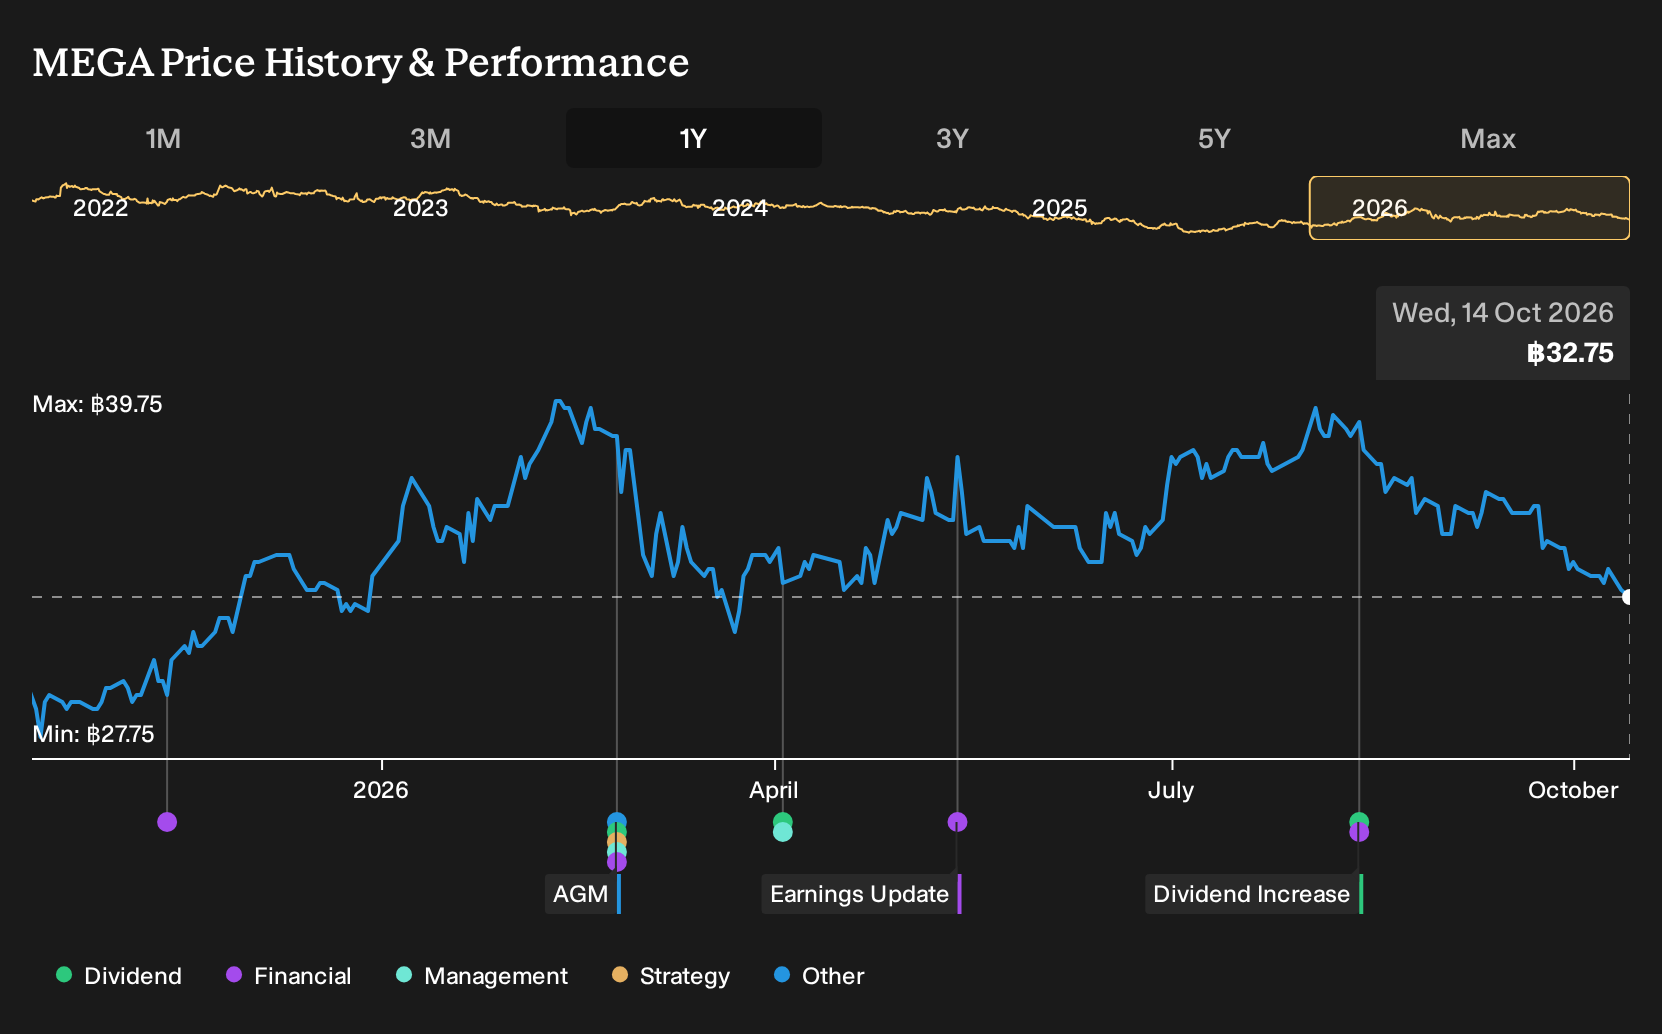
Q2 2026 put Mega Lifesciences back in focus as quarterly revenue reached THB 3,547.183 million and net income excluding extra items registered THB 514.611 million, with net margin at 14.5%. Investors who held Mega Lifesciences over the past year are up 23.6%, including dividends. If you were deciding on 14 October 2025, you had only the earlier analyst split and pre Q2 track record. What exactly had to be believed about this business at that time?
If the move has made Mega Lifesciences harder to judge, start where the gap is still open and scan 188 high quality undervalued stocks.
The Two Mega Lifesciences Stories Investors Were Choosing Between
The shares cost THB28.75 at the start of the period, and the live question was which story about Mega Lifesciences would prove closer to reality.
The bullish view saw a Fair Value of THB39, a price implied by assumptions that aging populations and emerging markets would support 6.8% annual revenue growth and a profit margin lift from 13.0% to 16.3% by 2028.
The bearish camp set Fair Value at THB26, based on expectations that revenue would decline 0.8% a year and that heavy exposure to Myanmar, Nigeria, and Africa would keep earnings volatile despite margin assumptions of 14.6%.
What The Mega Lifesciences Results Actually Tested
Q2 2026 results gave both camps fresh numbers to chew on. Revenue reached THB 3,547.183 million against THB 3,420.07 million in Q2 2025, and net income excluding extra items rose to THB 514.611 million from THB 390.918 million, with net margin moving from 11.4% to 14.5%. The evidence cut both ways but leaned toward the optimistic thesis on profitability.
The useful takeaway for any stock is simple. When a forecast hinges on margin expansion, you track net income and net margin first, not just sales trends, and judge whether that profitability story is actually turning up in the reported numbers.
What Mega Lifesciences Buyers Are Paying For Now
Mega Lifesciences now trades at THB32.75, and this selected Narrative places its Fair Value above that level. The argument focuses on new manufacturing projects and branded-product economics rather than simply repeating the earlier split between bullish and bearish views.
The Narrative centres on capital expenditure execution, cash conversion and the branded portfolio doing the heavy lifting. A buyer today would need to judge whether Mega Lifesciences can deliver its planned capacity build while keeping SG&A around one third of sales and turning earnings into cash.
"The main thing that has to go right is that the company executes its THB 2.6 to 2.7b capex plan while maintaining disciplined SG&A at about 32 to 33% of sales and sustaining low double digit growth in its branded business across Southeast Asia, Africa and Latin America."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Go Straight To The Source
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 49% below our estimate - focuses on mission critical data center and semiconductor infrastructure projects with multi year backlogs.
- Company 2 - 50% below our estimate - shifts toward long duration public programs and higher margin technical and energy service contracts.
- Company 3 - 24% below our estimate - leans on U.S. boutique rollout and new digital channels to deepen fashion customer engagement.
Those are three of them. See every one of the 202 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com