
How Montréal Studio Opening At Hasbro (HAS) Has Changed Its Investment Story
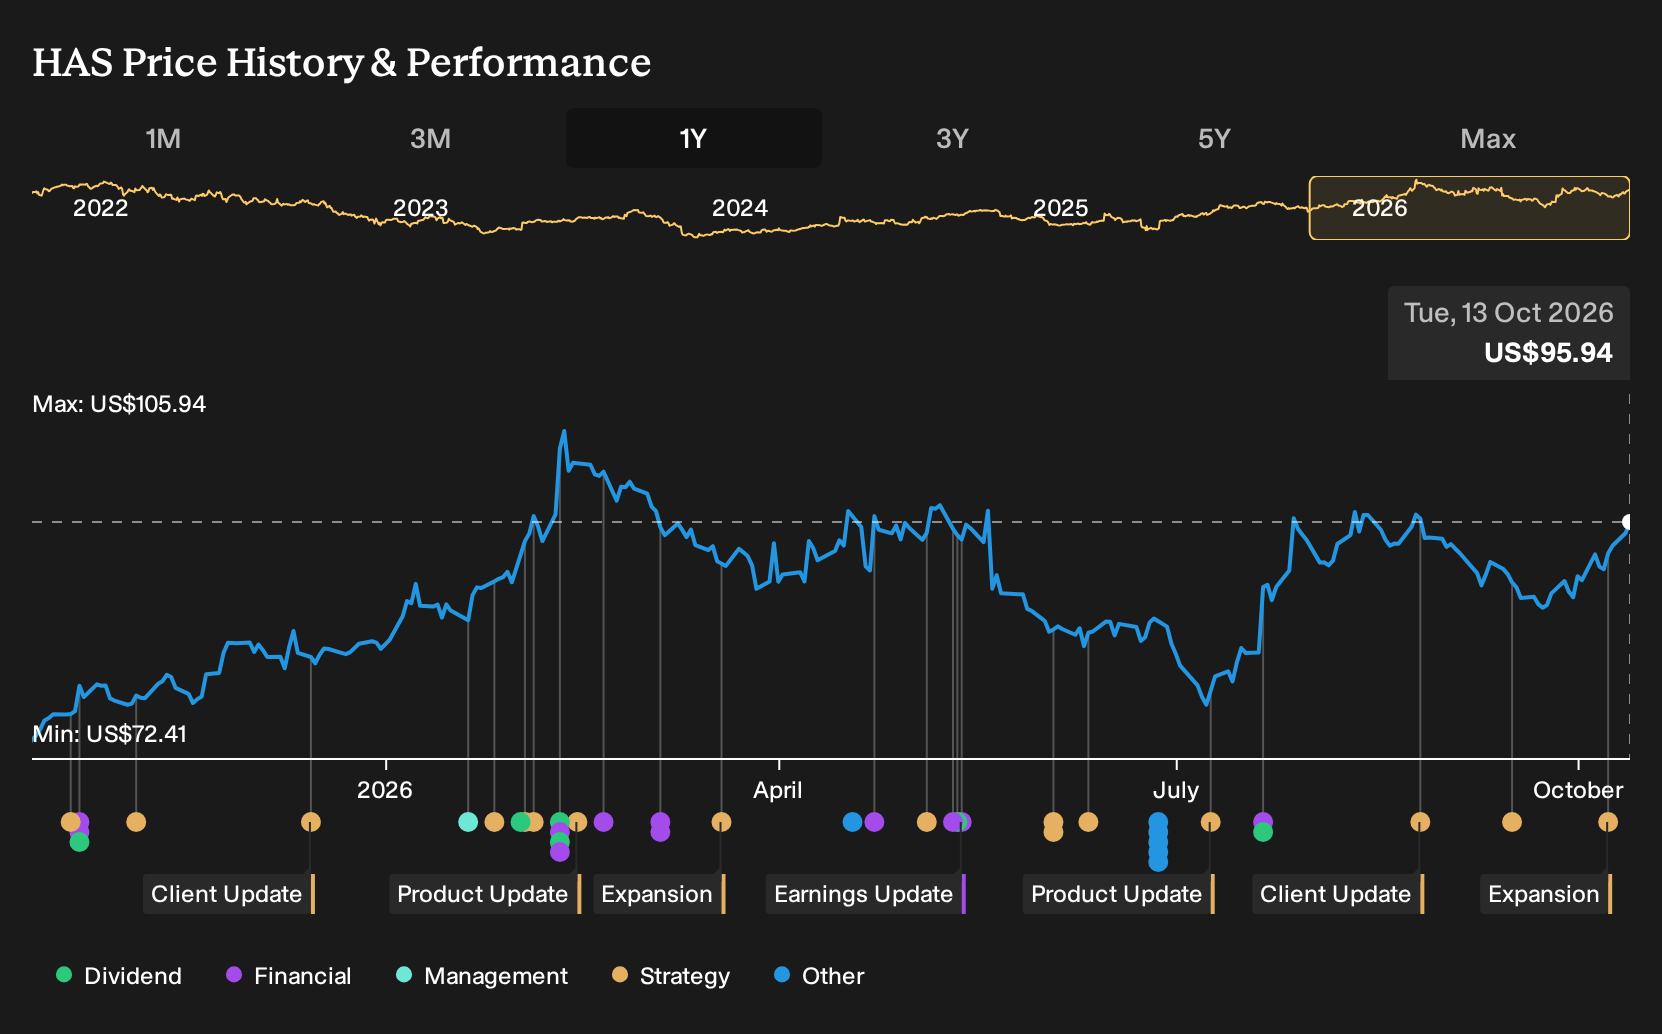
- Hasbro and Bib & Tucker Bourbon released MONOPOLY: Bib & Tucker Collector's Edition on October 14, 2026, a limited-run, adult-focused board game that merges Tennessee whiskey themes with classic Monopoly gameplay and targets holiday gifting price points.
- Alongside this collector product, Hasbro opened Wizards of the Coast Studios in Montréal to build Dungeons & Dragons content and digital games, signalling continued investment in owned IP and higher-margin digital experiences.
- This article examines how Hasbro's investment narrative is shaped by the Montréal Dungeons & Dragons studio opening and the adult-focused Monopoly collaboration.
Scan for other brands trying to turn fandom into higher-margin experiences and compare Hasbro with a hand picked group of 20 high quality undiscovered gems in the consumer and entertainment space.
Hasbro Investment Narrative Recap
To own Hasbro, you need to believe the shift toward higher margin digital and IP driven experiences can offset a softer, more uneven traditional toy cycle and high reliance on a few franchises. The key near term swing factor is whether Wizards of the Coast and digital titles keep carrying earnings while Consumer Products faces retailer caution and tariff pressure.
The biggest risk still sits in concentration around brands like Magic and Dungeons & Dragons plus a balance sheet that carries meaningful debt. The Bib & Tucker Monopoly tie in is directionally consistent with adult collectors and gifting, but appears immaterial to near term earnings or to the core risk profile.
The Montréal Wizards of the Coast studio opening is the announcement to watch. It directly relates to Hasbro's push into digital Dungeons & Dragons content, a segment that has been framed as a key driver of higher margin, recurring income. The move expands the footprint in a major gaming hub and adds capacity to support existing Wizards and MONOPOLY GO! momentum.
Execution risk rises with any large content hub, especially when analysts already focus on digital expansion as a central catalyst. Cost control, hiring pace, and quality of shipped titles will determine whether this studio supports the profit growth analysts have forecast at roughly 7% a year or instead weighs on margins if projects run long or underperform.
Hasbro's narrative projects US$5.5b revenue and US$1.0b earnings by 2029. This assumes 4.7% yearly revenue growth and a move from a loss of US$222.6m today to US$1.0b earnings, representing an earnings increase of roughly US$1.2b.
Uncover why Hasbro's fair value indicates a 15% potential upside to its current price, which could narrow quickly if Hasbro executes on its IP plans.
Exploring Other Perspectives
The Simply Wall St Community currently contributes 2 fair value estimates for Hasbro, stretching from about US$109.93 to US$159.66, which shows just how far apart private investors can be. Before the Montréal studio opening and adult Monopoly push, these views already hinged on franchise concentration risks and digital execution. Use that spread as a prompt to explore several alternative viewpoints.
Explore another Hasbro fair value estimate, including one that suggests as much as 67% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Hasbro research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Hasbro. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hasbro's overall financial health at a glance.
Looking For More Hasbro-Like Investment Ideas?
If the Hasbro story has you thinking about where else durable brands and solid balance sheets might show up, the Simply Wall St Screener can help you scan the wider market with the same discipline.
- If you care most about resilience and capital protection, start with a set of companies that score well on financial strength through our 32 resilient stocks with low risk scores.
- For investors focused on sturdier finances and less stretched balance sheets, the list of solid balance sheet and fundamentals (25 results) can surface businesses with the kind of foundation that supports long term plans.
- If you want ideas that are off most radars but still backed by solid fundamentals, use the 20 high quality undiscovered gems to look beyond widely followed large caps.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com