
Should Mexico Leadership Shift Require Action From Woodside Energy Group (ASX:WDS) Investors?
- Woodside Energy Group recently expanded Stephane Drouaud’s remit as he relocates to Mexico City to become Managing Director for Mexico while remaining Vice President of the Trion Project. This move aligns leadership with centralised project execution as drilling and subsea installation work progresses.
- The combination of on the ground leadership for Trion and a Memorandum of Understanding with PEMEX signals Woodside Energy’s intent to build a longer term operational and technical footprint in Mexico’s hydrocarbon sector.
- We will now explore how Woodside Energy's investment narrative could shift as execution of Trion concentrates under new Mexico based leadership.
Scan how Woodside Energy Group’s Mexico push compares with other energy producers ramping up project pipelines by checking our hand picked list of solid balance sheet and fundamentals (12 results).
Woodside Energy Group Investment Narrative Recap
To own Woodside Energy Group you need to be comfortable with a large scale LNG and oil producer that leans heavily on big projects like Scarborough, Pluto Train 2, Louisiana LNG and Trion. The near term story is about executing those developments cleanly while keeping operating costs and capex from crowding out flexibility elsewhere.
The Mexico leadership move looks operational rather than thesis changing. It concentrates accountability for Trion closer to the field, which may help keep timelines and budgets on track. The bigger near term risk still sits with project delivery, regulatory shifts and carbon costs, along with a dividend that is not well covered by free cash flow.
The Trion focused announcement links directly to one of Woodside Energy Group’s key future production drivers. By putting the Trion Vice President in Mexico City as Managing Director, the business is tying country presence to a specific project that already has drilling and subsea installation underway, which points to an execution heavy phase for this asset.
For catalysts, investors are watching whether Trion, alongside Scarborough and Louisiana LNG, can come online without meaningful schedule or budget pressure. Trion progress also interacts with expectations for earnings, which consensus currently sees as drifting slightly lower over the next few years, and with how much room Woodside has to keep funding a dividend that is not fully covered by free cash flows.
Woodside Energy Group’s current analyst storyline points to revenues of $16.1 billion and earnings of $3.1 billion by 2029, based on assumed yearly top line growth of 5.2% and earnings holding flat at $3.1 billion, which implies no change from earnings today.
Uncover why Woodside Energy Group's fair value indicates a 4% potential upside to its current price that may not last much longer.
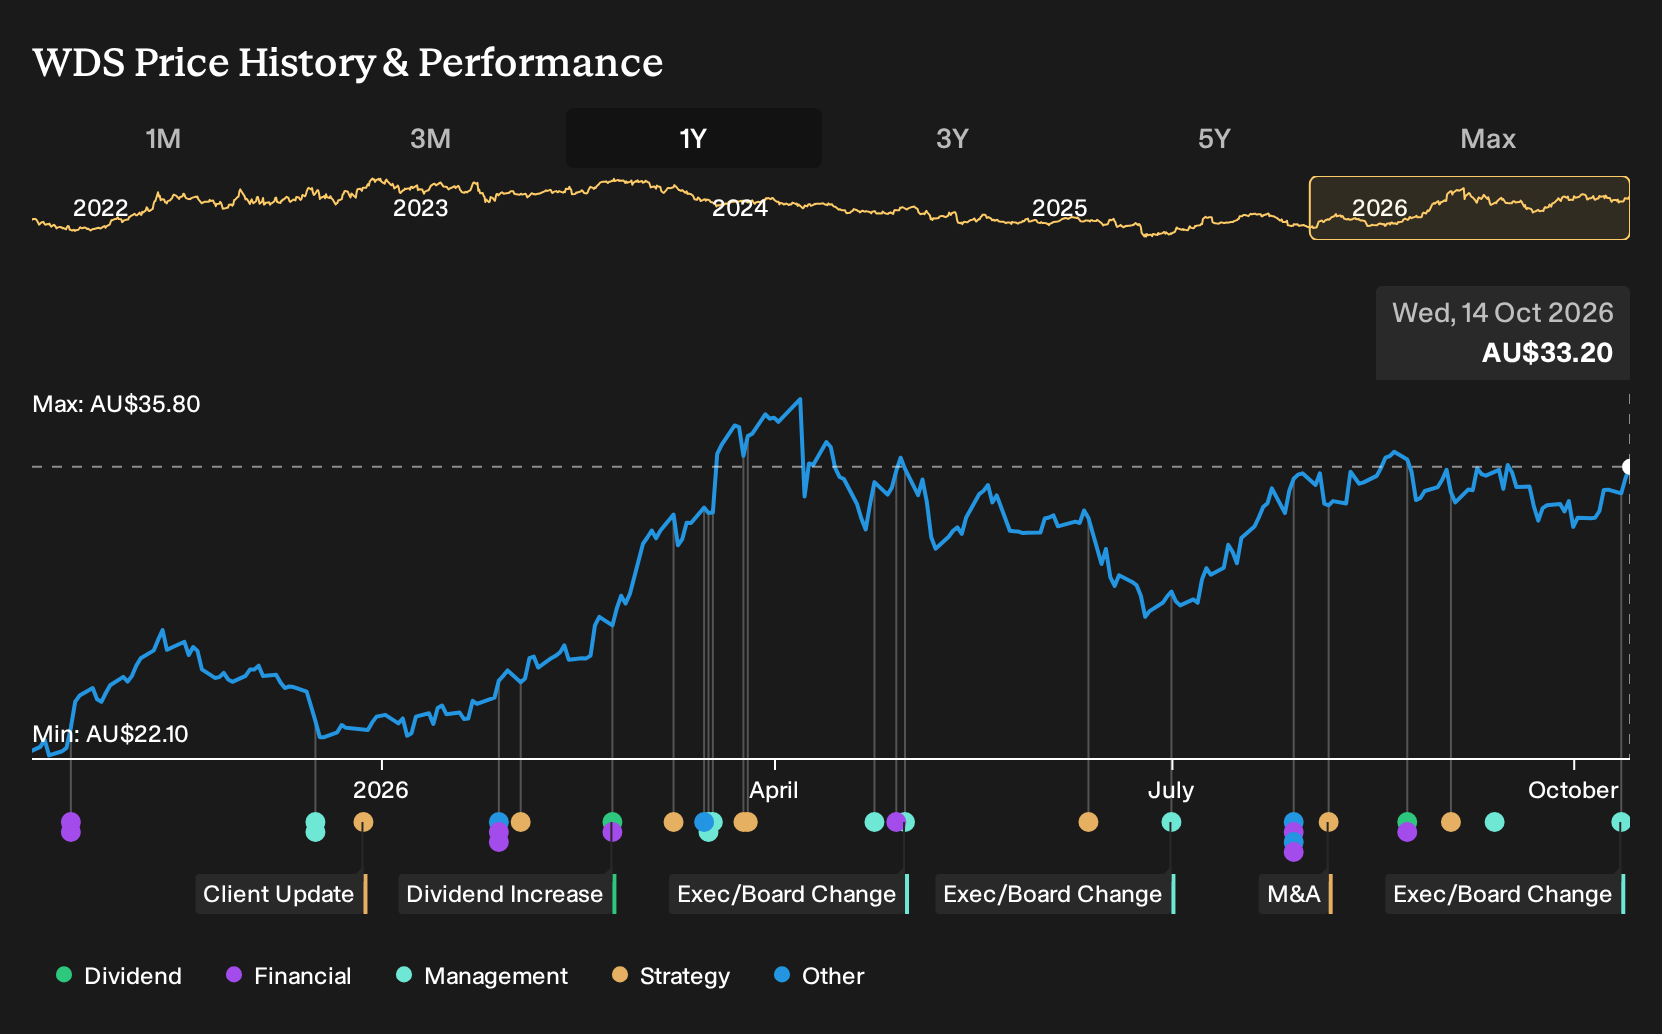
Exploring Other Perspectives
You have a very different story if you focus on the risk that Trion and other LNG projects struggle to earn back their upfront spend. The most bearish analysts were only pencilling in about $13.4b of revenue and $2.2b of earnings by 2029 before this Mexico leadership shift, so views clearly diverge. Consider using this move as a trigger to explore those alternative forecasts for Woodside Energy Group.
Explore 6 other Woodside Energy Group fair value estimates, including one that suggests as much as 22% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own research and judgment.
- A great starting point for your Woodside Energy Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Woodside Energy Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Woodside Energy Group's overall financial health at a glance.
Looking for more investment ideas beyond Woodside Energy Group?
If the Woodside Energy Group story has highlighted how much project mix and balance sheet strength can shape your returns, it can be useful to compare it with other companies that have very different profiles. Use the Simply Wall St Screener to scan broader opportunities and assess whether Trion heavy exposure is really the right fit for your portfolio.
- If you want potential mispricing on your side, check out companies that screen as 4 high quality undervalued stocks with solid fundamentals backing them.
- For income focused investors, map out options that look built for regular payouts by reviewing our set of 3 dividend fortresses.
- When capital preservation matters most, narrow your watchlist to businesses that qualify as 6 resilient stocks with low risk scores based on their financial resilience and risk profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com