
Solar Pipeline Might Change The Case For Investing In Southern Stock (SO)
- Southern Company is drawing attention for its large utility scale solar position, with more than 17 GW of contracted large load agreements into the mid 2030s, an 8 GW late stage pipeline, and a prospective funnel above 75 GW integrated into its regulated electric and gas operations.
- Investors are also focusing on Southern's 25 year streak of annual dividend increases and upcoming November 5, 2026 earnings release, as current projections point to higher EPS and revenue alongside a premium P/E multiple relative to peers.
- Attention is now turning to how Southern's long term solar pipeline and dividend consistency could reshape the investment narrative for this regulated utility.
Scan beyond Southern to see how other regulated utilities and grid players are positioning for large scale renewables with our hand picked 43 power grid technology and infrastructure stocks
What Is Southern's Investment Narrative?
To own Southern, you need to be comfortable with a regulated utility that leans into very long term projects. The core story is still about steady electric and gas operations in the Southeast, layered with a large utility scale solar buildout that is capital heavy but backed by long duration contracts. Recent attention on the earnings release scheduled for November 5, 2026, and on premium P/E pricing, mainly reinforces that near term sentiment is tied to execution on this growth plan rather than a sudden shift in the business model.
Short term, the bigger swing factors are whether Southern can keep large load demand tied up in contracts at acceptable pricing, control project costs across its 8 GW late stage solar pipeline, and support the 25 year dividend increase streak with earnings rather than balance sheet stretch. Interest coverage and free cash flow coverage of the roughly 3.5% yield are watchpoints, especially with a market value above US$100b and a stock that has lagged the broader US market over the past year.
That said, there is a quieter pressure point in Southern's story that could matter far more than the next earnings print...
There's only one way to know the right time to buy, sell or hold Southern. Head to Simply Wall St's company report for the latest analysis of Southern's Fair Value.
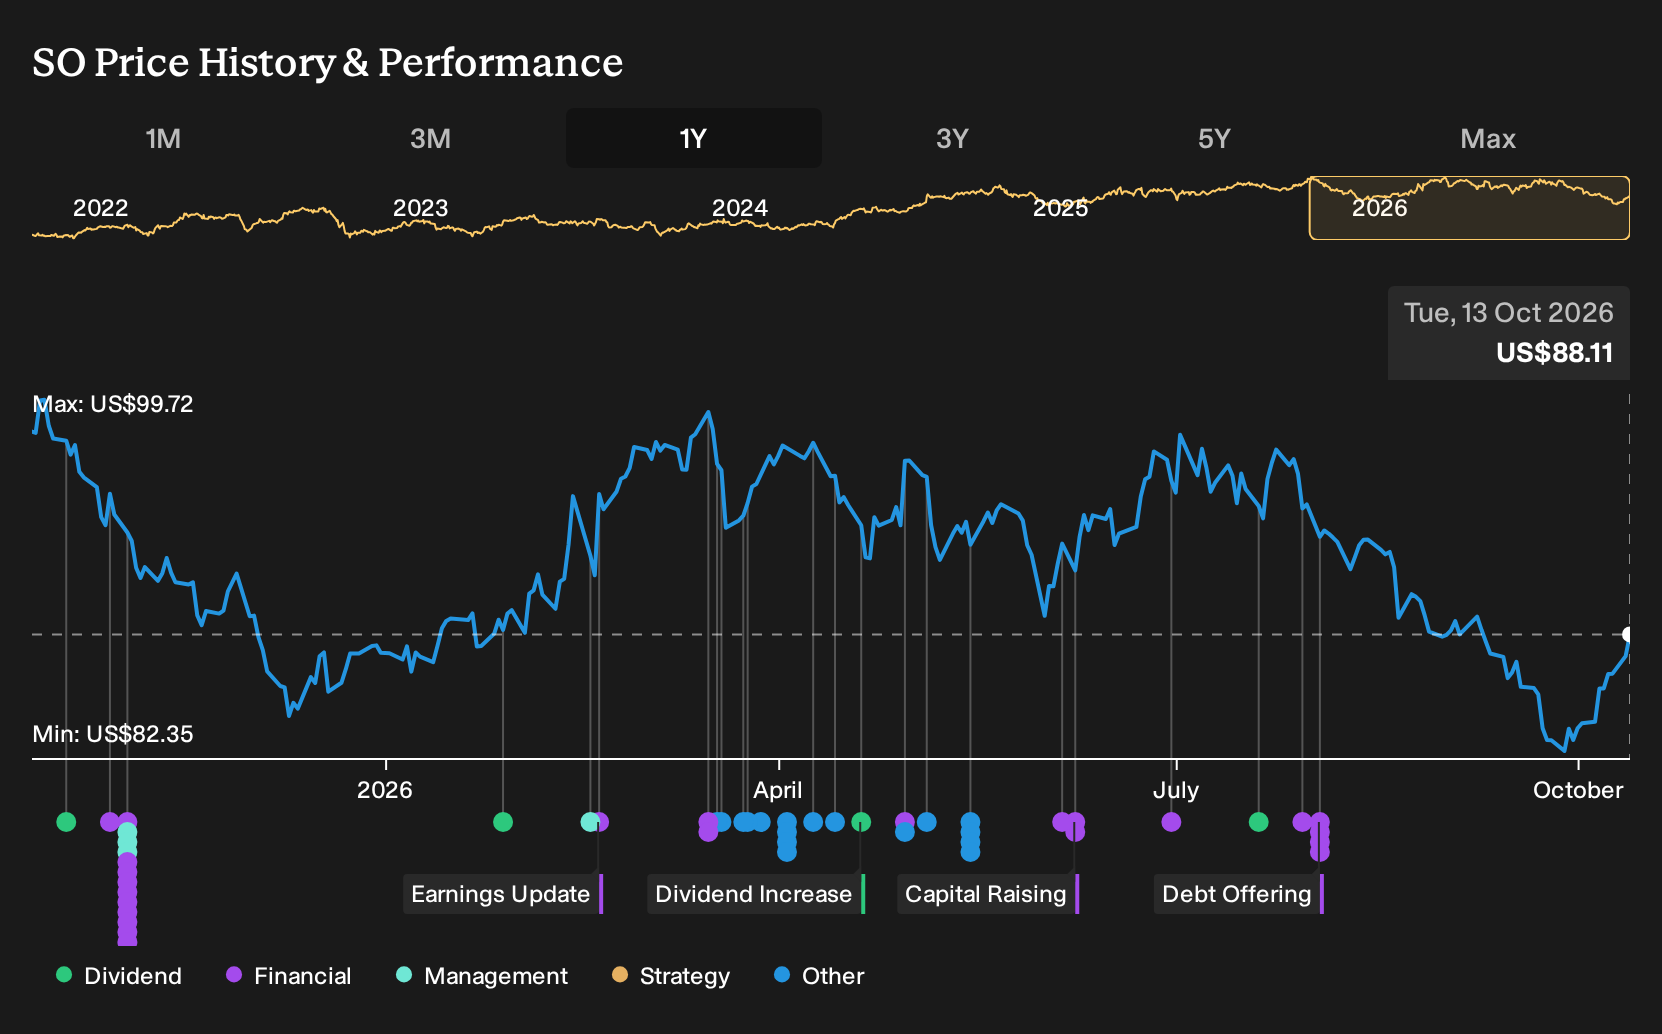
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$4 to US$97 per share, so retail opinions on Southern Company could not be further apart. You are weighing that spread against a premium P/E, a 25 year dividend streak, and a large solar pipeline, each of which could pull sentiment in different directions. Explore the full set of views to see where you sit in that spectrum.
Explore 2 other Southern fair value estimates, including one that suggests there could be as much as 96% downside from the current price.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Southern research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Southern. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Southern's overall financial health at a glance.
Looking For More Investment Ideas Beyond Southern?
Once the Southern story is clear in your mind, broaden your watchlist using the Simply Wall St Screener to find other stocks that fit the kind of profile you prefer, whether that means income resilience, valuation support, or future potential.
- If you want income to do more of the heavy lifting, scan for higher yielding payers that still look robust with our 8 dividend fortresses.
- When valuation discipline matters most, focus on companies that blend quality fundamentals with pricing that does not look stretched using the 32 high quality undervalued stocks.
- If resilience and balance sheet strength sit at the top of your checklist, narrow the field to businesses with sturdier financial footing through the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com