
Will Earnings Beat Change Victoria's Secret's (VSXY) Narrative
- Victoria's Secret & Co. announced that Chief Legal and Compliance Officer Melinda McAfee will depart after March 31, 2027, and has begun searching for her successor while reporting second quarter adjusted earnings per share and revenue that were above consensus estimates.
- The combination of a planned legal leadership transition and stronger than expected quarterly performance highlights how Victoria's Secret is balancing governance continuity with current operating momentum in its core retail business and supporting functions.
- We will now look at how Victoria's Secret investment narrative could be affected by the legal leadership transition alongside the earnings beat.
Scan how investors are rewarding execution in retail by comparing Victoria's Secret with list of solid balance sheet and fundamentals (25 results) that are also trying to turn operational traction into sustained market confidence.
Victoria's Secret Investment Narrative Recap
To hold Victoria's Secret shares, investors need to believe that the shift toward higher quality merchandising, fewer discounts and a stronger omnichannel setup can keep customers engaged without eroding traffic. The latest quarter, with adjusted EPS and revenue above expectations, supports that operating story. The key near term catalyst remains execution through upcoming seasonal periods and whether regular price selling holds.
The main risk remains a return to the older pattern of low single digit revenue growth, mid single digit margins and weaker EPS, especially with tariffs and higher debt costs in the background. The planned legal leadership change appears manageable and, on its own, does not materially alter the near term commercial outlook.
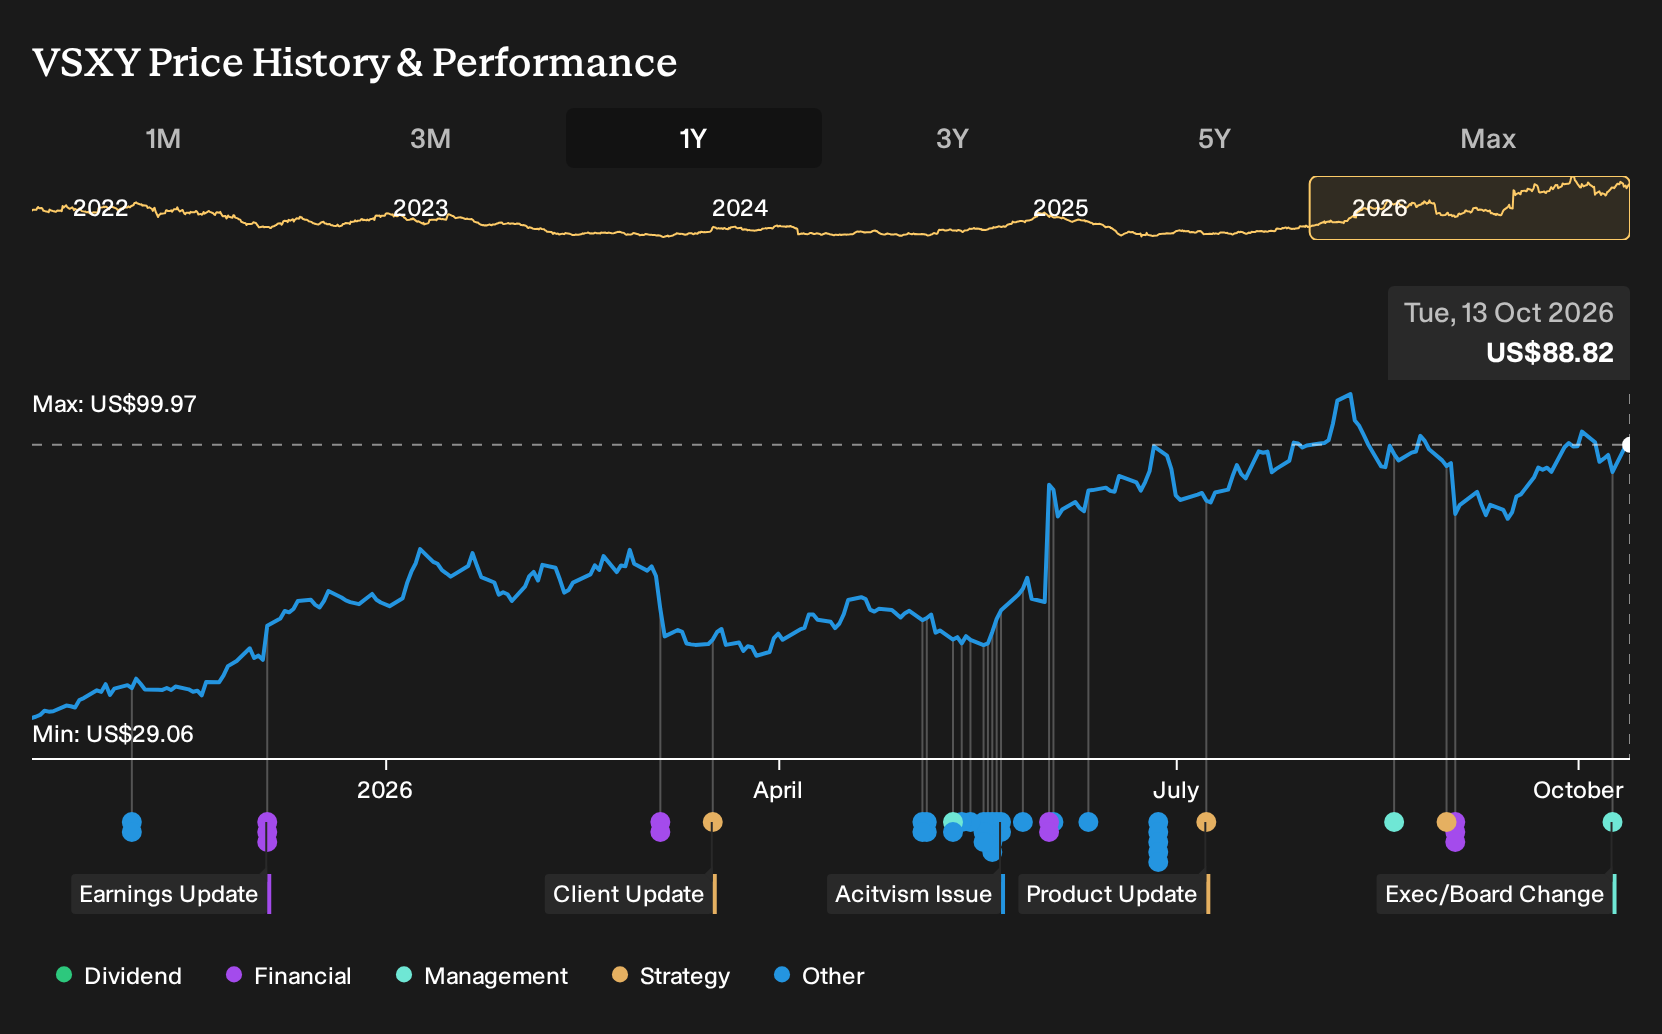
The most relevant announcement here is the 7.11% move in Victoria's Secret stock after the legal chief's planned exit alongside an earnings beat. That reaction suggests investors are currently more focused on operating trends than on a staged governance transition, with the backdrop of reported revenue growth of 5.3% and earnings growth of 10.9% annually.
For investors, the practical watchpoints are clear. Track who steps into the Chief Legal and Compliance Officer role and whether any change in risk oversight affects tariff mitigation, sourcing or international expansion. Combine that with close attention to holiday performance in bras, beauty and digital, because any slowdown relative to recent momentum could quickly bring valuation and past share price gains back into focus.
Victoria's Secret's current analyst narrative points to revenues of US$8.1b and earnings of US$536.9m by 2029, built on 5.6% yearly revenue growth and an earnings increase of about US$158.9m from the US$378.0m reported today.
Uncover why Victoria's Secret's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts see the legal leadership change as a potential catalyst rather than a risk. They were already pencilling in about US$8.3b of revenue and US$508.6m of earnings by 2029, with a US$110.0 price target. You can compare those pre‑news assumptions with your own view and decide where you sit.
Explore 2 other Victoria's Secret fair value estimates, including one that suggests it could be worth as much as $92.45.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Victoria's Secret research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Victoria's Secret. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Victoria's Secret's overall financial health at a glance.
Looking For More Investment Ideas Beyond Victoria's Secret?
Once you have a view on Victoria's Secret, it can help to benchmark that thesis against other opportunities on the market using the Simply Wall St Screener. That way you keep your watchlist fresh and grounded in data rather than headlines.
- If income stability matters most to you, scan for companies that aim to combine yield with resilience through the 8 dividend fortresses.
- For investors who care most about financial strength, search for businesses with cleaner balance sheets and sturdier fundamentals using the list of solid balance sheet and fundamentals (25 results).
- If you want ideas that the broader market may be overlooking, widen your research with the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com