
3 Japanese Growth Stocks With Earnings Growth Over 23%
US inflation has stayed high for years, keeping interest rates in focus and rewarding businesses that can grow without leaning heavily on cheap debt. That backdrop makes fast growing Japanese companies with managers who own meaningful stakes especially interesting, because leadership feels more of the upside and the downside. This article highlights three stocks from that group, explaining how their growth profiles and insider ownership might appeal to long term investors.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders share more of the upside and the downside with you. However, if you want the names that matter most, these 28 high growth high conviction stocks are the strongest companies we've found.
Sansan (TSE:4443)
Overview: Sansan is a Tokyo based SaaS provider that digitises business cards and contracts so companies can centralise contacts and streamline workflows.
Operations: Sansan generated about ¥48.9b from its Sansan and Bill One unit, ¥7.1b from the Eight segment, and almost all ¥56.2b revenue in Japan.
Market Cap: ¥241.3b
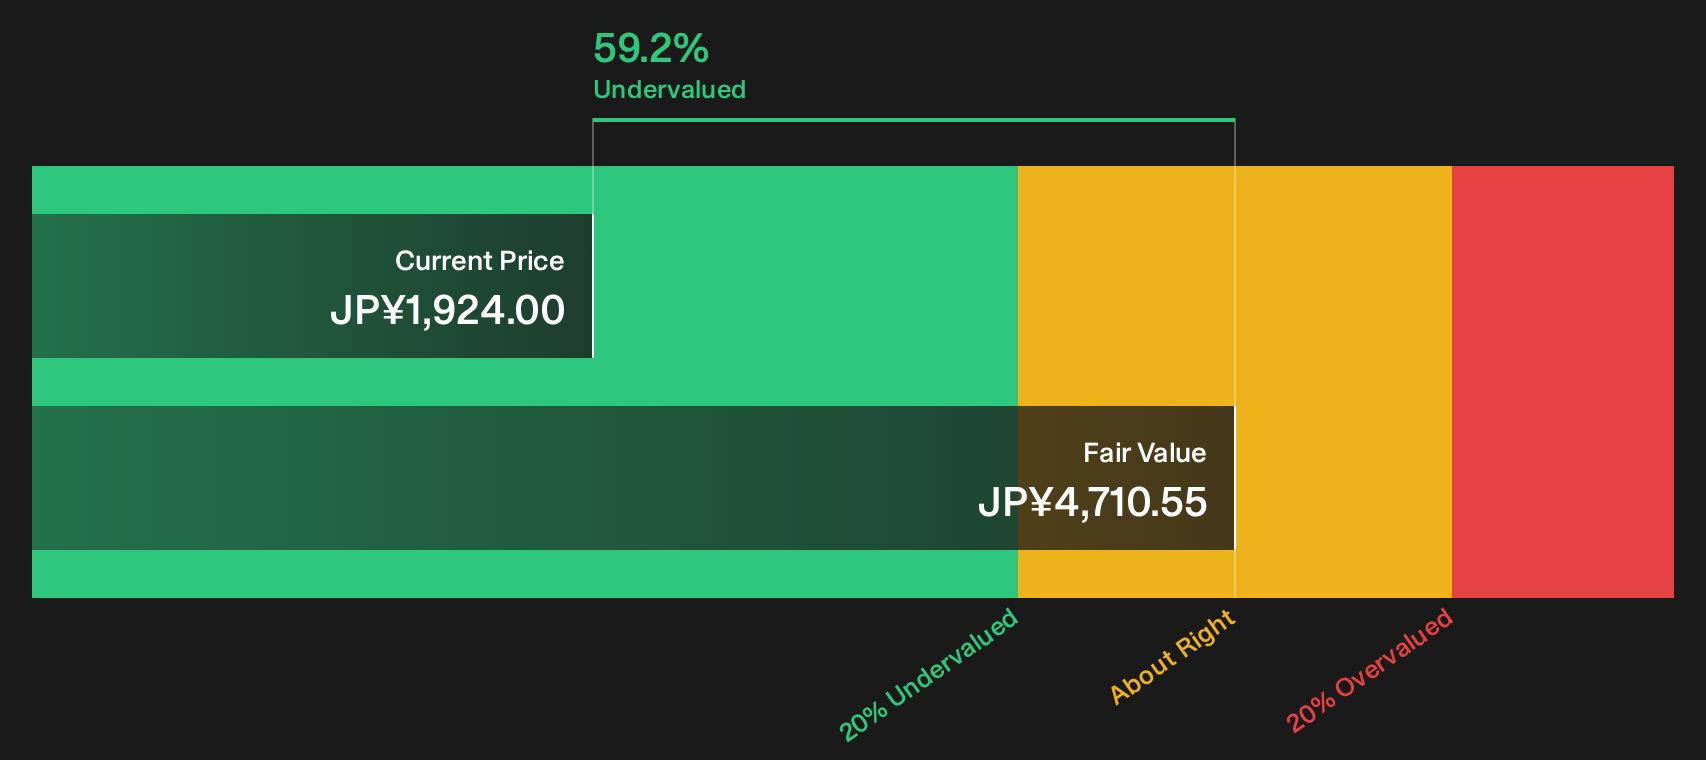
Sansan fits this screener because its core cloud contact platform and related tools support strong projected earnings growth and high forecast ROE. The stock trades well below one estimate of fair value, so the real test is what happens if a single key assumption about SaaS demand and pricing power breaks.
If that assumption feels like the real swing factor for Sansan, start with the 3 key rewards and 1 important warning sign to see what the market might be missing.
Micronics Japan (TSE:6871)
Overview: Micronics Japan makes semiconductor probe cards and testing gear for advanced chip fabrication, alongside body measuring and display inspection equipment.
Operations: Micronics Japan generates about ¥84.9b from its Probe Card Business and ¥1.4b from TE Business across Japan, South Korea, Taiwan and other regions.
Market Cap: ¥582.7b
Micronics Japan ties directly into the screener theme through its probe card and semiconductor test equipment line. Earnings grew 89.4% last year and forecasts point to about 24.88% yearly earnings expansion. Management is ramping production to meet memory semiconductor demand, so the real story depends on what happens if that demand curve starts to bend.
If that demand bend worries you, take a closer look at how Micronics Japan compares with that scenario in the 2 key rewards and 1 important major warning sign before sentiment starts to shift.

Kasumigaseki CapitalLtd (TSE:3498)
Overview: Kasumigaseki CapitalLtd is a Tokyo based real estate consultant that also develops solar power projects, logistics facilities and apartment hotels.
Operations: Kasumigaseki CapitalLtd generated ¥163.8b in Japan, entirely from its Real Estate Consulting Business that includes solar project development.
Market Cap: ¥186.2b
Kasumigaseki CapitalLtd is linked to the fast growing, high insider ownership theme through its solar power project pipeline, supported by rapid earnings and revenue expansion, an 11.2x P/E below peers and positive analyst expectations. All of these factors depend on how pressure on funding and cash flow influences the outcome of that growth strategy.
That funding pressure is the crux, so start with the Kasumigaseki CapitalLtd financial health report to see whether Kasumigaseki CapitalLtd’s growth plan and balance sheet are really pulling apart.

Curious About The Next Set Of Alternatives
Fresh ideas often move first. Breakout stories can gain momentum while they are still under the radar. Consider taking time to review opportunities before the crowd shifts its focus.
- Hunt for income workhorses using the 28 dividend fortresses and gauge which businesses might keep cash returns flowing while the yield window still matters.
- Track developments in automation by scanning the 90 robotics and automation stocks and see which operators could support long term productivity before attention increases.
- Target resilient balance sheets through the list of solid balance sheet and fundamentals (21 results) and focus on companies that may hold up when weaker peers start to struggle.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com