
How Investors May Respond To GEO Group (GEO) Debt Cleanup And Buybacks
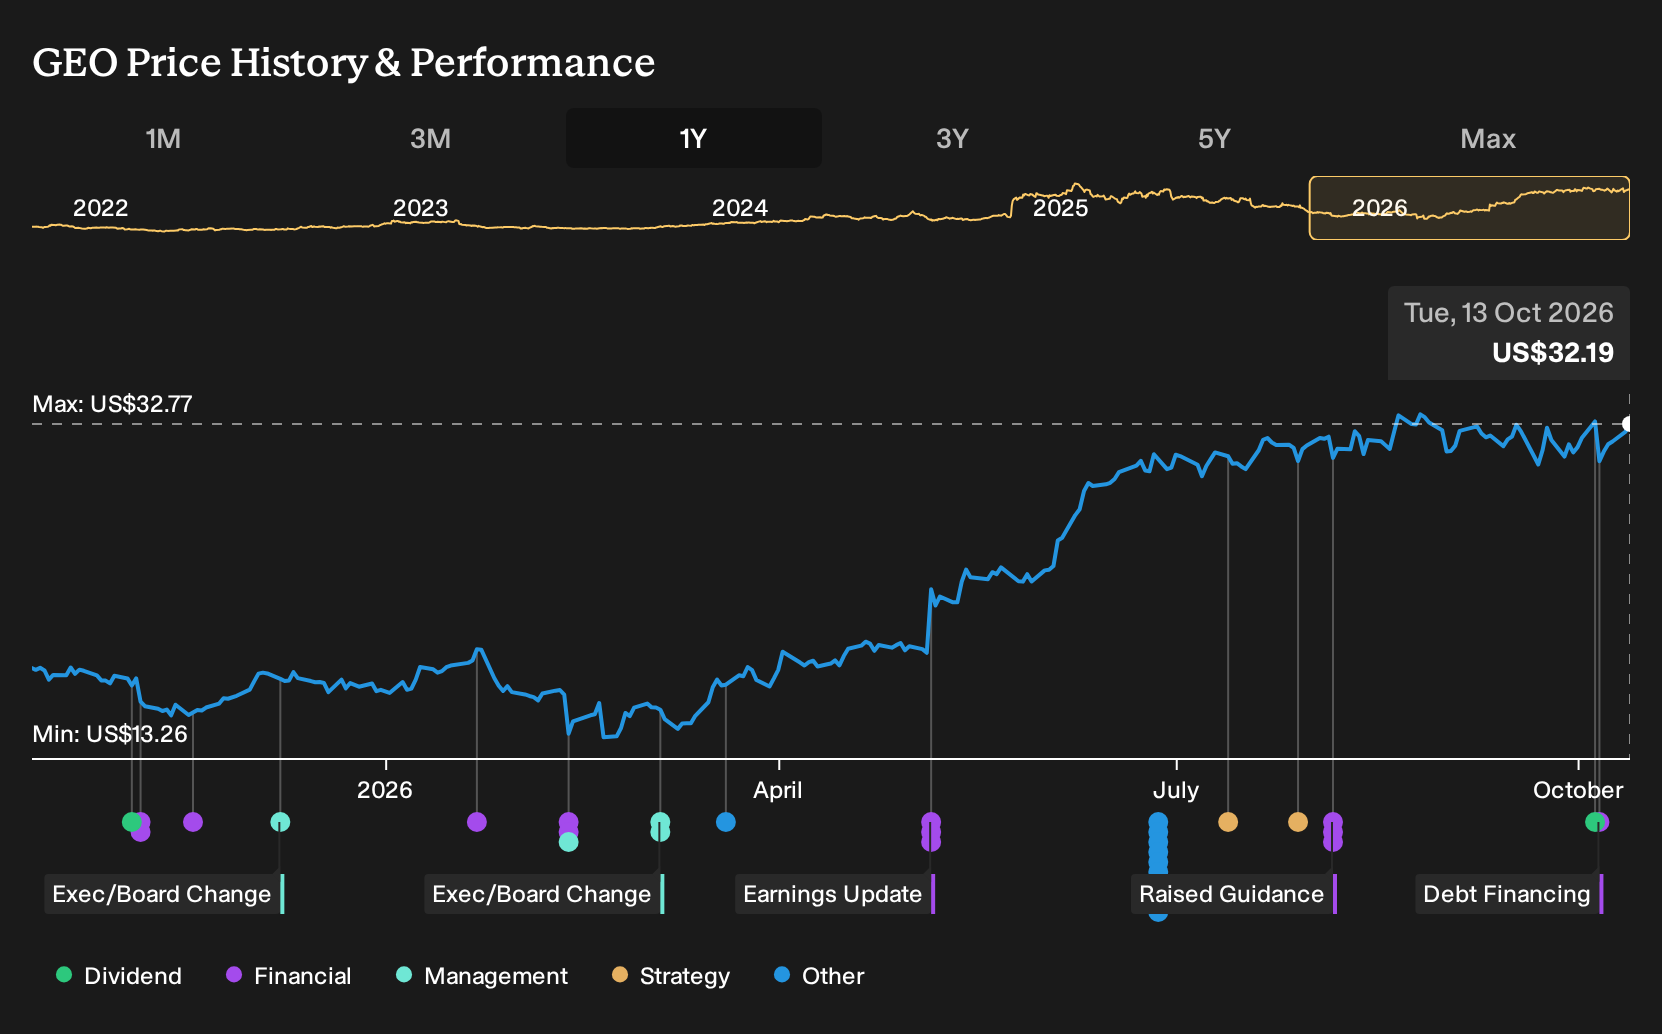
- GEO Group has already redeemed all US$650,000,000 of its 8.625% Senior Secured Notes due 2029 at about US$1,043.13 per US$1,000 of principal, funded by recent asset sales, and extended its US$550,000,000 revolving credit facility maturity to July 14, 2031 with expanded restricted payment capacity.
- The decision to clear these secured notes and expand a US$1.25 billion share repurchase authorization reshapes GEO Group’s capital structure and could influence how future cash flow is allocated between debt reduction and buybacks.
- Attention now turns to how GEO Group's investment narrative aligns with this large debt redemption and expanded share repurchase flexibility.
Scan how GEO Group’s debt cleanup and larger share repurchase plan compares with other companies reshaping their balance sheets by focusing on list of solid balance sheet and fundamentals (25 results).
GEO Group Investment Narrative Recap
To own GEO Group, you need to believe that federal detention and monitoring contracts remain active enough for the firm to keep filling beds, ramping ISAP participants, and reactivating idle facilities. The recent move to clean up higher cost secured debt does not alter the core operating swing factor, which is how ICE funding and policy choices translate into actual utilization.
The biggest near term swing factor still sits with the pace of ICE capacity build out and the activation of Big Horn, Rivers, and other idle high security beds. Policy reversals, contract pauses such as the recent skip tracing lapse, or fresh regulatory issues remain the main operational risk, and the latest debt actions do not change that exposure in a material way.
The most relevant update is the redemption of GEO Group’s US$650,000,000 8.625% Senior Secured Notes due 2029 and the extension of its US$550,000,000 revolving credit facility. Retiring this secured debt with asset sale proceeds and pushing out the revolver maturity to 2031 tidies the liability side and can reshape future interest expense and liquidity headroom.
With the indenture discharged and leverage based restricted payment baskets defined, GEO Group now has clearer room to choose between debt paydown, share repurchases under the expanded US$1.25b authorization, and reinvestment. For catalysts tied to ICE bed growth and ISAP scale, that flexibility may help management fund contract driven capacity while still managing financial risk if earnings soften or programs slow.
GEO Group's narrative projects US$3.8b revenue and US$137.8m earnings by 2029, which implies revenue growth of 9.9% per year and an earnings decline of about US$153.7m from US$291.5m today.
Uncover why GEO Group's fair value indicates a 17% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some bearish analysts focus less on GEO Group’s debt cleanup and more on free cash flow pressure. They were already modeling 2029 revenue of about US$3.7b with earnings of roughly US$151.3m, compared with today’s US$291.5m. That is a much more cautious story. Use it as a prompt to compare several viewpoints before deciding your own.
Explore 3 other GEO Group fair value estimates, including one that suggests it could be worth just $37.75.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your GEO Group research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for GEO Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate GEO Group's overall financial health at a glance.
Looking for more investment ideas beyond GEO Group?
If GEO Group has sharpened your focus on balance sheets, cash generation, and policy risk, it can be useful to line those insights up against a wider watchlist. Use the Simply Wall St Screener to scan for other businesses that match the kind of risk and quality profile you want to research next.
- If you want potential upside with strict quality filters, start by reviewing 20 high quality undiscovered gems that already show solid fundamentals and room to gain a wider following.
- For investors who prefer resilience over drama, consider building a list from 32 resilient stocks with low risk scores that score well on financial strength and business stability.
- If reliable income is your focus, map out companies offering higher yields and stronger coverage by screening through 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com