
Kimbell Royalty Partners (KRP) Lifted Its Distribution, Is The Upside Still Cheap?
Kimbell Royalty Partners (KRP) put fresh numbers on the table in Q2 2026, reporting record financial and operational results and lifting its quarterly distribution by 15% after the Mesa Royalties acquisition.
The Kimbell Royalty Partners unit price has built steady momentum, with a 7.22% 90 day share price return and a 30.92% year to date share price return, contributing to a 79.65% five year total shareholder return that reflects how income and price gains have combined over time.
Scan beyond Kimbell Royalty Partners and see how other income focused energy plays stack up in our hand picked 8 dividend fortresses.
After that run and a richer distribution, Kimbell Royalty Partners now asks a different question of holders and new money: Does the current unit price still offer a clear skew in favour of buyers?
Most Popular Narrative: 18% Undervalued
Against the last close at $15.75, the most followed narrative points to a fair value of $19.20, which frames Kimbell Royalty Partners as materially mispriced and puts consolidation at the center of the story.
The size of the U.S. royalty market, estimated at around $800 to $850b, and the continued shift of assets from private to public ownership position Kimbell Royalty Partners to pursue additional deals that can expand its asset base and support long term cash flow growth.
Scaling the royalty portfolio while keeping cash G&A per BOE below guidance and using larger transactions such as the August 2026 drop down to further reduce unit costs creates operating leverage that can support higher net margins and distributable earnings over time.
See why 16 investors see Kimbell Royalty Partners as 18% undervalued.
Result: Fair Value of $19.20 (UNDERVALUED)
Still, two pressure points could flip that bullish Kimbell Royalty Partners narrative: weaker drilling and DUC conversions on its acreage, and richer pricing for competing royalty deals.
Find out about the key risks to this Kimbell Royalty Partners narrative.
Another View On Kimbell Royalty Partners Valuation
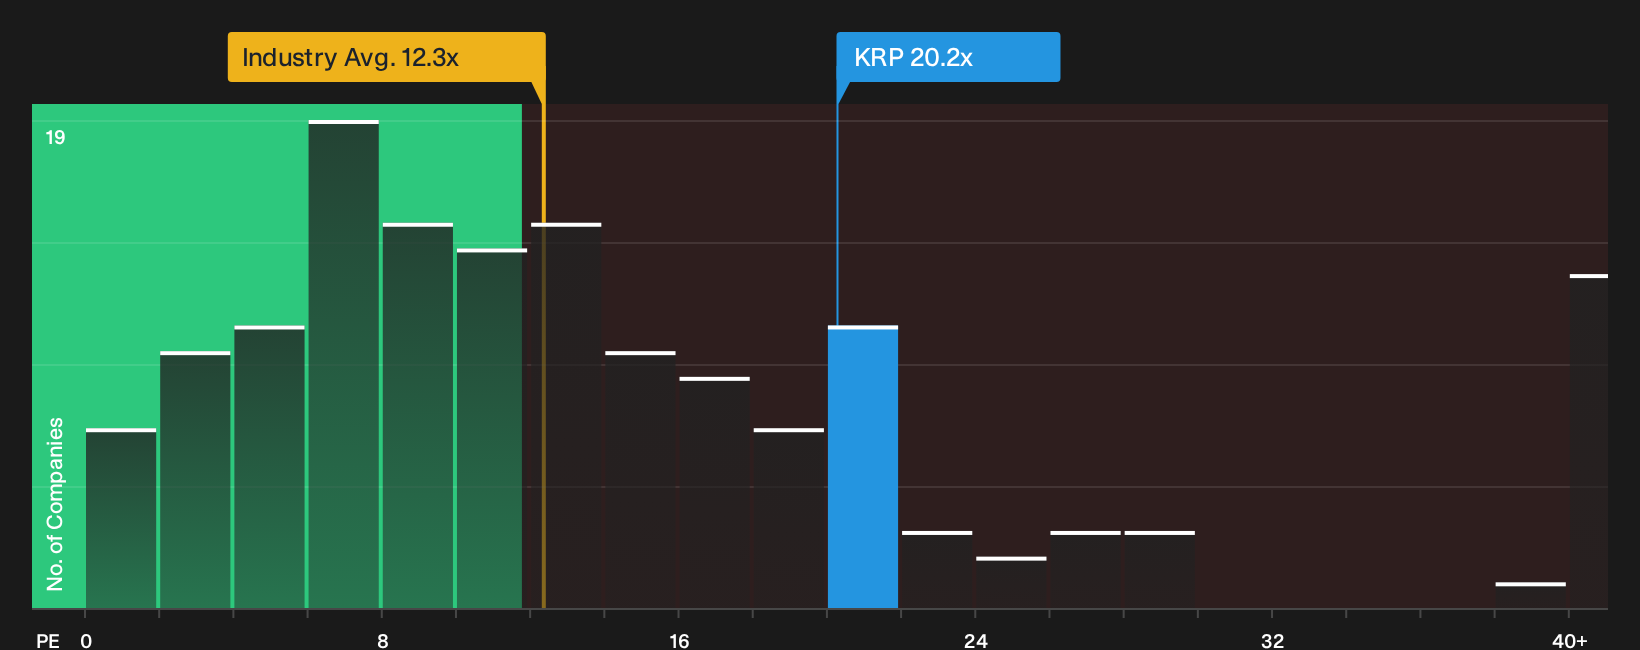
The DCF work and analyst fair value around $19.20 present Kimbell Royalty Partners as attractively priced. The P/E story is harsher. Units trade on about 20.2x earnings, versus 12.2x for the US Oil and Gas group and a peer average of 13x.
Even against an estimated fair ratio of 17.8x, KRP appears expensive on earnings. That gap highlights potential valuation risk if expectations soften. The question is which lens to prioritize, particularly when both distributions and deal making are central to the thesis.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Kimbell Royalty Partners valuation and earnings multiples can spark debate, so move quickly, review the full data set and pressure test both sides of the argument using the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Kimbell Royalty Partners?
If Kimbell Royalty Partners sharpened your focus on value and income, do not stop here. Broaden your opportunity set and pressure test fresh ideas now.
- Spot potential value pivots early and review the 32 high quality undervalued stocks that combine solid fundamentals with priced-in pessimism.
- Prioritise resilience and use the 32 resilient stocks with low risk scores to filter for businesses with sturdier balance sheets and steadier risk profiles.
- Get ahead of the crowd and scan the 20 high quality undiscovered gems before these quieter opportunities attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com