
Top 3 British Undervalued Stocks Trading Up To 48% Below Fair Value
Hotter than expected US inflation has kept interest rate worries alive, which often pushes investors toward dependable cash flow instead of hopeful stories. That puts undervalued UK cash flow stocks in an interesting spot, because solid future cash generation can look even more attractive when money stays expensive. This article highlights three companies from our cash flow discount list that currently trade below estimated fair value based on their projected cash streams.
The three stocks below are just a starting sample from this idea, because the full screen surfaced 26 more companies with equally cash focused narratives that are not covered in this article. To go beyond the shortlist, head straight into the Undervalued Stocks Based On Cash Flows screener to identify, analyze and concentrate on the opportunities that best match your own conviction level.
Shell (LSE:SHEL)
Overview: Shell is a global energy group whose integrated gas, upstream oil and gas, and petrochemicals operations generate large, tradable cash flows.
Operations: Shell earns most of its revenue from Marketing at about $135b and Chemicals and Products at about $132b, with Integrated Gas at about $49b and Upstream at about $44b, while Renewables and Energy Solutions contributes about $42b.
Market Cap: £221.1b
Shell matters for this cash flow focused screen because its integrated gas and upstream engine throws off sizeable, relatively visible cash generation that supports a discounted cash flow valuation signal.
"With an LNG portfolio exceeding 60 million tons and unparalleled trading capabilities, Shell is the company that benefits most from the volatility in the global gas market. Economic growth in Asia and energy security concerns in Europe will increase LNG demand by over 50% by 2040."
What happens to Shell’s cash returns if a single assumption about future LNG market tightness or trading spreads starts to shift?
If that assumption shift matters to you, read the full narrative for Shell to see how Shell’s cash engine could accelerate or stall under different LNG scenarios.
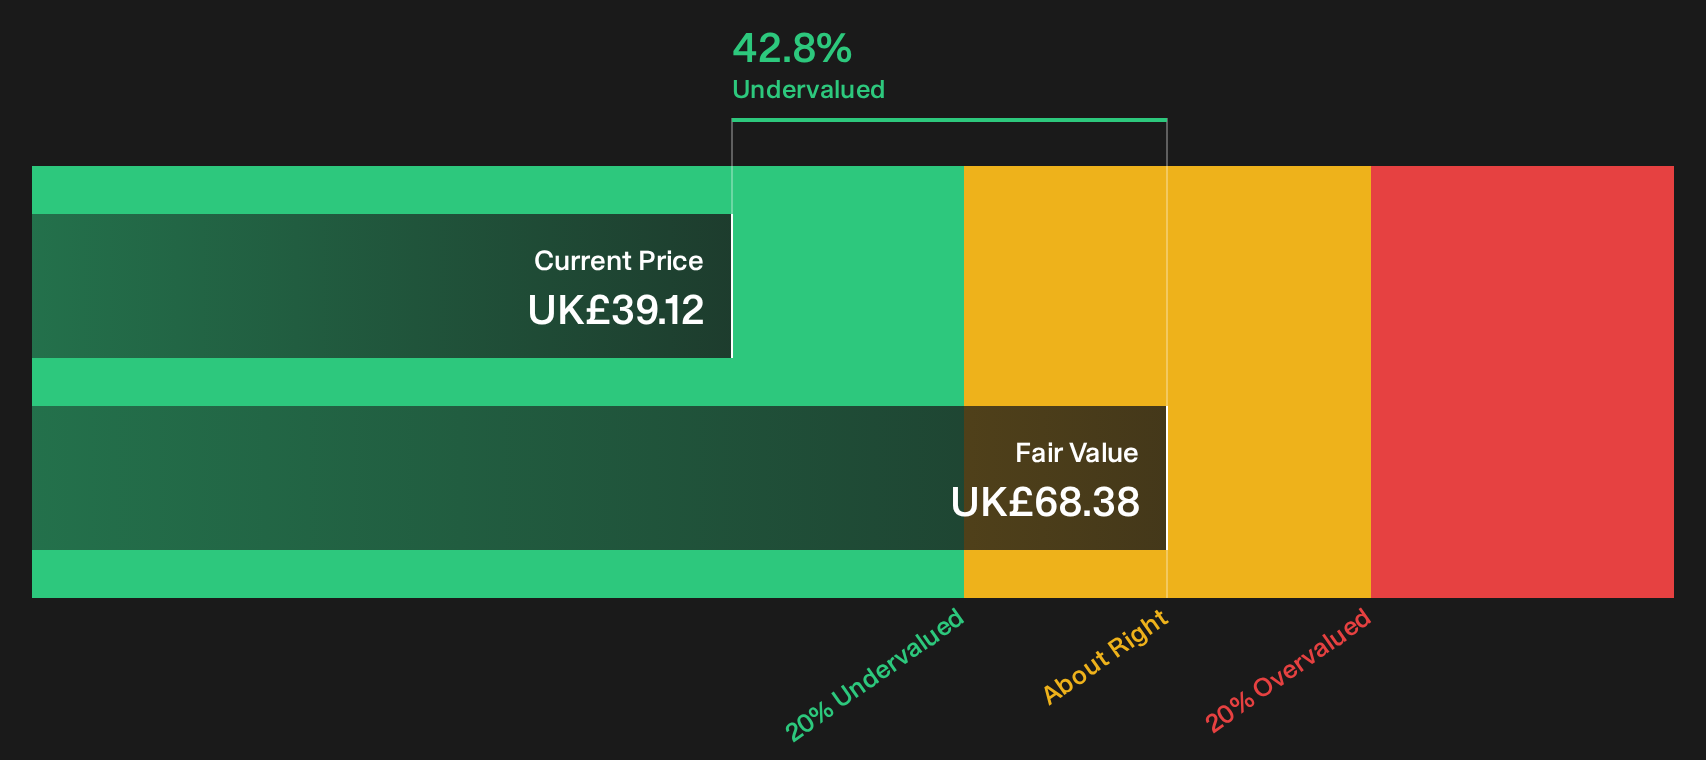
Balfour Beatty (LSE:BBY)
Overview: Balfour Beatty builds, maintains, and invests in large infrastructure projects, with long-term concession assets providing its clearest link to contract-backed cash flows.
Operations: The group generates about £8.0b from Construction Services, £1.5b from Support Services, and £470 million from Infrastructure Investments across the US and UK.
Market Cap: £4.0b
Balfour Beatty matters for a cash flow focused investor because its Infrastructure Investments portfolio ties capital to long-duration, contract-backed projects where future payments can be modelled more cleanly than traditional construction cycles.
"That positions the company well to profit from the Labour government's initiative for growth, the related, mooted slashing of planning and building regulations in particular."
The real test for that cash-flow story sits in how one pressure on future project economics ultimately shapes pricing power and margins.
If that pressure point has your attention, go straight to the full narrative for Balfour Beatty to see how Balfour Beatty’s cash engine could accelerate or stall across different project cycles.
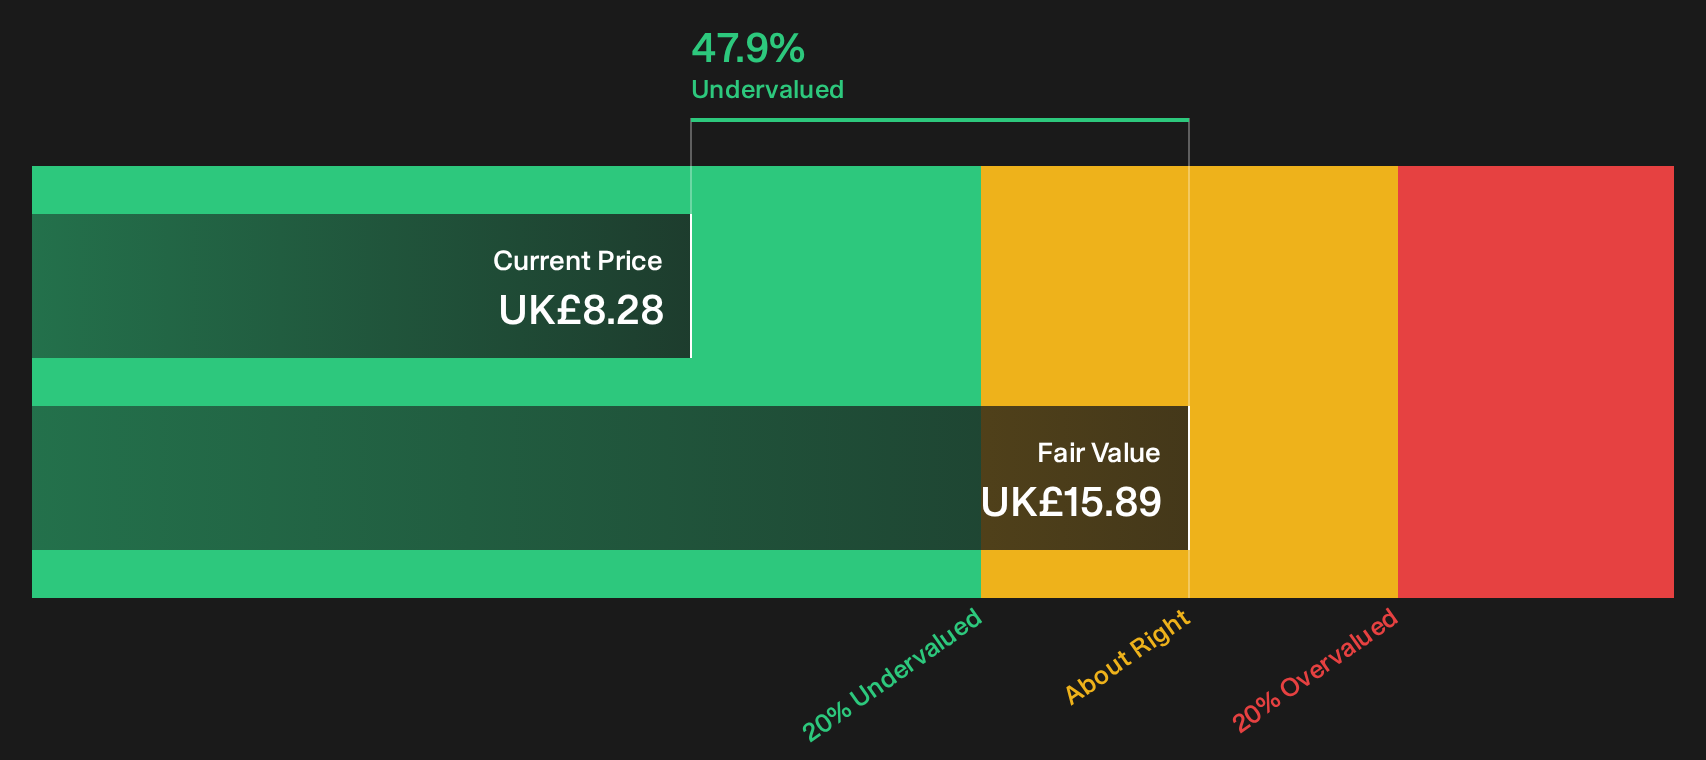
Jupiter Fund Management (LSE:JUP)
Overview: Jupiter Fund Management runs mutual funds and client portfolios across equities and fixed income, earning recurring management fees linked to invested assets.
Operations: Jupiter Fund Management generates about £490 million of revenue from its Investment Management Business, primarily through fee income on managed assets.
Market Cap: £865 million
Jupiter Fund Management matters for this cash flow screen because its fee based asset management engine converts client assets into relatively steady revenue streams that feed directly into discounted cash flow valuation work.
"Ongoing outflows from retail clients, coupled with only modest net inflows from institutional clients, suggest continued pressure on overall assets under management despite recent improvements. Integration costs and execution risk related to the CCLA acquisition introduce medium-term uncertainty, as regulatory and one-off costs may exceed guidance and erode net margins over the next few years, impacting Jupiter's profitability even if top-line growth materializes."
What happens to Jupiter Fund Management’s cash flow appeal if a single moving part in that fee and asset base story shifts direction?
If that pivot is what you care about, read the full narrative for Jupiter Fund Management to see whether Jupiter Fund Management’s fee engine is quietly rebuilding momentum.

Seeking Alternatives Before The Crowd Moves
Fresh ideas move first, and slower money often gets caught chasing momentum once these under the radar stories start breaking out. Scan these curated shortlists while it matters and get in early.
- Target steadier income potential from companies investors often overlook by running the 2 dividend fortresses before yields start dropping and competition for these payouts heats up.
- Track where real AI revenue and cash generation may be building by reviewing the 39 profitable AI stocks that aren't just burning cash while these operators are still flying below wider market attention.
- Position ahead of a possible next leg in electrification by combing through the 43 power grid technology and infrastructure stocks while these infrastructure players remain under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com