
COSCO SHIPPING Ports (SEHK:1199) Trades At An 8% Premium Following Peru Port Interest
Fresh interest from US, Chinese, and Indian investors in a planned US$1.21b deep water port in southern Peru has brought COSCO SHIPPING Ports (SEHK:1199) and its Chancay facility back into focus for shareholders.
At a share price of HK$6.475, COSCO SHIPPING Ports has caught a tailwind, with a 30.81% 90 day share price return and a 20.28% 1 year total shareholder return. This suggests momentum has picked up recently as investors reassess growth prospects and risks around new port projects.
Scan port and infrastructure operators riding similar momentum to COSCO SHIPPING Ports using our handpicked list of solid balance sheet and fundamentals (202 results) as a starting universe.
For COSCO SHIPPING Ports, that sharp move can look like renewed faith in the port portfolio or just a sentiment swing around Peru and regional projects. The valuation work now needs to separate story from fundamentals.
Most Popular Narrative: 8% Overvalued
On the most followed narrative, COSCO SHIPPING Ports screens as modestly above fair value, with a narrative fair value of HK$5.98 against the last close at HK$6.475. The story rests on whether future execution justifies paying that premium today.
The company's proactive global expansion, particularly in emerging markets along key trade corridors such as Southeast Asia, South America, and the Middle East, positions it to capture rising global trade volumes and future throughput growth. This is expected to support sustainable increases in top-line revenue.
Strategic enhancements to COSCO's port network, such as investment in smart port technology, automation, and advanced digitalization, are reducing operating costs and boosting efficiency, which in turn is improving net margins and long-term earnings power.
See why 4 investors see COSCO SHIPPING Ports as 8% overvalued.
Result: Fair Value of HK$5.98 (OVERVALUED)
Still, the COSCO SHIPPING Ports story could be knocked off course if China-linked exposure tightens financial conditions or if rising competition crimps overseas expansion.
Find out about the key risks to this COSCO SHIPPING Ports narrative.
Another View: COSCO SHIPPING Ports Through The P/E Lens
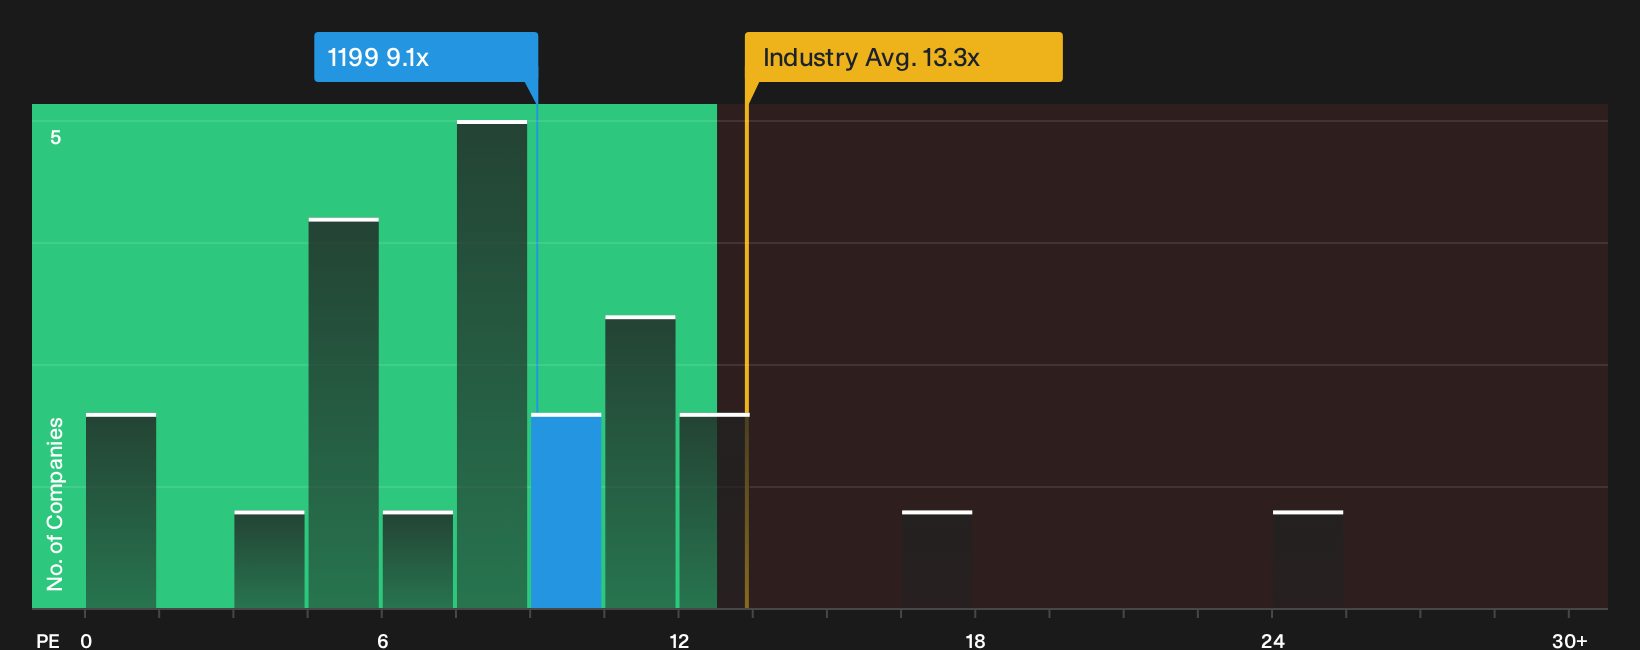
The first story has COSCO SHIPPING Ports trading about 8% above a HK$5.98 narrative fair value. On straight P/E math though, the picture changes. At 9.1x earnings, the stock sits cheaper than both the Asian Infrastructure group on 13.3x and its peer average on 10.7x, yet slightly richer than its own fair ratio of 8.6x.
That mix of discount versus sector and premium versus fair ratio points to a tug of war between potential upside and the risk that the market leans back toward that lower 8.6x anchor. Which side of that trade-off matters more for your thesis on COSCO SHIPPING Ports?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on COSCO SHIPPING Ports, with both risks and rewards in play, mean the next move comes down to your own read of the data. To weigh those trade offs for yourself and see what other investors are watching, start with the 2 key rewards and 2 important warning signs.
Looking for more COSCO SHIPPING Ports investment ideas?
If you stop with COSCO SHIPPING Ports alone, you risk missing other opportunities that fit your style, your risk tolerance, and the kind of portfolio you want to build.
- Target potential mispricings by scanning a curated pool of quality businesses that look cheap on the numbers with the 187 high quality undervalued stocks.
- Build a steadier income base by scouting companies with robust payout profiles and strong yield support using the 217 dividend fortresses.
- Dial back portfolio risk by filtering for resilient businesses with healthier balance sheets and lower risk scores through the 224 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com