
XPO (XPO) Could Be 22% Below Fair Value On New Service Center Expansion
Recent analyst coverage around XPO (XPO) has focused on its expansion plans, after the company opened new freight service centers in Mesa, Arizona, and Cameron, Missouri, to address rising regional demand.
XPO’s latest service center openings land after a period where the share price has cooled in the short term, with the 90-day share price return down 11.56%, even as the year-to-date share price return is 30.52% and the 5-year total shareholder return sits at 276.19%. This suggests long term momentum has been strong, while recent moves hint at investors reassessing near term expectations around growth and risk.
Capitalize on the freight momentum story by scanning hand-picked logistics and industrial carriers in the list of solid balance sheet and fundamentals (25 results) that may offer similar expansion potential with sturdier finances.XPO is now priced well above its levels of a few years ago, yet it has just hit a patch of short term weakness. Does that wobble suggest a better opportunity for buyers, or does it call for more caution as you assess valuation next?
Most Popular Narrative: 22% Undervalued
XPO last closed at $181.15, while the most followed narrative anchors fair value at about $231.83 using an 8.56% discount rate. That gap sets up a thesis that focuses on productivity, capacity and cash generation rather than only on freight volume recovery.
The company is positioned to benefit from an industry wide reset in LTL capacity. Service center counts and door counts at the sector level are down since 2021, while XPO has raised its own tractor, trailer, and door capacity and now carries more than 30% excess doors, which can support shipment growth and revenue as freight demand recovers.
See why 12 investors see XPO as 22% undervalued.
Result: Fair Value of $231.83 (UNDERVALUED)
Still, the XPO story can unravel if freight demand softens for longer or if rising labor costs outpace the productivity gains that analysts are banking on.
Find out about the key risks to this XPO narrative.
Another Look At XPO Through Market Pricing
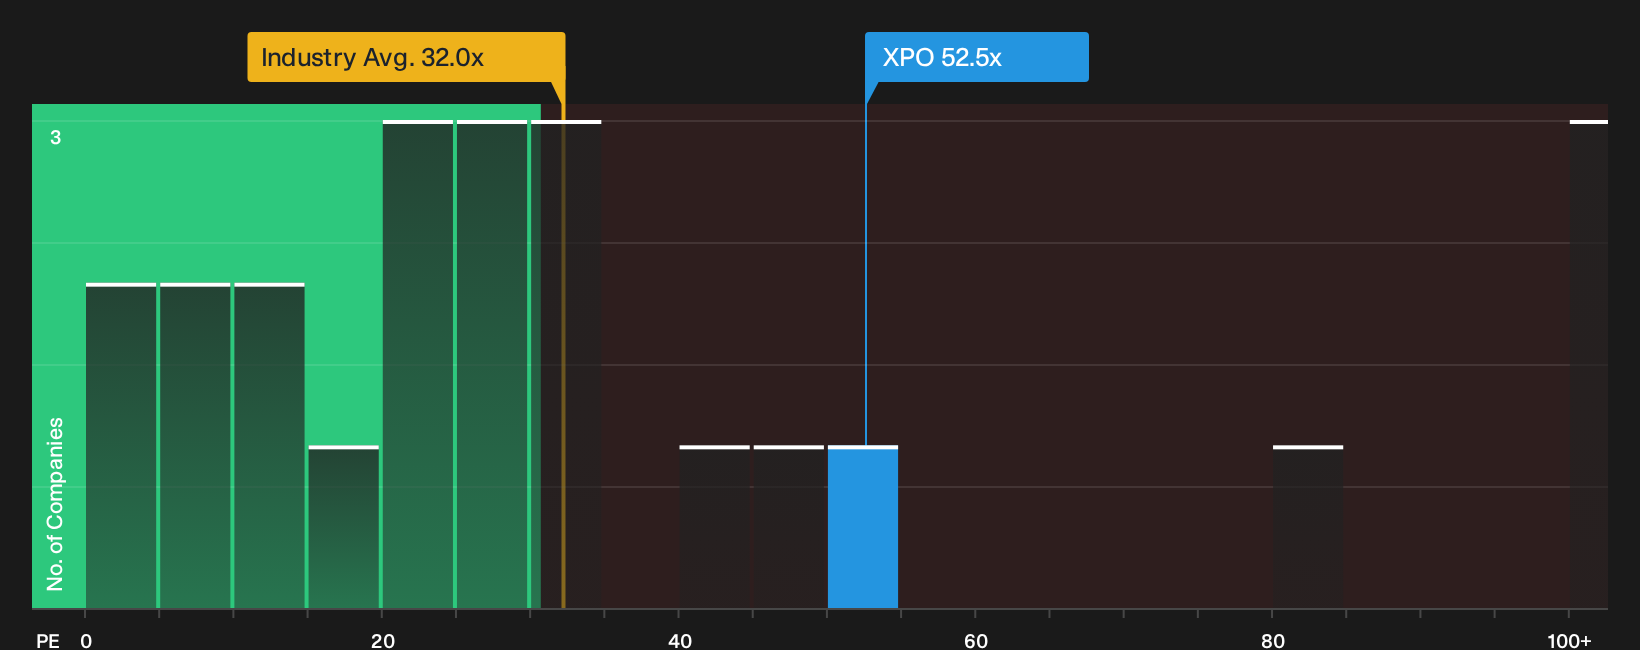
On the flip side of that fair value story, XPO trades on a P/E of 52.5x, compared with 32.3x for the wider US Transportation group and a fair ratio of 21.8x. That gap points to rich expectations baked into the price. Is that premium a comfort or a warning for you as an investor?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the XPO story can feel confusing, so move quickly on your own homework by weighing both the risks and the upside. Start by looking at the 3 key rewards and 2 important warning signs.
Looking for more XPO style investment ideas?
If you stop with XPO, you miss a wider set of ideas where balance sheets, income strength, and return potential line up more cleanly for your watchlist.
- Target resilient potential by scanning companies with lower risk profiles using the 32 resilient stocks with low risk scores.
- Hunt for mispriced quality by reviewing the 32 high quality undervalued stocks that pair strong fundamentals with more modest expectations.
- Build a sturdier core by filtering for businesses with robust finances through the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com