
How Investors Are Reacting To SoftBank (TSE:9984) AI Selloff Pressure
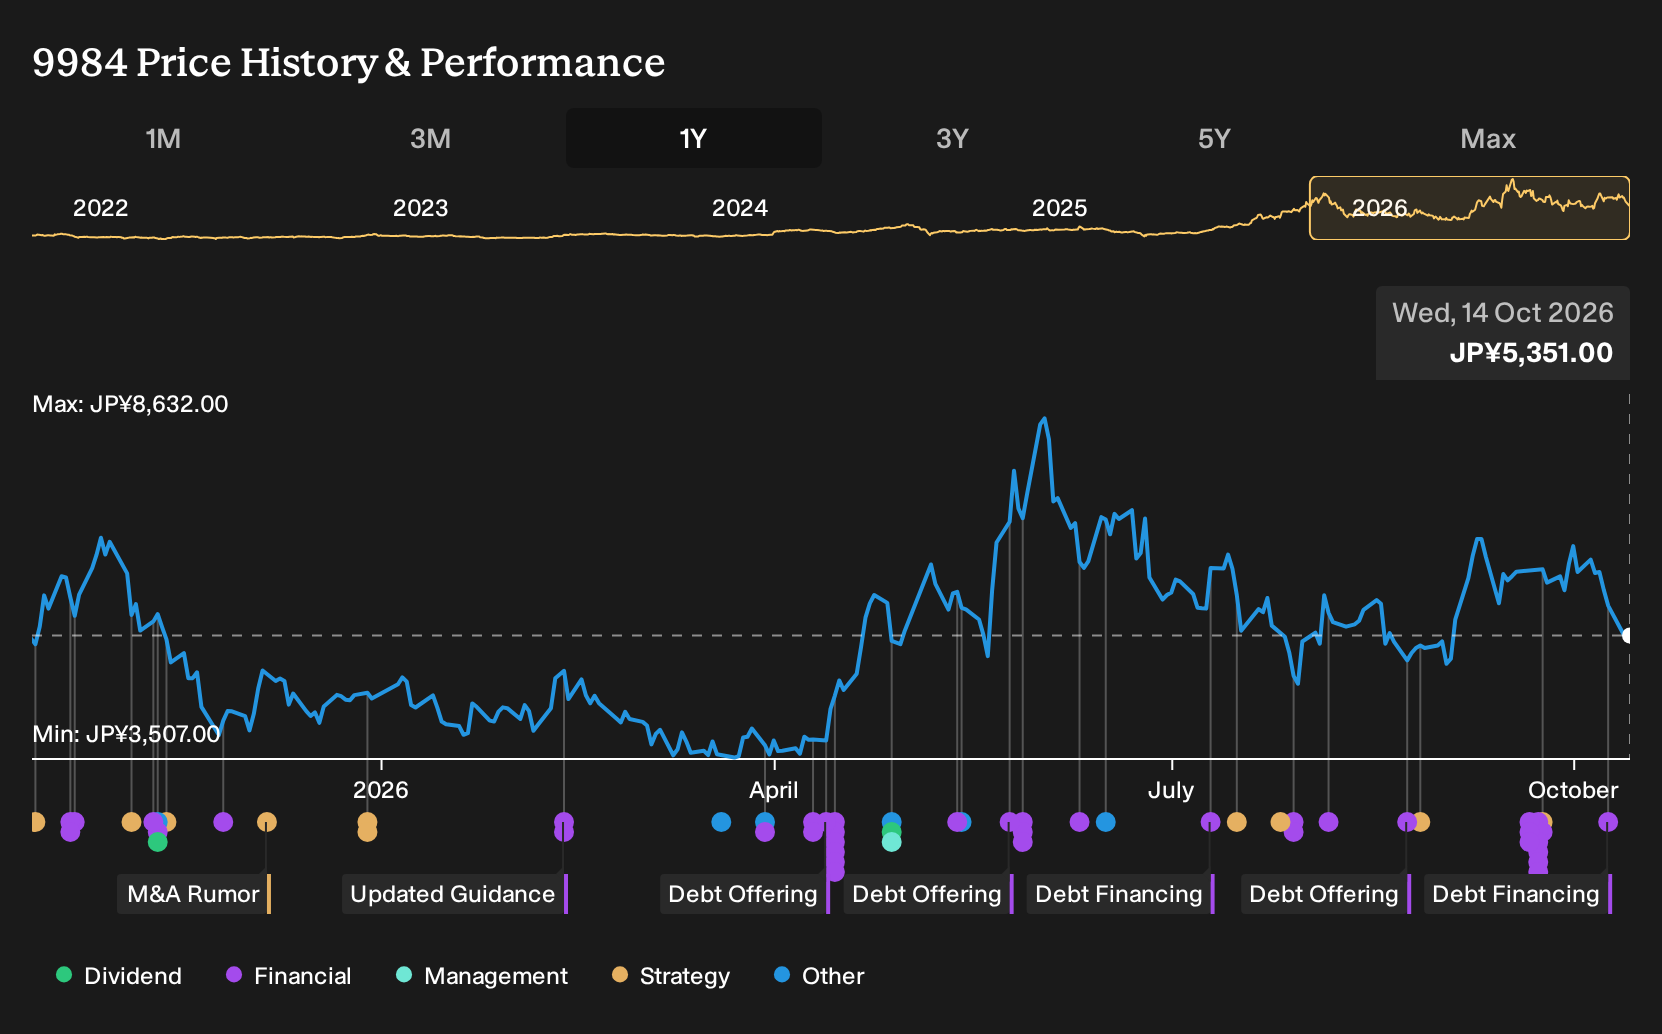
- SoftBank Group has redeemed all of its remaining €405.1 million 2.875% euro senior notes originally due January 2027 and issued several new unsecured yen straight bonds maturing between 2029 and 2033.
- This refinancing reshapes SoftBank Group's funding mix, which is relevant for an investment story built on large AI commitments and sizeable leverage.
- We now consider how SoftBank Group's refinancing and AI sector exposure might influence its investment narrative and risk profile.
Compare SoftBank Group’s refinancing and AI ambitions with other potential opportunities by scanning a curated list of 92 AI infrastructure stocks that could be setting up for the next leg of demand.
SoftBank Group Investment Narrative Recap
To own SoftBank Group, you effectively need to back a high conviction AI infrastructure and software story that sits on top of a complex financing stack. The short term hinge point is simple: can management keep funding that program on acceptable terms while AI exposed equities stay choppy and earnings are forecast to decline over the next few years?
The fresh mix of early euro note redemption and new yen bonds slightly tilts that balance but does not overhaul it. Debt is still not well covered by operating cash flow, and equity markets remain sensitive to AI sentiment shifts, especially around OpenAI timelines and SB Energy listing progress.
The most relevant move here is the decision to redeem all remaining €405.1m 2.875% euro notes due January 2027 and replace them with unsecured yen straight bonds maturing out to 2033. That choice extends parts of SoftBank Group’s funding profile and concentrates more obligations in its home currency.
For you, the key link to catalysts is execution capacity. Arm order visibility, SB Energy’s prospective Nasdaq listing, and AI data center build outs all lean on dependable access to funding. This refinancing nudges duration and currency mix while leaving the central questions of leverage, liquidity, and AI deal outcomes firmly in focus.
SoftBank Group’s AI Story Through The Numbers
SoftBank Group's narrative projects ¥10,084.0b revenue and ¥757.4b earnings by 2029. This projection draws on analyst assumptions of 8.0% yearly revenue growth and an earnings decrease of about ¥4,151.0b from current earnings of ¥4,908.4b.
Uncover how SoftBank Group's fair value indicates a 45% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts refinancing risk front and center for SoftBank Group. The most bearish analysts already pencilled in revenue of about ¥9,355.4b and earnings near ¥334.8b by 2029 before this bond switch, far below consensus. That cohort reads today’s funding moves more cautiously, so it makes sense to compare several narratives and decide which assumptions you find more realistic.
Explore 4 other SoftBank Group fair value estimates, including one that suggests as much as 53% downside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SoftBank Group research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for SoftBank Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SoftBank Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond SoftBank Group?
Once you have a view on SoftBank Group, it can help to line it up against other opportunities that fit different risk and income profiles. Use the Simply Wall St Screener to build a watchlist that reflects how you actually want your portfolio to work for you.
- If you want to focus on quality and price discipline, scan a curated set of companies through 15 high quality undervalued stocks that combine solid fundamentals with appealing valuations.
- If resilience matters most to you, filter for businesses with stronger financial footing by working through the list of solid balance sheet and fundamentals (21 results) and see which ones hold up best under stress.
- If income is your priority, target potential yield anchors for your portfolio by reviewing the 28 dividend fortresses that currently clear a 5% threshold.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com