
Exelon (EXC) Gets A Fresh Look On Data Center Demand And A More Balanced Valuation
Exelon (EXC) is back in focus after a KeyBanc analyst shifted the stock from Underweight to Sector Weight, tying the call to rising data center power needs and fresh battery storage activity at ComEd.
Recent trading tells a mixed story. Exelon’s 1-day and 7-day share price returns of 0.52% and 1.58% hint at improving short-term sentiment, even as the 90-day share price return is down 7.43% and the 1-year total shareholder return is down 7.36%. This is against a still positive 3-year total shareholder return of 18.36% and 5-year total shareholder return of 40.96%, which suggests longer term holders have seen more resilient outcomes despite the current reset around data center and battery storage expectations.
Scan how other grid and data center power plays are lining up by comparing Exelon with our hand picked 43 power grid technology and infrastructure stocks in this theme.
Exelon now has a cleaner data center story, fresh battery storage projects at ComEd, and a less bearish analyst stance. The operations read solid. The open question is whether the current share price does them justice.
Most Popular Narrative: 13% Undervalued
On the most followed narrative, Exelon’s fair value of $48.71 sits meaningfully above the last close at $42.34. This frames the current debate around how much of its grid investment and data center story is already in the price.
The rebalanced US$41.7b capital plan that shifts US$1.5b into higher earning transmission while deferring US$1.1b of lower priority distribution projects positions Exelon to pursue its targeted 7.9% rate base growth with a tilt toward assets that can support operating EPS and cash flow.
See why 37 investors see Exelon as 13% undervalued.
Result: Fair Value of $48.71 (UNDERVALUED)
Still, the Exelon narrative could shift if regulators push back harder on rate cases, or if affordability concerns at utilities like PECO squeeze returns and financing costs.
Find out about the key risks to this Exelon narrative.
Another View On Exelon’s Valuation
The crowd narrative leans on a $48.71 fair value, yet Simply Wall St’s DCF model points in the opposite direction. On that framework, Exelon at $42.34 screens as expensive versus an estimated future cash flow value of $9.61. That is a wide gap. Which story do you trust more: cash flows or narratives?
Look into how the SWS DCF model arrives at its fair value.
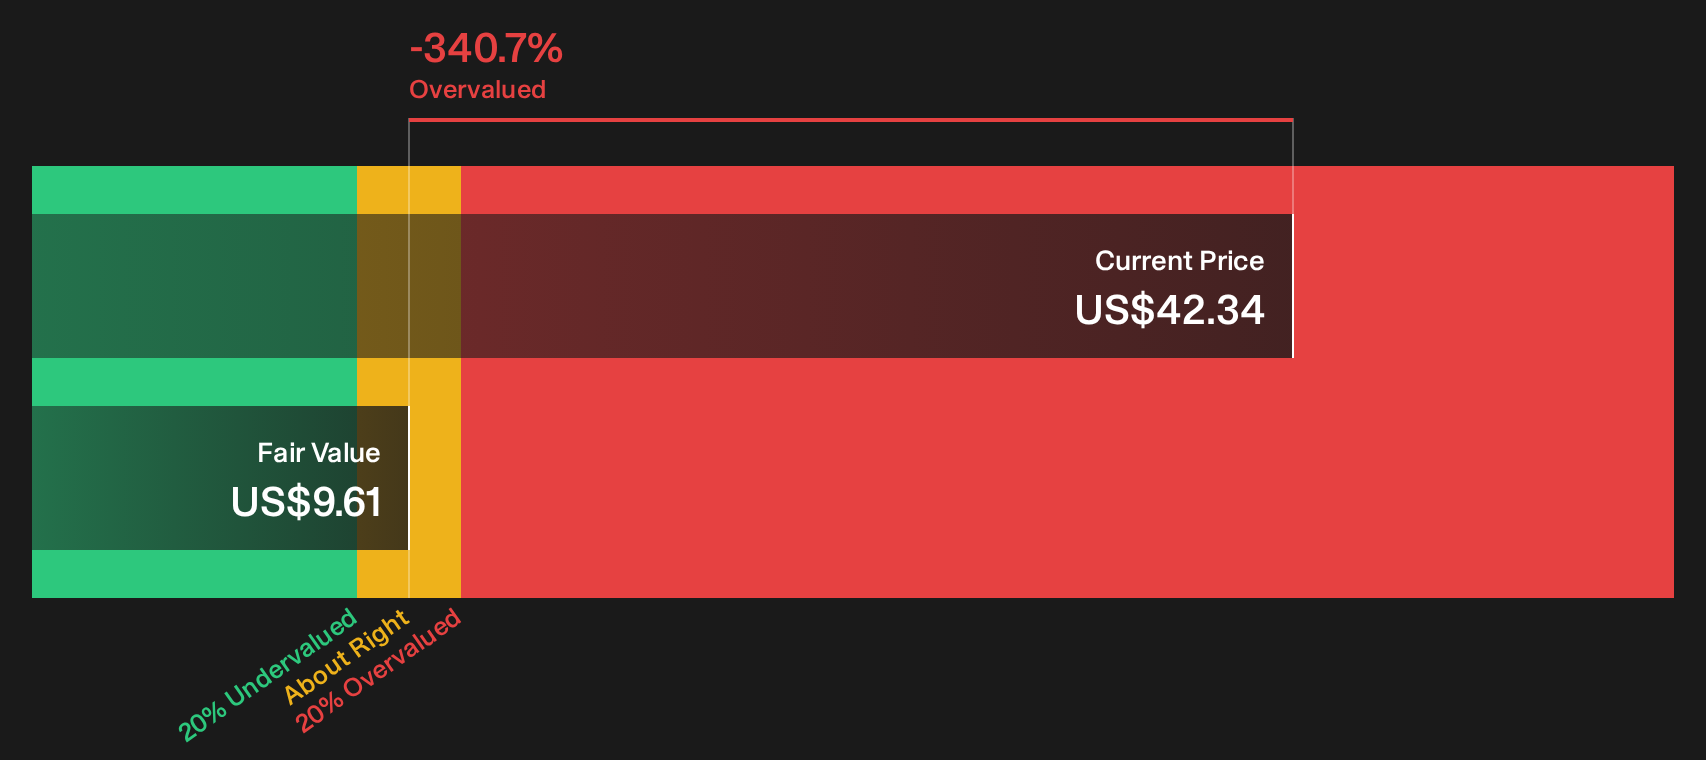
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Exelon for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a clear setup for Exelon, either way you are better off checking the data yourself and forming your own stance. The fastest way to pressure test that view is to weigh the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Exelon?
If Exelon has sharpened your focus on utilities and power infrastructure, do not stop there. Broaden your watchlist now so you are not late to the next setup.
- Target resilient balance sheets by scanning our list of solid balance sheet and fundamentals (25 results), which filters for companies with financial footing built to handle shocks.
- Hunt for mispriced opportunities using the 32 high quality undervalued stocks, which highlights stocks where fundamentals and current prices look out of sync.
- Prioritise stability and peace of mind with the 32 resilient stocks with low risk scores, which focuses on businesses carrying lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com