
3 Dividend Stocks For Investors Seeking Safety As The Buffett Indicator Hits 237%
When Warren Buffett’s favorite market gauge flashes “expensive” at a record 237% of GDP, broad index exposure can feel like walking a tightrope without a harness. At the same time, reliable dividend payers with strong balance sheets may offer a steadier way to collect income while keeping risk in check. This article explores that contrast and highlights 3 dividend stocks exposed to the same forces influencing the Buffett indicator today.
The three dividend stocks that follow are a sample set, while the full quantitative screen identified 22 additional large U.S. companies with similar income profiles and risk checks that are not covered in this article. To see the wider field and identify which ones best fit your portfolio, head straight to the High-Quality Dividend-Paying Blue-Chip Stocks in the U.S. screener.
Tractor Supply (TSCO)
Tractor Supply gives this high quality dividend screen a tilt toward everyday rural spending, which can feel useful when broad market valuations look stretched and investors are hunting for steady cash flows from essential goods.
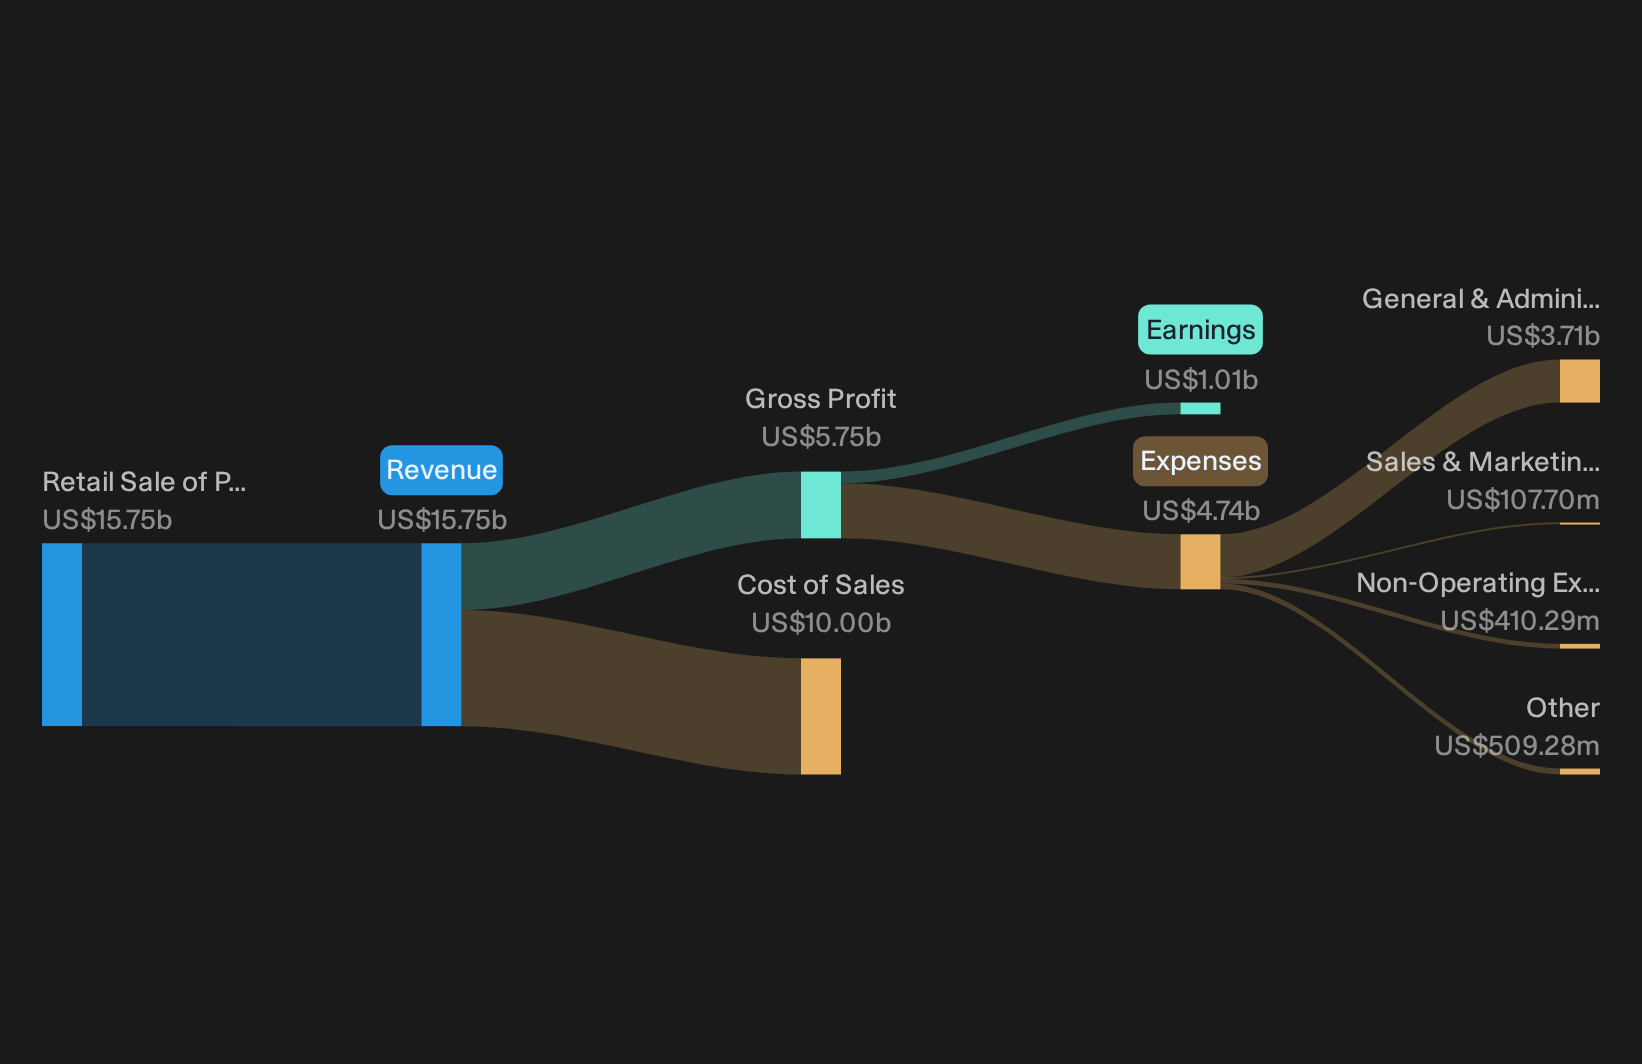
Tractor Supply runs rural lifestyle stores and e commerce sites selling farm, pet, home and hardware supplies, generating about US$15.8b in retail product sales and supported by a market value near US$17.4b, squarely in large cap blue chip territory.
The growing pet ecosystem that now links assortment resets, over 200 new pet products, Freshpet coolers, subscriptions projected above US$200 million in 2026, and the acquisition of VIP Petcare with access to about 1 million pets annually may support steadier pet category revenue and earnings contribution.
What happens to Tractor Supply’s appeal depends heavily on how one quiet pressure shapes the balance between dependable income and future margin strength.
That quiet pressure is exactly what the full narrative for Tractor Supply unpacks in detail, showing where Tractor Supply’s rural cash flows could be masking both risk and upside.
A. O. Smith (AOS)
A. O. Smith fits the screener’s high quality dividend brief as a long established water heater and treatment specialist whose products keep homes, hotels and hospitals running, which can feel useful when investors want income from essentials instead of faster moving stories.
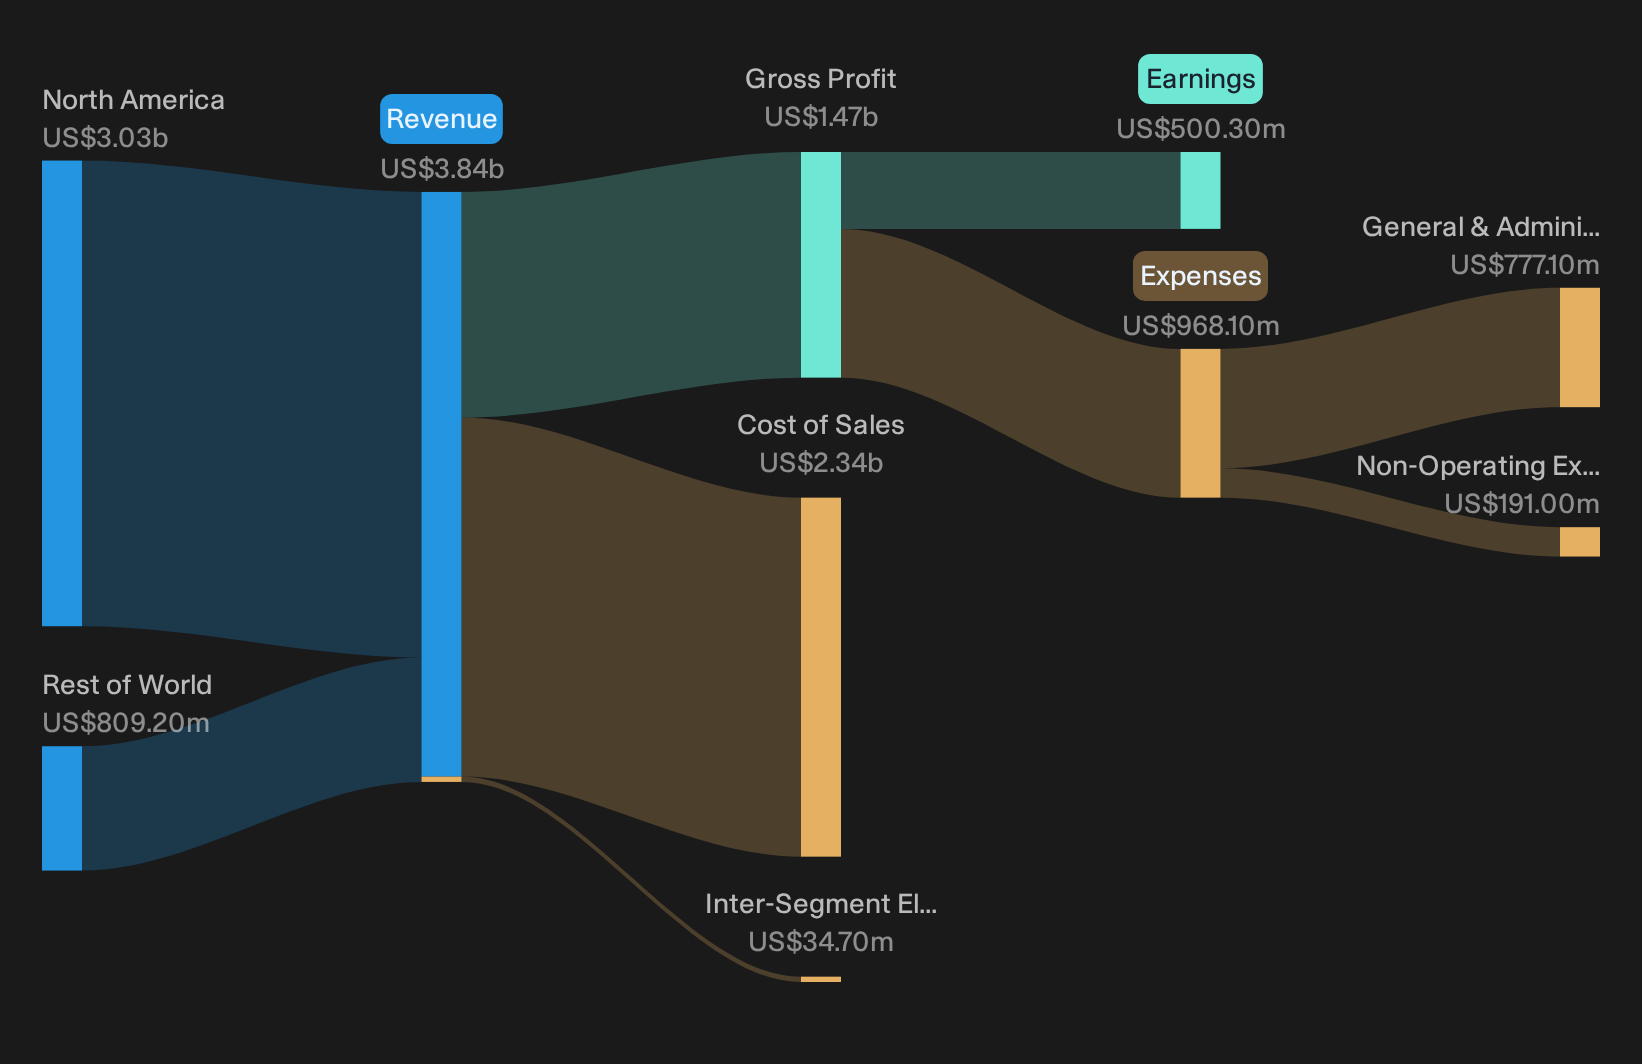
A. O. Smith manufactures residential and commercial water heaters, boilers and water treatment systems sold under multiple brands across wholesale, retail and e commerce channels, generating about US$3 billion of its roughly US$3.8 billion in revenue from North America and carrying a market value near US$7.7 billion.
In a market where the Buffett indicator is flashing expensive, A. O. Smith’s focus on hot water, filtration and treatment gives you exposure to a basic service that rarely goes out of style. That is exactly where the company is leaning harder.
Increasing regulatory focus on energy efficiency and sustainability in water heating is prompting A. O. Smith to accelerate investment and launch new high efficiency and smart products such as condensing boilers and tankless water heaters, which could support future revenue and gross margin growth as higher priced systems gain share.
What happens if one less visible shift in where those high efficiency units are sold changes the balance between steady income, pricing power and margin strength?
That quiet shift is exactly what the full narrative for A. O. Smith unpacks, showing how accelerating efficiency demand, regional mix and pricing power could reshape A. O. Smith’s next chapter.
Stryker (SYK)
Stryker brings a healthcare tilt to this high quality dividend screen, pairing large cap scale with medical technology that hospitals rely on every day.
Stryker is a US medical technology group worth about US$108.4b, with roughly US$9.7b of revenue from Orthopaedics and about US$16.1b from MedSurg and Neurotechnology products serving hospitals and surgeons worldwide.
Stryker offers a way to lean into durable healthcare demand when broad indices look stretched, with its mix of implants, surgical tools and robotics giving this dividend screen exposure to procedures that tend to run regardless of market swings.
Expanding use of Stryker’s Mako platform, including record installations, broader procedure coverage such as shoulder and advanced hip or revision, and the rollout of Mako RPS for handheld knee robotics, supports a larger orthopedic addressable market and can lift revenue and associated service earnings over time.
What investors really need to watch is how one less visible constraint shapes the payoff between that growing installed base and future margin strength.
That hidden constraint is exactly what the full narrative for Stryker unpacks, explaining how Stryker’s accelerating install base, pricing power and capital intensity could decouple earnings from simple procedure counts.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. The best breakouts often move before most investors even notice them, while momentum can drop quickly once the crowd piles in. Consider acting early if an idea fits your strategy and risk tolerance.
- Capture potential early movers in niche corners of the market by scanning 20 high quality undiscovered gems that filter for strong balance sheets and real earnings power before they get widely noticed.
- Explore the structural shift into smarter automation by reviewing 90 robotics and automation stocks curated for businesses involved in robotics demand while the theme is still developing.
- Review opportunities ahead of potential upgrade cycles by checking 43 power grid technology and infrastructure stocks tuned to companies building critical grid technology where momentum may develop before broader attention increases.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com