
Halozyme Stock Has The Bull Case Changed After Argenx Deal Expansion?
- Halozyme Therapeutics reported that argenx has expanded its global collaboration and license agreement to use the ENHANZE platform on two additional exclusive targets, taking argenx’s total exclusive ENHANZE targets from six to eight and increasing Halozyme’s potential milestone and royalty income tied to those programs.
- The broader ENHANZE footprint with argenx reinforces Halozyme Therapeutics’ royalty focused model, since each new partnered target can support long dated, asset light revenue streams if products reach the market.
- We will now look at how this deeper ENHANZE access for argenx could reshape Halozyme Therapeutics' royalty centric investment narrative.
Scan beyond Halozyme Therapeutics and size up other asset light compounders that use royalty and licensing models with the hand picked 20 high quality undiscovered gems that could sit in a similar sweet spot.
Halozyme Therapeutics Investment Narrative Recap
To own Halozyme Therapeutics, you need to believe its enzyme platforms keep attracting partners and that existing ENHANZE programs keep building meaningful royalty pools over time. The expanded argenx deal adds two more shots on goal, but it does not change the near term reality that royalty growth still depends on how quickly current subcutaneous launches scale and are used in practice.
The biggest short term swing factor is execution on partner launches and label expansions for existing ENHANZE products, while the key risk remains pressure on pricing and competition from rival subcutaneous platforms that could slow new deals. This argenx update slightly widens the opportunity set, but it does not remove those core uncertainties.
The argenx expansion matters most when set against Halozyme Therapeutics’ broader push to deepen its royalty pool, including newer platforms like Hypercon and Surf Bio that are being prepared for early trials. More partnered targets give the business a larger pipeline of potential royalties, but commercial uptake, not just deal count, will drive actual cash generation.
Investors also have to weigh balance sheet and earnings quality questions, including the use of debt and the impact of one off items on recent results. In that context, adding more ENHANZE targets for argenx slightly strengthens the long run royalty story, while the main operational catalysts still sit with how existing high profile launches such as Darzalex and VYVGART perform.
Halozyme Therapeutics' current analyst narrative points to US$2.2b in revenue and US$1.1b in earnings by 2029, based on an assumed 9.9% yearly revenue growth rate and an earnings increase of about US$686.4m from US$413.6m today.
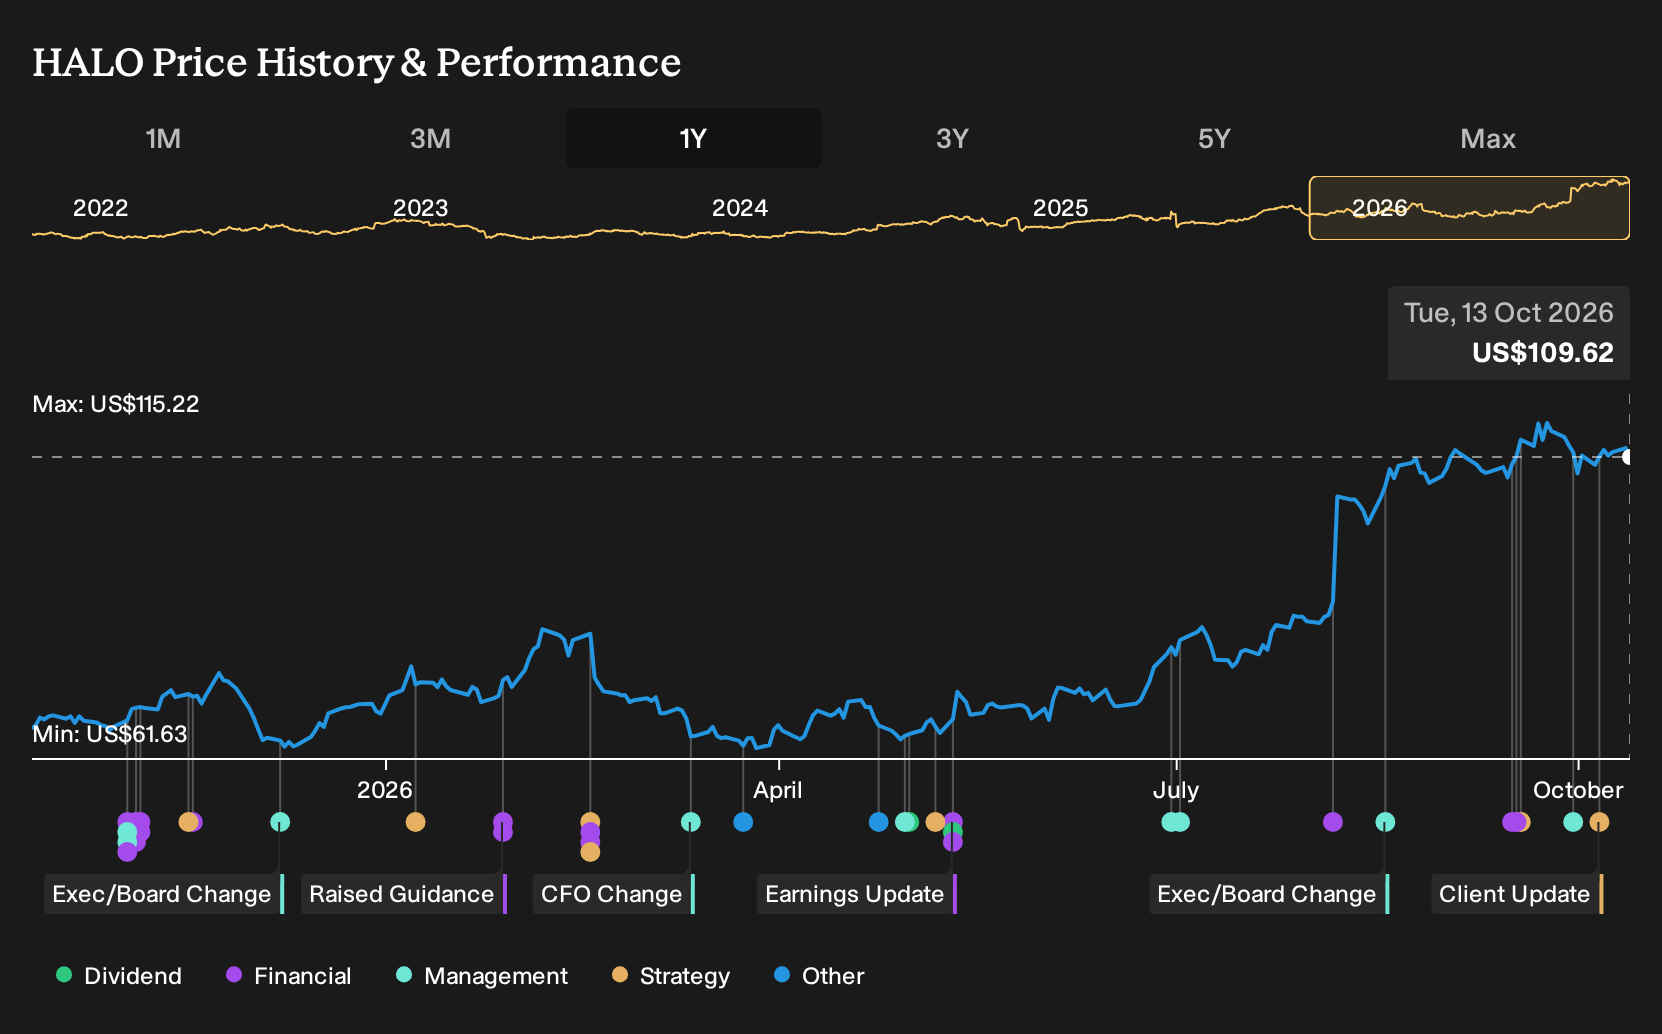
Uncover how Halozyme Therapeutics' fair value indicates a 9% potential downside to its current price, a valuation premium that leaves little room for error.
Exploring Other Perspectives
You might see this argenx expansion and focus on competition risk instead. The most bearish Halozyme Therapeutics analysts were already building in pressure from rival subcutaneous platforms and a lower P/E, even while still modeling about US$2.2b of 2029 revenue and roughly US$1.2b of earnings. Their forecasts came before today’s news, so their story may shift.
Explore 4 other Halozyme Therapeutics fair value estimates, including one that suggests as much as 9% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Halozyme Therapeutics research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Halozyme Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Halozyme Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Halozyme Therapeutics?
If the Halozyme Therapeutics story has you thinking about royalty driven models, balance sheet strength, or different ways to pursue compounders, it can help to line it up against a wider watchlist built with a clear framework.
- Focus on quality at a discount by starting with companies that pair solid fundamentals with potentially attractive pricing through 32 high quality undervalued stocks.
- If capital preservation sits near the top of your priority list, filter for businesses that score well on resilience and financial risk using the 32 resilient stocks with low risk scores.
- For investors who care most about robust finances and staying power, build a shortlist from the list of solid balance sheet and fundamentals (25 results) to keep your research pipeline stocked with sturdier options.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com