
What Zee Doubters Saw Before The Drop
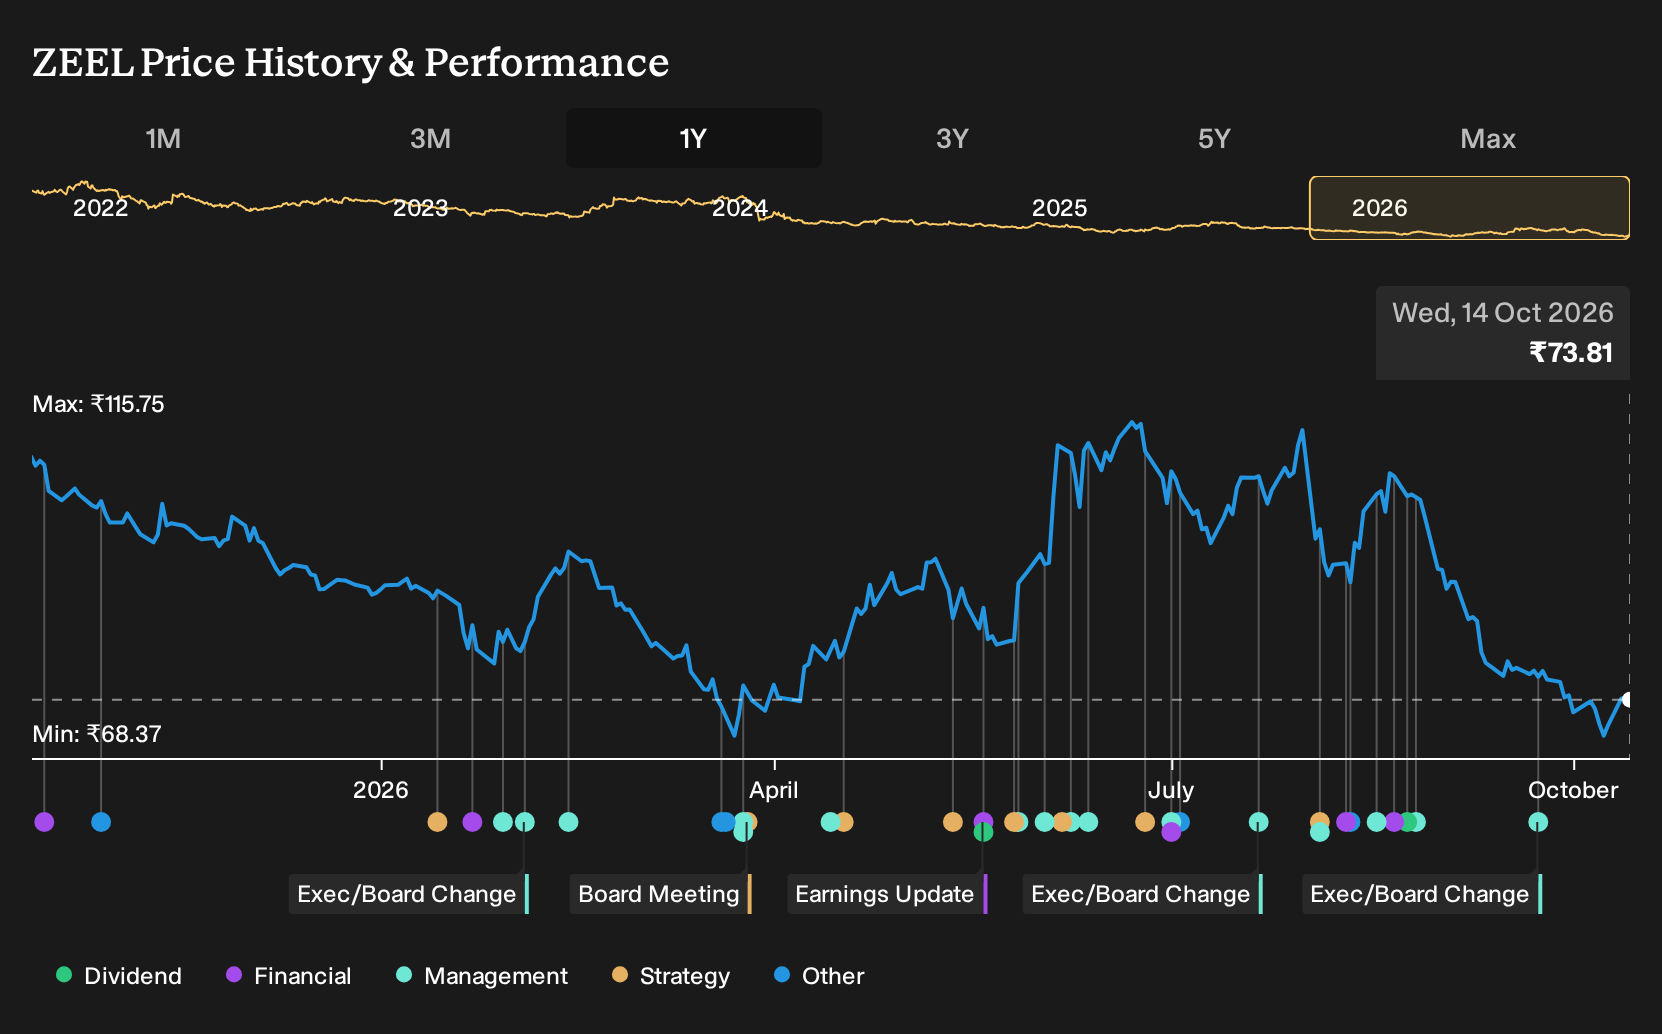
Zee Entertainment Enterprises has just reported Q1 2027 figures that show total revenue at ₹19,073m and net income at ₹763m, with net margin at 4.0%, compared with 7.9% a year earlier. Investors who held Zee Entertainment Enterprises over the past year are down 31.2%, including dividends. If you had committed fresh capital a year ago on the back of the OTT growth story, how much of that decline now depends on whether margins can recover meaningfully?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind Zee Entertainment Enterprises. Zero in on 187 high quality undervalued stocks for companies trading below our estimates.
The Two Competing Stories Around Zee Entertainment Enterprises
The shares cost ₹109 at the start of the period, and investors in Zee Entertainment Enterprises were really choosing between two clear stories.
The bullish narrative saw a fair value of ₹148. It leaned on strong digital momentum from language focused ZEE5 plans and regional content, as well as tighter cost control that, in the thesis, supported higher net margins over time.
The bearish view put fair value at ₹98. That thesis focused on structural pressure on linear TV revenues as audiences moved to OTT, and the risk that heavy digital content spending would keep squeezing profitability.
What The Zee Entertainment Evidence Actually Showed
Q1 2027 results gave Zee Entertainment investors a clear test of the margin story. Total revenue reached ₹19,073m compared with ₹18,248m a year earlier, which supported the growth leg of the bullish case. Net income slipped to ₹763m from ₹1,437m and net margin moved from 7.9% to 4.0%, which challenged the profitability assumptions. Overall, the evidence pointed in both directions.
The key lesson is simple. When a thesis leans on better profitability, focus on net margin alongside revenue, and then track whether both move in the same direction in each set of results for any media stock.
What You Are Really Buying In Zee Entertainment Today
Zee Entertainment Enterprises now trades at ₹73.81, with the selected Narrative’s Fair Value sitting above that level. The argument focuses on sports rights, digital audiences and tighter people costs as the key levers rather than a broad OTT recovery story.
For the fall to look like an opening instead of a warning, a buyer today would need to believe that higher sports and digital spending converts into durable pricing power that more than covers advertising swings and content costs.
"A key factor is whether Zee Entertainment Enterprises converts its recent gains in digital profitability, sports viewership, and network share into durable monetisation that more than offsets advertising cyclicality and higher content costs."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Where Zee Viewers Go Next
Zee investors are still watching the streaming contest. Viewer attention rarely stops at one app or one country.
Behind the scenes, another global player turns that attention into targeted digital advertising. It uses search data, video viewing and mobile usage to match marketing messages.
The same capabilities support a growing cloud offering for businesses. Companies pay to run data heavy workloads and AI tools on that infrastructure.
If Zee keeps chasing digital viewers, this parallel story matters more. Time on screen can enhance the value of anyone helping advertisers and enterprises reach those users more precisely.
One Narrative has already put a figure on it. → Uncover the company trading 18% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com