
Does Unusual Options Trading Change The Bull Case For Innoviva Stock (INVA)?
- Innoviva, Inc. recently saw heavy trading in its Dec. 18, 2026 US$10.00 call options, with implied volatility ranking among the highest in the equity options market that day.
- This concentration of activity in a single contract highlights that derivatives traders are positioning around a potential major development that is not yet visible in Innoviva’s disclosed operating plans.
- We now look at how this surge in Innoviva options volatility could reshape the investment narrative that investors have been using.
Scan how options traders are positioning around Innoviva, then benchmark that setup against a curated group of potential breakout ideas in the 32 high quality undervalued stocks.
Innoviva Investment Narrative Recap
To own Innoviva, you need to believe its multi pillar model can keep turning respiratory royalties, Innoviva Specialty Therapeutics and equity stakes like Armata and Nortiva Bio into dependable cash generation. The immediate operating focus is on scaling hospital and anti infective products while managing a forecast decline in earnings over the next three years and slower expected revenue growth.
The options volatility does not clearly change the core near term catalyst, which is execution on U.S. product sales targets and preparation for the NUZOLVENCE rollout. The biggest operational risk still sits with any shortfall in the roughly US$1b respiratory royalty stream or a weaker trajectory from GIAPREZA, XACDURO and related therapies.
With no fresh company announcements directly tied to these options moves, the most relevant reference point remains Innoviva’s earlier framing of Innoviva Specialty Therapeutics and NUZOLVENCE as key growth drivers. Management is planning a second half 2026 U.S. launch of NUZOLVENCE for uncomplicated urogenital gonorrhea, aimed at an addressable market of roughly 1.0 to 1.5 million annual patients.
That new product, alongside a target of at least US$150 million of 2026 U.S. net product sales for Innoviva Specialty Therapeutics, gives traders a clear operational event path to anchor around. Any change in launch timing, uptake or pricing would feed directly into how sustainable current earnings, high reported profit margins and the low P/E multiple look against the risk that analyst forecasts already build in declining profit over time.
What The Consensus Innoviva Forecasts Are Actually Saying
Analysts sketch a very specific earnings path for Innoviva. Their models point to revenue growth of 7.8% a year over the next three years, paired with a sharp shift in profitability from an 81.2% profit margin today to 38.9% by 2029. That combination matters for anyone trying to reconcile today’s low P/E multiple with the recent options activity.
On the earnings line, the consensus view has Innoviva moving from current earnings of US$357.2 million to US$214.6 million by 2029. That is an earnings decrease of roughly US$142.6 million in absolute terms, not a growth story, and it is built into the way analysts frame both risk and valuation. Profit per share is expected to land at US$2.43 by that year, with the models also baking in a 3.38% annual decline in shares outstanding over the next three years.
Valuation work in the same reports ties these operating assumptions to a single anchor year. To line up with the analyst targets, Innoviva would need to generate US$551.1 million of revenue and US$214.6 million of earnings in 2029. The stock would then trade at a P/E of 13.1x on those earnings, using a discount rate around 7.2% to 7.24% in the present value math.
Innoviva's narrative projects US$551.1 million revenue and US$214.6 million earnings by 2029. This requires 7.8% yearly revenue growth and an earnings decrease of roughly US$142.6 million from current earnings of US$357.2 million.
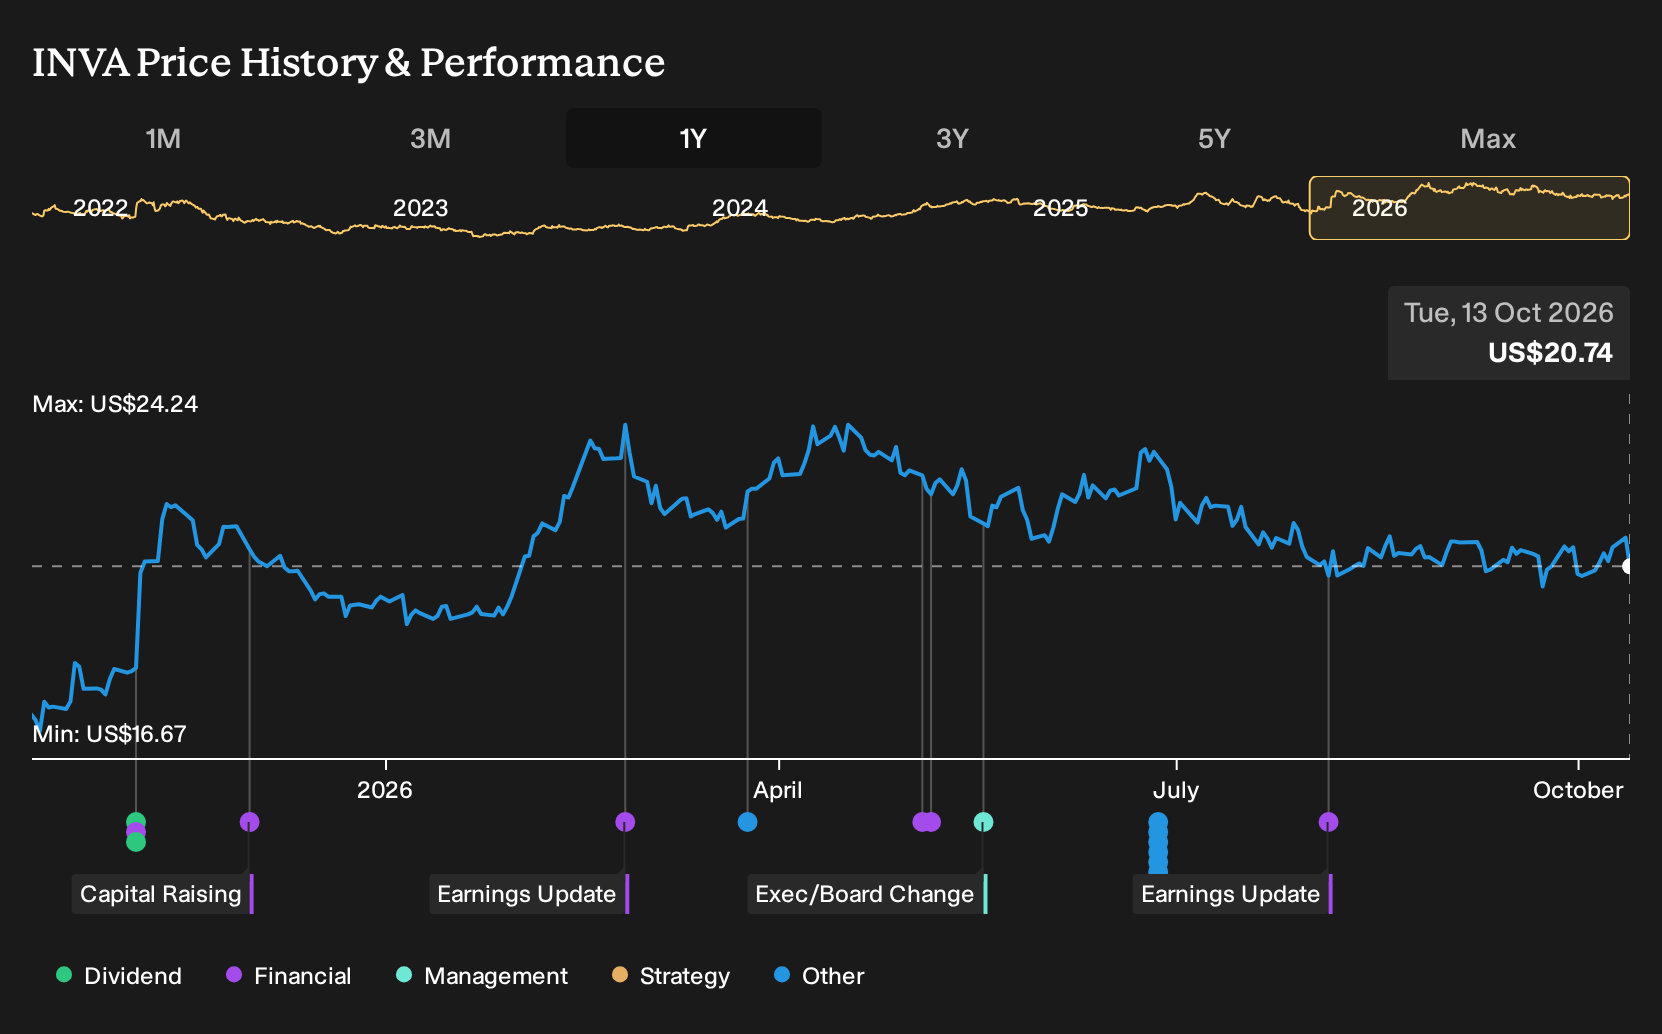
This is where the option flow and the fundamental story meet. Derivatives traders are effectively taking views on whether the market will move closer to the analyst framework that has a US$35.00 consensus price target, with the most optimistic forecast at US$46.00 and the most cautious down at US$18.00. The current share price of US$21.14 sits well below the average target, even though those same forecasters already bake in shrinking margins and lower earnings over time.
For you as an investor, the key question is not whether those targets are right. The more useful exercise is to compare your expectations for NUZOLVENCE rollout, Innoviva Specialty Therapeutics product traction and the US$1b respiratory royalty stream against the revenue and earnings path implied by the 2029 numbers. If your assumptions point to materially different outcomes on any of those pillars, then the options volatility simply signals that other market participants are also stress testing that same spread between story and spreadsheet.
Uncover why Innoviva's fair value indicates a 69% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Options traders are now effectively asking whether Innoviva’s NUZOLVENCE launch can really earn the premium storyline baked into earlier guidance. The most cautious analysts were already modeling revenue of about US$425.8 million and earnings near US$127.2 million by 2029. That is a far more pessimistic setup, and today’s volatility could push those narratives to evolve in very different directions.
Explore 2 other Innoviva fair value estimates, including one that suggests it could be worth just $35.00!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so consider your own analysis.
- A great starting point for your Innoviva research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Innoviva. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Innoviva's overall financial profile at a glance.
Looking For More Investment Ideas Beyond Innoviva?
Once you have a view on Innoviva, it can help to pressure test that thesis against other opportunities that share similar financial traits or very different risk profiles.
- If you want to focus on value backed by robust fundamentals, line up Innoviva against a list of solid balance sheet and fundamentals (25 results) and see how its financial footing compares.
- For readers who care most about stability and capital preservation, weigh Innoviva against a 32 resilient stocks with low risk scores that screens for resilience first.
- If you prefer to hunt for potential future leaders before they become widely followed, contrast Innoviva with a 20 high quality undiscovered gems that filters for quality companies still flying under the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com