
What AZZ (AZZ)'s Earnings Beat Means For Shareholders
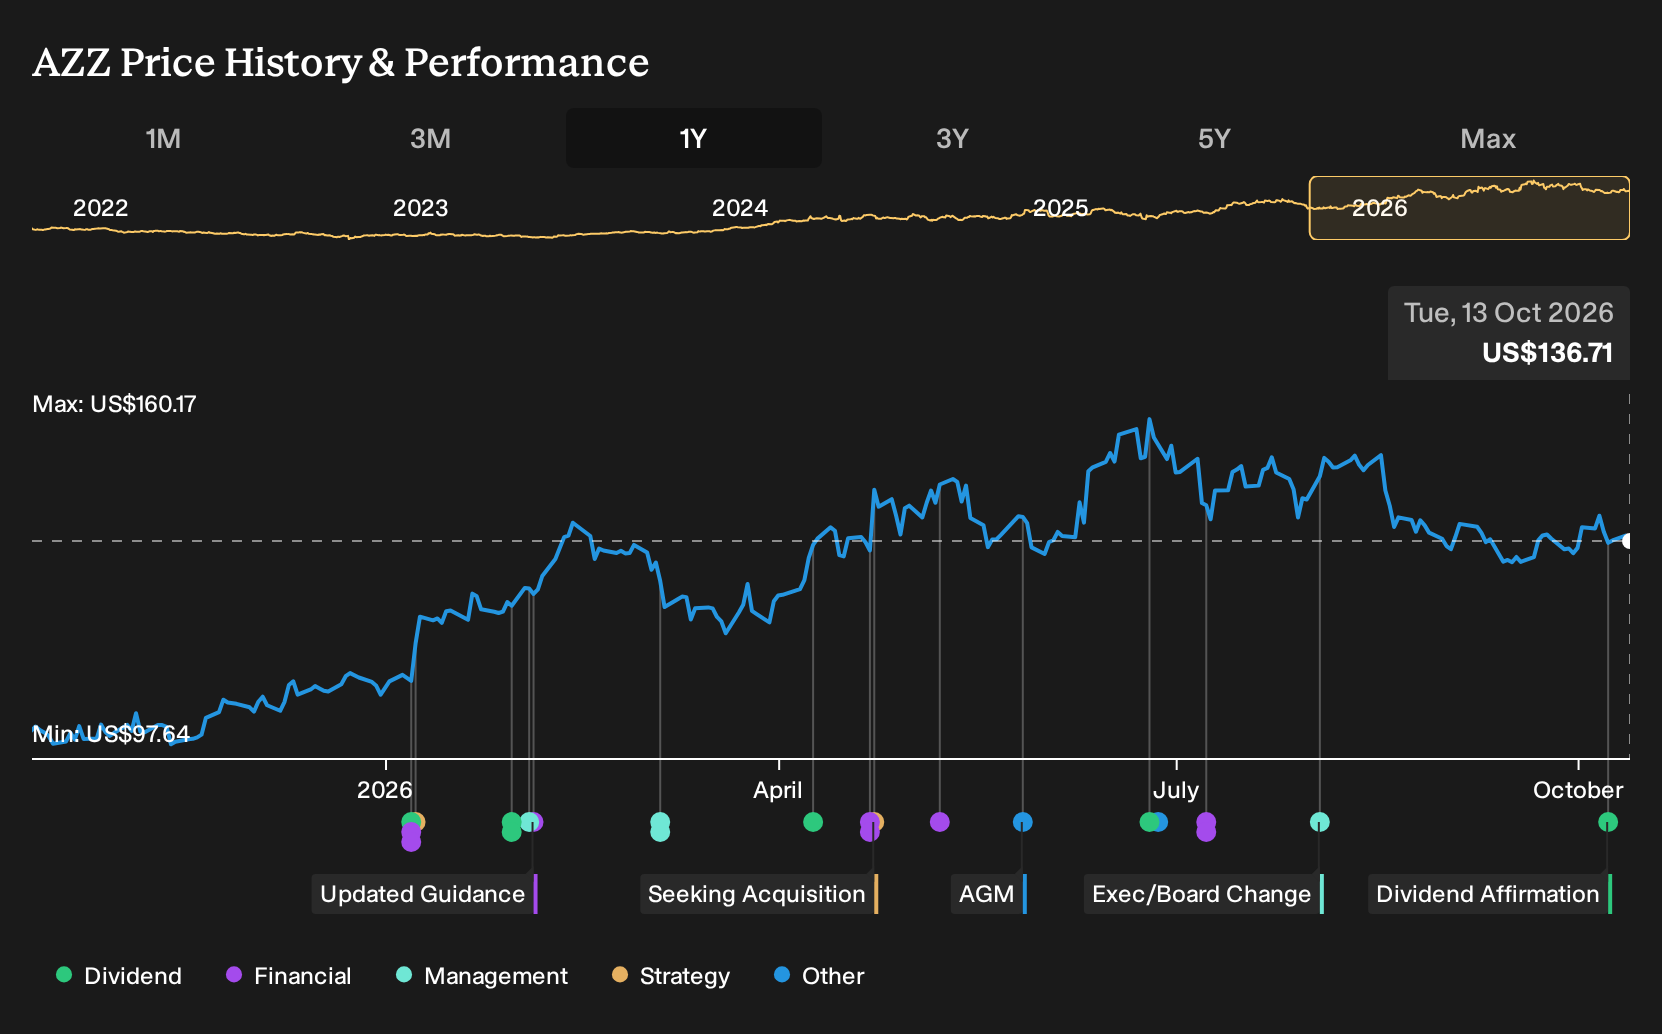
- AZZ Inc. reported record Q2 fiscal 2027 sales of US$486.9 million with strong organic demand and contribution from the Seattle Galvanizing acquisition, while net income and earnings per share from continuing operations were lower than a year earlier.
- The company paired this revenue performance with higher full year fiscal 2027 sales and earnings guidance and continued balance sheet work, including debt reduction, share repurchases, dividends and reinvestment in metal coating capacity and digital systems.
- This article examines how AZZ’s raised full year guidance reshapes the existing investment narrative built around efficiency, acquisitions and capacity.
Compare AZZ’s record-setting quarter with other metal coating and infrastructure plays by scanning our hand picked 43 power grid technology and infrastructure stocks for potential beneficiaries of similar spending trends.
AZZ Investment Narrative Recap
To own AZZ, you need to believe the metal coatings and Precoat platforms can turn higher sales into durable cash generation as new plants and digital systems ramp. The record US$486.9 million quarter and raised full year revenue outlook speak to demand and execution, even with net income and EPS lower than a year earlier.
In the near term, the key catalyst is whether capacity additions like Washington, Missouri and the Seattle Galvanizing acquisition translate into cleaner margin and earnings quality. Weather disruption, input cost swings and integration of new facilities remain the biggest operational risks, and the latest update does not remove those pressure points.
The earnings guidance revision for fiscal 2027 is the announcement that matters most here. AZZ now expects full year sales of US$1.825 billion to US$1.875 billion, slightly above the prior US$1.80 billion to US$1.85 billion range. This aligns with the strong Q2 revenue print.
That higher revenue bar makes execution on Digital Galvanizing, CoilZone and new kettles more important, because investors will be watching whether margins recover alongside the top line after the year on year decline in net income. It also keeps attention on risks from tariffs, substrate availability and any repeat of severe winter production outages.
What AZZ’s Long Term Forecasts Assume
AZZ's consensus story focuses on steady, measured expansion in the metal protection niche rather than rapid growth. Analysts who follow the stock are penciling in 6.0% annual revenue growth over the next three years, along with a modest squeeze in profit margins from 11.8% today to 11.4% by around 2029. This implies that volume and pricing gains would contribute more than further cost cutting.
The current earnings base for these projections is US$198.4 million. The same group of forecasters is looking for profits to reach US$227.8 million by about 2029 as new kettles, acquisitions and digital systems mature. That change implies an earnings increase of roughly US$29.4 million from today’s level. Analysts also expect revenues to reach around US$2.0b in that year if the growth thesis on Metal Coatings and Precoat Metals remains in place.
Under these assumptions, AZZ would be earning US$227.8 million on about US$2.0b of sales by 2029 and trading on a P/E of 27.8x, compared with 21.0x today and a current US Building industry multiple of 19.2x. This scenario requires investors to accept a smaller margin percentage than today but a larger absolute profit pool, and to be comfortable that the stock could sustain a valuation premium to the broader sector if the capacity additions and bolt-on deals proceed as planned.
AZZ's narrative outlines revenues of roughly US$2.0b and earnings of US$227.8 million by 2029, based on 6.0% yearly revenue growth and an earnings increase of about US$29.4 million from current earnings of US$198.4 million.
Uncover why AZZ's fair value indicates a 20% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternative angle focuses on AZZ’s exposure to big U.S. infrastructure and data center projects as a potential long term catalyst. Before this earnings release, the most optimistic analysts were assuming revenue of about US$1.9b and earnings of US$212.9 million by 2029. You can compare those earlier projections with today’s raised guidance and decide whether that bullish story still feels reasonable or needs a rethink.
Explore 2 other AZZ fair value estimates, including one that suggests as much as 20% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AZZ research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AZZ. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AZZ's overall financial health at a glance.
Looking For More Investment Ideas Beyond AZZ?
If the updated AZZ story has sharpened your thinking about risk, return and balance sheets, it can help to compare it with a wider set of companies using the Simply Wall St Screener.
- For investors who care about financial resilience first, focus on businesses with stronger balance sheets and cleaner fundamentals using the list of solid balance sheet and fundamentals (25 results).
- If value is your priority, scan for companies that combine quality metrics with prices that look undemanding through the 32 high quality undervalued stocks.
- For readers who want stability with income potential, filter for established businesses offering higher yields and solid coverage using the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com