
International Seaways (INSW) Stock Could Look Stretched On Earnings Today
International Seaways has seen its share price climb sharply in recent years, which puts the spotlight firmly on what investors are paying for its earnings today. With that kind of move already on the table, the key issue for anyone looking at the stock now is how well the current price lines up with the profits the business is generating.
- Over the past 5 years, International Seaways has delivered a very large share price gain, which raises the question of how much of its earnings strength may already be reflected in the valuation.
- The tanker operator’s ability to convert freight demand into consistent profits and cash flow can influence how much investors are prepared to pay for each dollar of its earnings.
- There is a second opinion on International Seaways worth weighing. See what analysts think International Seaways's shares could be worth.
The stock's next move may depend on whether International Seaways' current share price is adequately supported by its earnings power.
If you want a quick comparison point for International Seaways' recent run and what investors are paying for earnings in similar stories, scan through 32 high quality undervalued stocks.
Is International Seaways Getting Expensive on Earnings?
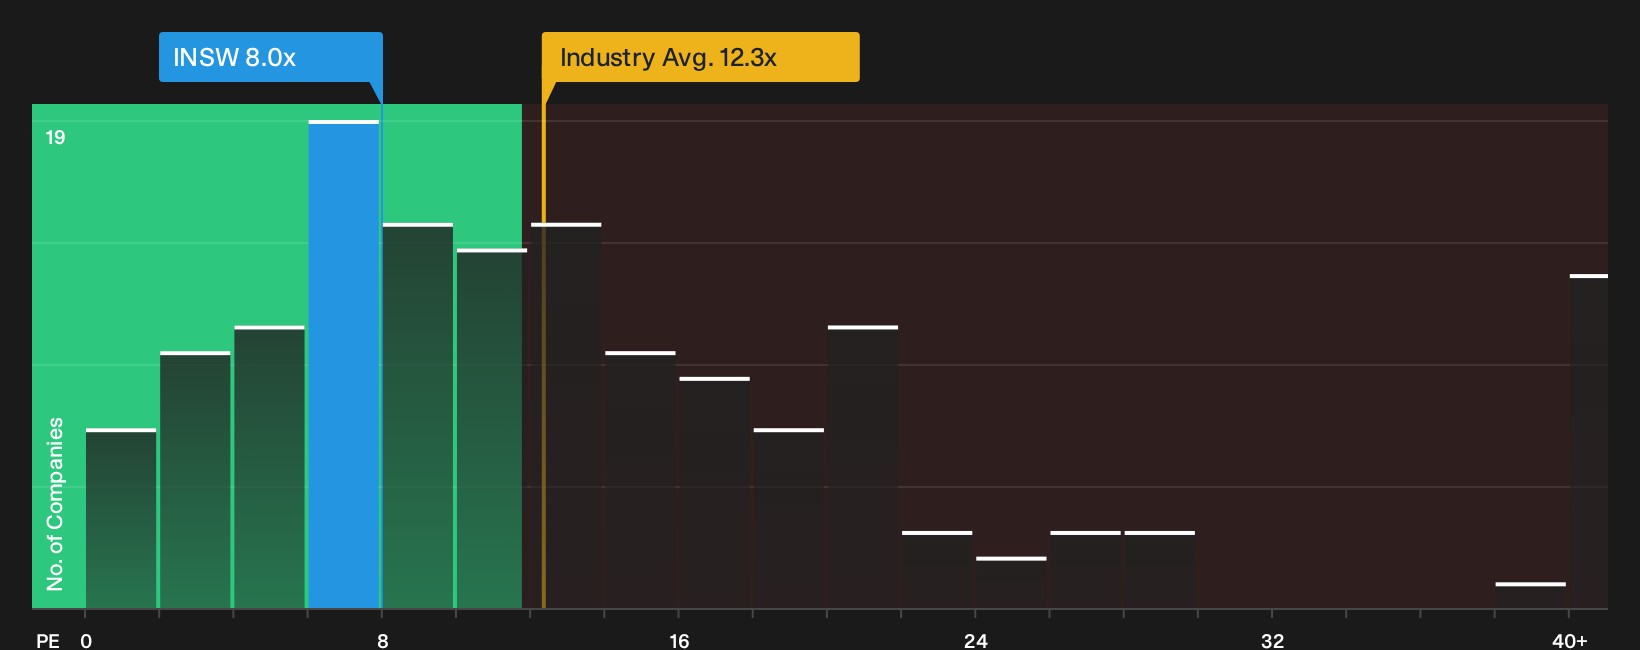
A P/E lens works well for International Seaways because freight markets swing, yet earnings still drive what investors are ultimately paying for. Right now the stock trades on a P/E of 8.0x, which is well below the broader Oil and Gas industry average of about 12.3x and also under the peer group on roughly 11.9x. That gap indicates the market is applying a lower price tag to each dollar of profit than it does to comparable tanker and energy businesses.
The fair P/E level implied by the valuation model, which factors in International Seaways' own growth profile, profitability and risk, sits above the current multiple. On this framework the shares screen overvalued, since the earnings being produced today come through at a price that is richer than the tailored fair level even though it looks cheaper than sector and peer benchmarks. For anyone weighing an entry or adding to a position, the tension between a low headline P/E and an above fair model reading is the key trade off to work through before deciding whether the current tag still makes sense. Explore the numbers behind International Seaways's P/E valuation.
The International Seaways Narrative: What Would Justify Today's Price?
Narratives on International Seaways pick up where the P/E puzzle leaves off and describe what kind of growth, profitability and earnings pattern would need to hold for the stock to appear meaningfully cheaper or richer than today’s price on Simply Wall St’s Community page. Each one treats fair value as a thesis about how the business performs over time, so you can see how the reasoning holds up as new information arrives.
On International Seaways, the bullish and bearish community views both lean on the same recent cash surge, yet they draw very different conclusions about how much is left in the story.
Bull case: roughly fairly valued
"Full ownership of Tankers International and the expansion into Suezmax and LR1 pools give International Seaways more control over commercial deployment and access to third party pool income…"
Discover why this Narrative puts International Seaways at roughly fairly valued.
Bear case: 42% overvalued
"Although International Seaways currently generates record earnings and free cash flow with a high dividend payout policy, the introduction of a new US$200 million at the market equity program after a strong share price run raises the risk that future growth and shareholder returns rely more on issuing stock than on internal cash generation…"
Explore why this Narrative puts International Seaways at 42% overvalued.
The International Seaways price is only one side of the decision
Analyst projections for International Seaways set out a different lens on what this business might look like a few years from now, which you can weigh directly against today’s earnings multiple and share price. Explore where analysts expect International Seaways to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com