
Is Cigna Group (CI) Trading At A Discount To Its Earnings?
Cigna Group has delivered a 5 year share return that looks very different from its more recent trading pattern. This puts fresh focus on whether today's US$282.53 price lines up with what the business earns. With new long term initiatives now on the table, the question is how much of that story is already reflected in the earnings investors are paying for.
- Over the past 5 years the stock is up 50.1%, which makes it important to ask whether the current valuation is still grounded in the underlying earnings power.
- Management's "Lead to One" vision and the US$3b modernization plan may support expectations for higher profitability and more scalable earnings, which can influence how much investors are willing to pay for each dollar of profit.
- The analysts covering Cigna Group have run their own numbers. See what analysts think Cigna Group's shares could be worth.
The issue now is whether Cigna Group's current share price is justified by its earnings when set against a Fair Ratio benchmark.
If you are weighing Cigna Group against other opportunities built on earnings strength, it can help to benchmark it beside 32 high quality undervalued stocks.
Is Cigna Group Still Cheap on Earnings?
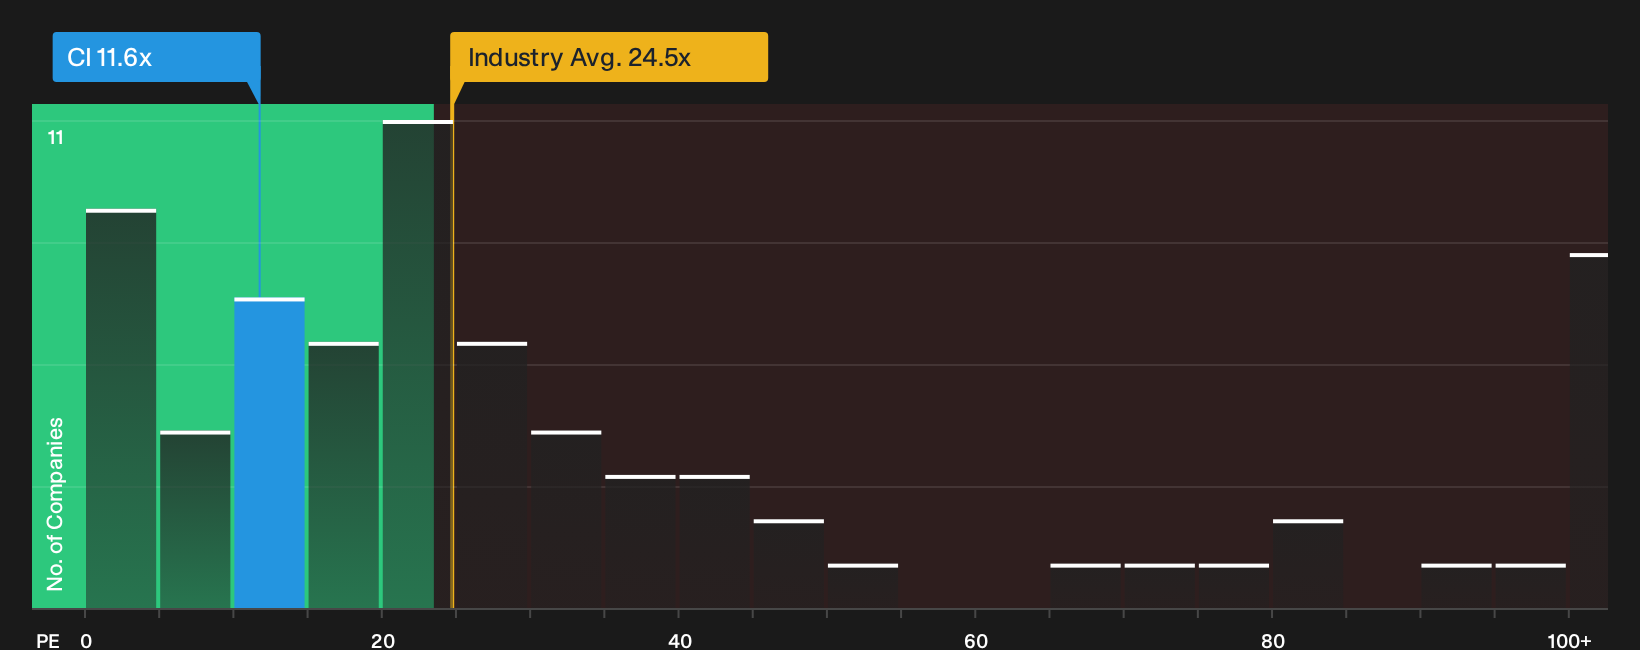
The P/E ratio fits Cigna Group well because earnings are a central yardstick for mature health insurers and health services providers. On this metric, the stock trades on roughly 11.6x trailing earnings, which is much lower than the Healthcare sector average of about 24.5x and well below the 31.2x peer group figure. For a large established operator, that is a wide gap in how the market prices each dollar of profit.
Fair Ratio modelling, which adjusts for Cigna Group's growth profile, margins, scale and risk, points to a higher P/E than where the shares trade today, so the current 11.6x screens as undervalued relative to that benchmark. Because the "Lead to One" plan and the US$3b modernization program are now public and widely discussed, this discount suggests investors are not yet paying up for those ambitions in the same way that peers are priced. That gap is what the earnings multiple leaves you to judge. Explore the numbers behind Cigna Group's P/E valuation.
The Cigna Group Narrative: What Would Justify Today's Price?
Cigna Group Narratives pick up where the valuation puzzle leaves off, by spelling out which future paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today's price on Simply Wall St's Community page. Rather than a single multiple or headline model output, each narrative lays out its own fair value assumptions so you can line them up against actual results as they arrive.
One of the top community narratives on Cigna Group: 17% undervalued
"The main requirement for this narrative is that Cigna successfully transitions clients to the Signature rebate-free PBM model while keeping specialty earnings, medical cost trends, and customer retention aligned with current expectations…"
Discover why this Narrative puts Cigna Group at 17% undervalued.
One more filter for weighing Cigna Group before you move on
Price and current earnings only tell part of the story, because professional forecasts for where Cigna Group could be a few years from now give you a different yardstick to compare with today's multiple. Explore where analysts expect Cigna Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com