
New CFO Appointment Altering The Investment Case For Mueller Water Products (MWA)?
- Mueller Water Products has announced that Michael Morgan, a finance leader with more than 30 years of experience at industrial and healthcare companies, will become Executive Vice President, Finance and then Chief Financial Officer after the filing of the 2026 Form 10-K, succeeding current CFO Melissa Rasmussen, who will stay through year end in an advisory role.
- The incoming CFO receives a one-time US$700,000 cash sign-on bonus and a US$500,000 equity award, underscoring how Mueller Water Products is tying leadership transition to long term financial stewardship and capital allocation priorities at a time when investors are focused on margins, free cash flow and foundry investment payoffs.
- This article examines how Mueller Water Products' investment narrative around margins, cash generation and capital allocation is affected by Michael Morgan's appointment.
Mueller Water Products Investment Narrative Recap
To own Mueller Water Products, you need to believe municipal repair and replacement demand, specialty valves and water management solutions can keep earnings quality intact while residential end markets stay softer. In the short term, the key swing factor is how well management turns capex heavy foundry projects and higher inventory into consistent cash conversion without straining flexibility.
The CFO transition itself looks more operational than thesis changing. Investors still face familiar risks. Hydrant backlog normalization, fading stimulus and trimmed free cash flow conversion guidance could matter more to the story than who signs the accounts, unless execution on pricing and the Mueller Operating System falters under new leadership.
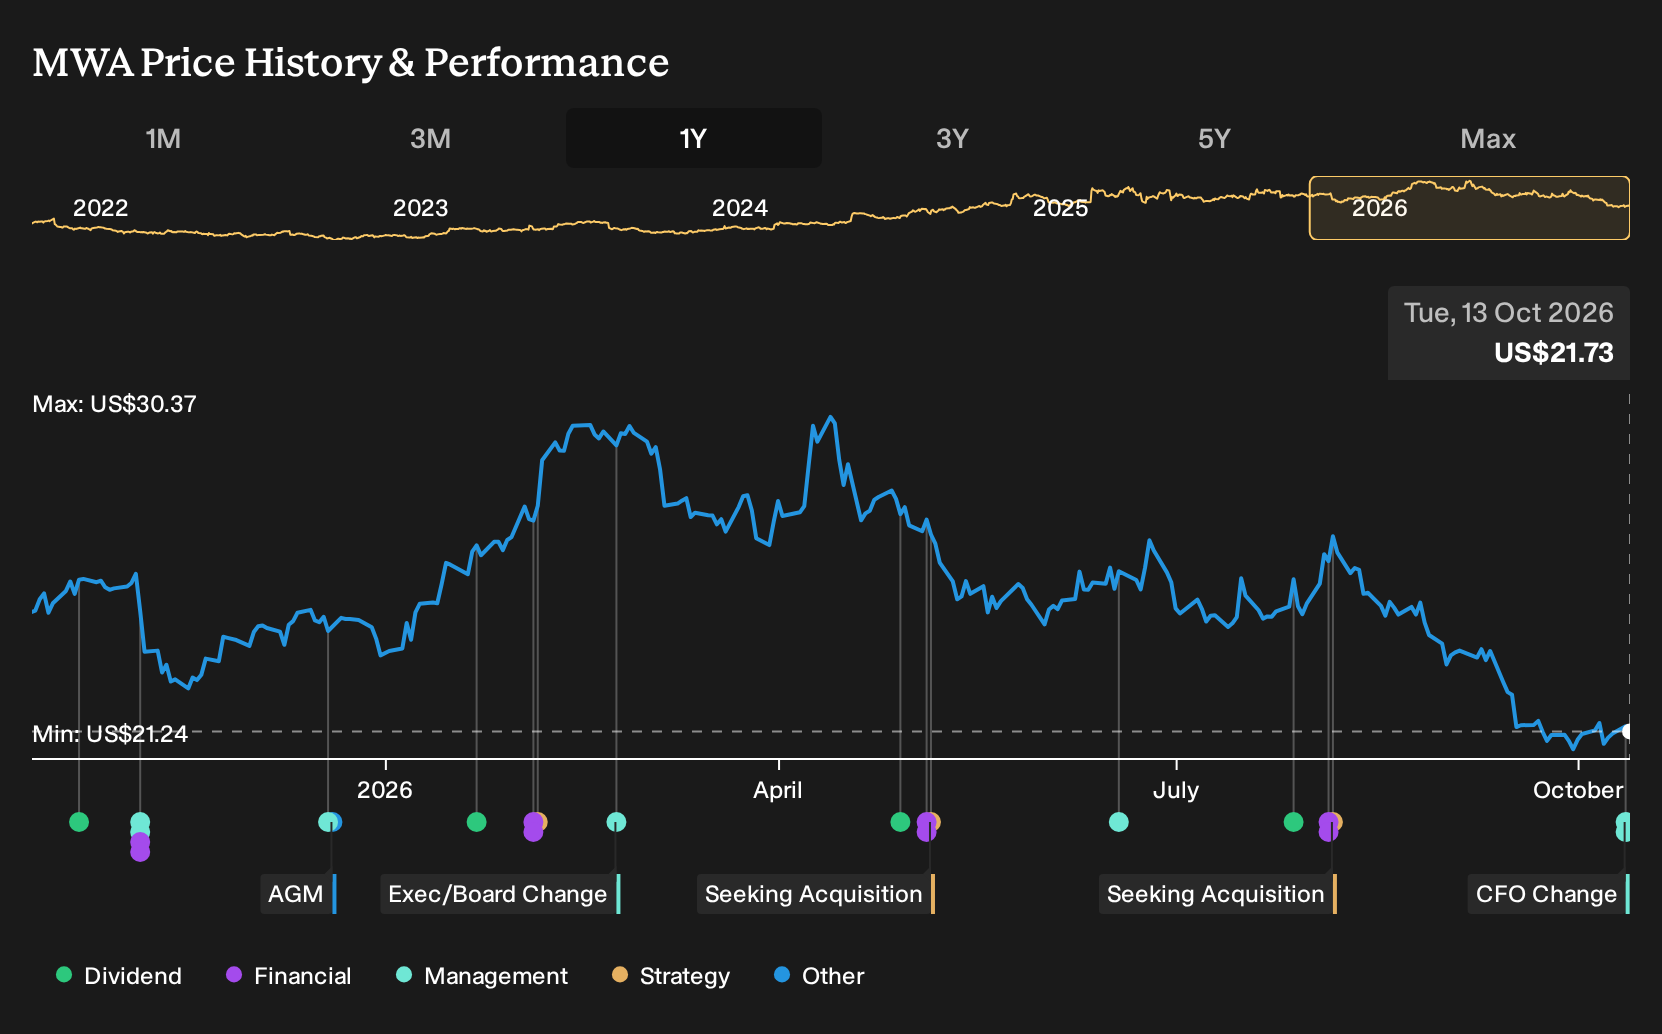
The most relevant development is Michael Morgan stepping in as Executive Vice President, Finance in October 2026, then taking the CFO role around the 2026 Form 10 K filing. His background at Indicor and Labcorp puts the financial playbook squarely on enterprise FP&A discipline, capital deployment and portfolio mix, all areas investors already watch closely here.
The main link to potential catalysts is cash and margin quality. Mueller Water Products is investing in foundries, higher value valves and digital water platforms, while free cash flow conversion guidance has been reset lower. Execution from the incoming finance chief on inventory, capex pacing and returns on these projects will shape how investors weigh those opportunities against the current risk list.
Mueller Water Products' current analyst script points to revenue of US$1.5b and earnings of US$281.5m by 2029, based on an assumed 1.5% yearly increase in revenue and an earnings increase of about US$59.3m from the US$222.2m reported today.
Uncover why Mueller Water Products' fair value indicates a 36% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle focuses on revenue risk rather than margin upside. The lowest analysts were already working off a cooler top line, with only 1.3% annual revenue growth and about US$1.5b of sales by 2029. You can read that as a far more cautious Mueller Water Products story, one that might shift again after this CFO announcement.
Explore 2 other Mueller Water Products fair value estimates, including one that suggests it could be worth just $28.67.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Mueller Water Products research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mueller Water Products. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mueller Water Products' overall financial health at a glance.
Looking for more Mueller Water Products style investment ideas?
If the Mueller Water Products story has you thinking about balance sheets, cash generation and capital discipline, use the Simply Wall St Screener to compare this situation with other companies facing similar tests.
- For investors who want resilience first and growth second, start with a 32 resilient stocks with low risk scores that already clear a strict risk filter.
- If you are hunting for quality at a reasonable entry point, scan for 32 high quality undervalued stocks that pair solid fundamentals with discounted valuations.
- When income matters as much as price appreciation, focus on 8 dividend fortresses that combine higher yields with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com