
What Jardine Matheson Southeast Asia Shares Name Change And Special Dividend Mean For Shareholders
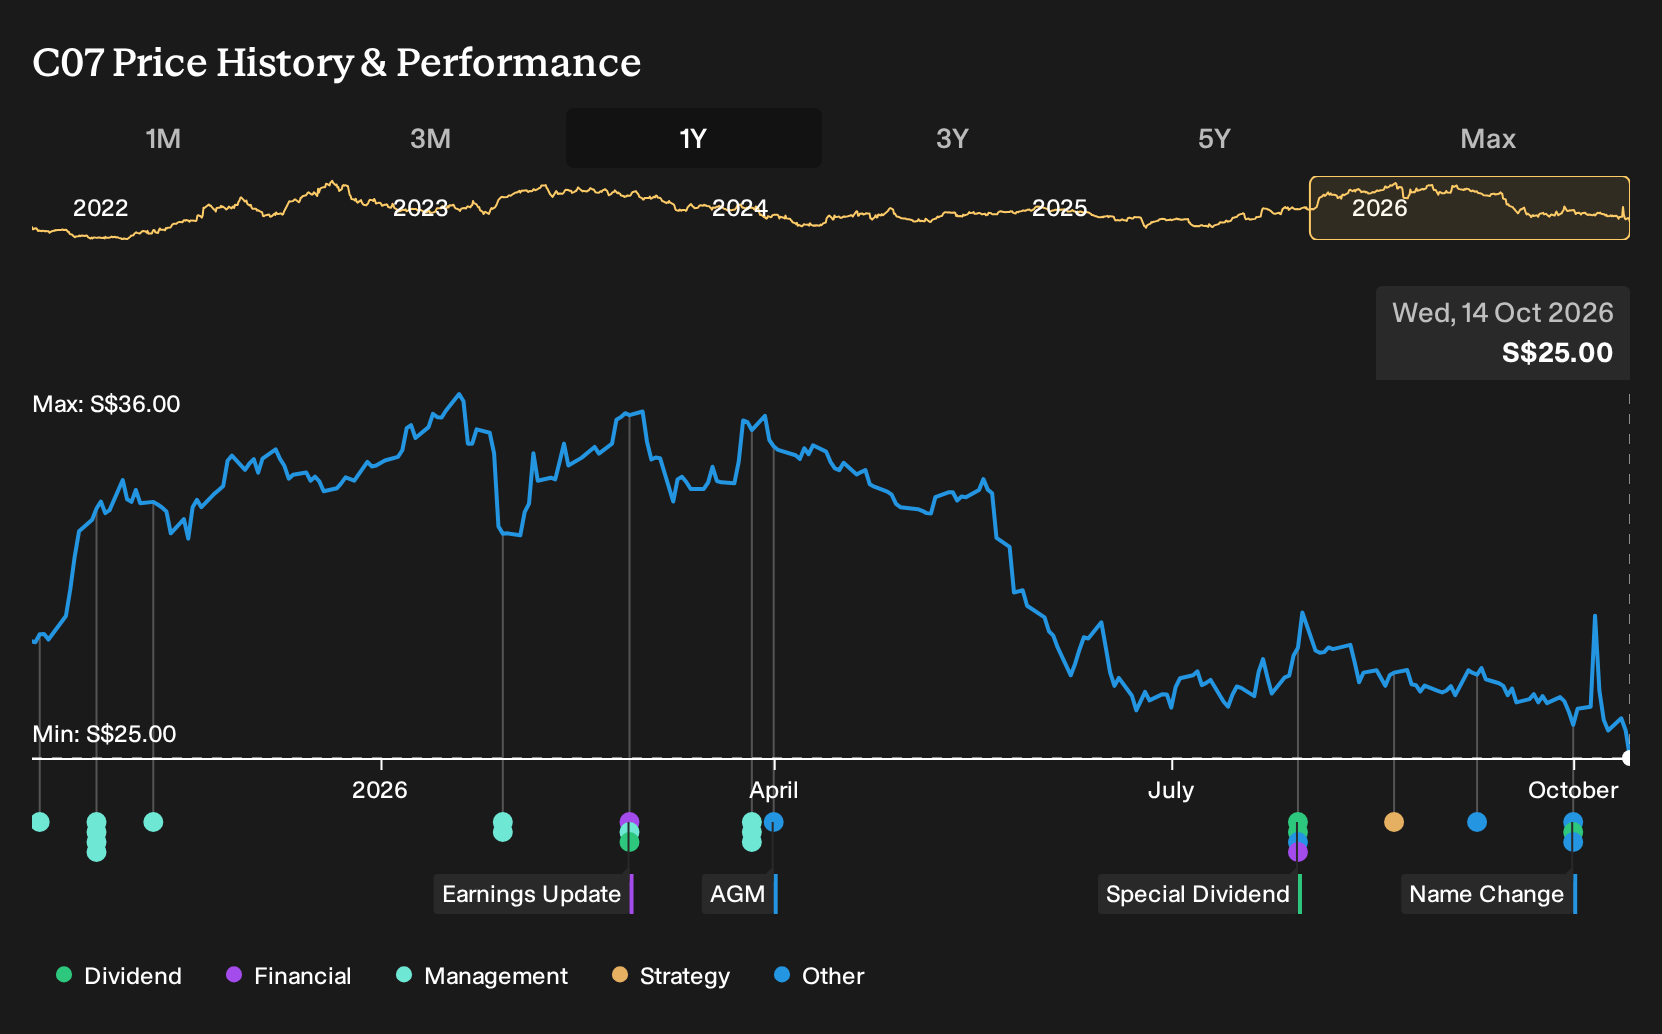
- Jardine Matheson Southeast Asia held an Extraordinary General Meeting on 1 October 2026, approving a constitutional amendment, a formal name change from Jardine Cycle & Carriage, and a one off special dividend of US$0.37 per share, with an expected record date of 9 October 2026.
- The combination of a rebrand, governance update, and cash return reflects active capital management and a refreshed corporate identity for Jardine Matheson Southeast Asia, which is relevant for how investors assess future decision making and alignment with shareholders.
- The focus now shifts to how Jardine Matheson Southeast Asia's investment narrative develops as this special dividend influences perceptions of capital priorities.
Scan how Jardine Matheson Southeast Asia's special dividend move compares with other potential value opportunities by reviewing our curated list of 187 high quality undervalued stocks.
What Is Jardine Matheson Southeast Asia's Investment Narrative?
To own Jardine Matheson Southeast Asia, you need to be comfortable with a diversified, capital intensive group that leans heavily on Indonesia through Astra and ties its fortunes to demand for autos, heavy equipment, mining, agribusiness, toll roads and finance. Earnings have grown 8.3% per year over 5 years and net profit margins are higher than last year, yet revenue has recently declined 3.4%, so execution on pricing, mix and cost control matters more than raw volume growth.
The one off US$0.37 special dividend and governance refresh signal active capital allocation rather than a shift in day to day operations. Near term catalysts still sit in auto demand, commodity linked activity and the health of its financing arm. With the stock down 26.4% year to date but trading on a 7.8x P/E and at a large discount to one cash flow based value estimate, the bigger question is whether management keeps prioritising disciplined reinvestment over sporadic cash returns.
Yet there is a less obvious pressure point inside Jardine Matheson Southeast Asia's story that turns on...
There's only one way to know the right time to buy, sell or hold Jardine Matheson Southeast Asia. Head to Simply Wall St's company report for the latest analysis of Jardine Matheson Southeast Asia's Fair Value.
Exploring Other Perspectives
One alternate view puts debt risk at the centre of the Jardine Matheson Southeast Asia story. The most cautious analysts were already baking in revenue declines of about 6.4% a year and earnings of roughly US$1.2b by 2029, yet still pencilling in a lower 7.5x P/E. With the governance changes and special dividend now approved, those assumptions may shift. Treat this as one of several narratives to test against your own expectations.
Explore 3 other Jardine Matheson Southeast Asia fair value estimates, including one that suggests as much as 6% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Jardine Matheson Southeast Asia research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Jardine Matheson Southeast Asia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jardine Matheson Southeast Asia's overall financial health at a glance.
Looking For More Investment Ideas Beyond Jardine Matheson Southeast Asia?
Once you have a view on Jardine Matheson Southeast Asia, it can help to widen the lens and compare it with other opportunities that match your risk tolerance, income needs, or focus on balance sheet strength. The Simply Wall St Screener lets you filter for very specific traits so you can build a watchlist that fits the way you like to invest.
- For investors hunting for strong businesses that appear mispriced, start with a curated group of 187 high quality undervalued stocks that combine quality fundamentals with potentially attractive entry points.
- If reliable income matters more to you than share price swings, look at companies in our set of 217 dividend fortresses that focus on higher yield alongside business resilience.
- For a focus on financial strength and staying power, filter for companies in the list of solid balance sheet and fundamentals (202 results) to see which ones pair robust balance sheets with solid underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com