
3 Tech Stocks Investors Are Watching as Interest Rates Start to Fall
Interest rates are finally edging lower in many countries while inflation still lingers, a mix that can reward some fast growing tech stocks and punish others that rely heavily on cheap money. That push and pull creates an opening for investors who can spot which growth stories look better positioned for this new rate cycle. This article walks through three large cap tech stocks from our screener that appear positively exposed to the latest macro shift.
The three stocks highlighted below are only a sample from this rate-sensitive tech theme, and the full screen surfaced 38 more large cap growth and tech companies with similarly interesting stories that are not covered here. To identify and analyze those additional ideas directly, head straight into the Global rate-sensitive growth and tech equities screener.
Macronix International (TWSE:2337)
Overview: Macronix International designs and supplies NOR and NAND flash memory, ROM, and security focused chips for global electronics markets.
Operations: The business generates NT$45,536.66 million from memory products and wafer fabrication, reflecting a heavy focus on core semiconductor manufacturing.
Market Cap: NT$217.73b
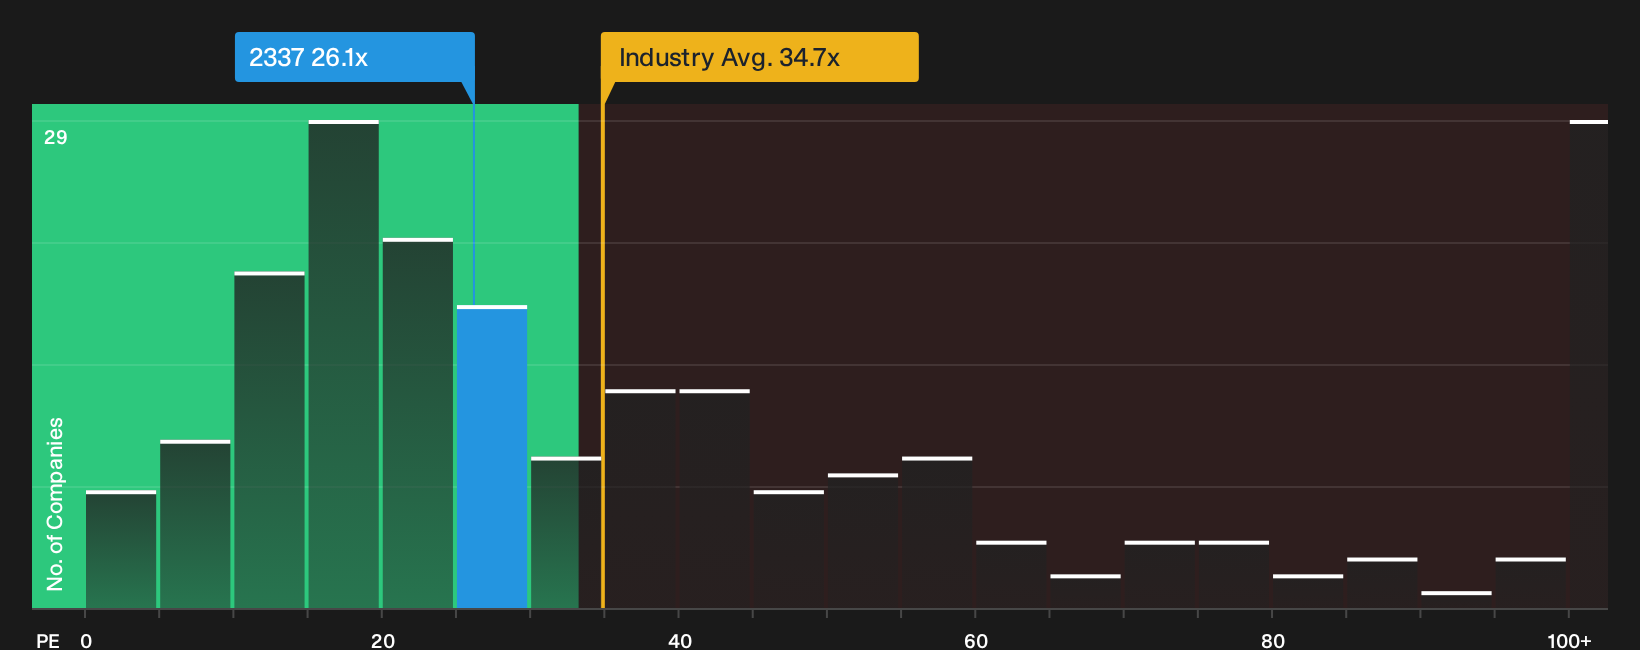
Macronix International fits this rate sensitive tech screen as a large cap memory producer with forecast earnings growth of 77.91% and revenue growth of 47.2%. It is trading on a 26.1x P/E compared with a Taiwan semiconductor average of 34.7x, and its outlook remains closely tied to how one powerful, capital intensive cycle shapes pricing power and cash returns.
That kind of cycle leverage makes it worth seeing the full 4 key rewards and 1 important major warning sign to judge whether the current multiple really captures the risk and upside.
HubSpot (HUBS)
Overview: HubSpot runs a cloud-based CRM suite that helps mid-market businesses manage marketing, sales, service, content, operations, commerce, and AI-assisted workflows.
Operations: The business generates about US$3.45b from internet software and services, with an additional US$281 million reported from Asia Pacific customers.
Market Cap: US$11.14b
Where interest rates set the tone for growth-focused software, HubSpot offers recurring, cloud-based CRM and AI tools. This aligns with the type of rate-sensitive beneficiaries that this screener targets when financing costs ease.
"AI augmentation: HubSpot’s Breeze AI can boost product stickiness by improving productivity for marketers and sellers; successful differentiated AI features would preserve ARPU and reduce commoditization risk."
What happens to HubSpot’s margin potential if a single assumption about how customers pay for these tools eventually shifts?
That payment shift question sits right at the center of the full narrative for HubSpot, where HubSpot’s AI pricing power, unit economics, and rate sensitivity all get pulled apart.

Amlogic (Shanghai)Ltd (SHSE:688099)
Overview: Amlogic (Shanghai) Ltd designs and sells system on a chip and related semiconductors that power smart home, AIoT, display and in-car devices.
Operations: The business generates about CN¥7.9b from research, production and sales of semiconductor integrated circuit chips across its SoC and peripheral portfolio.
Market Cap: CN¥39.3b
Amlogic (Shanghai) Ltd fits this rate-sensitive tech screen as a pure-play fabless semiconductor designer with earnings linked to global electronics and AI device spending. Forecast earnings growth of about 30.6% a year on a P/E of 39.8x, below domestic chip peers and industry averages, gives the stock significant exposure to changes in interest rates, depending on how one unseen pressure plays out around cash earnings quality.
That unseen earnings pressure is the crux, and the full 4 key rewards and 1 important major warning sign shows whether Amlogic (Shanghai) Ltd’s growth story is quietly compounding or already priced in.

Seeking Alternatives Before The Crowd?
Fresh screens keep breaking out while older ideas lose momentum and get caught by the crowd. Scan new themes that are still under the radar and review them early.
- Look for cash rich businesses that appear able to fund their own expansion by running a tight balance sheet with a curated list of solid balance sheet and fundamentals (203 results).
- Explore the potential for price momentum in high quality miners by scanning a hand picked pool of 35 elite gold producer stocks before attention shifts to other segments of the market.
- Focus on structural demand for critical metals by reviewing a focused basket of 16 top copper producer stocks that screens for both production scale and financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com