
Brookfield (TSX:BN) Stock May Look Rich Following Fresh AI Infrastructure Commentary
Brookfield has delivered a strong 77.0% share price gain over the past three years, yet the stock is currently trading well below its recent highs after a weaker run this year. This puts fresh focus on whether its earnings profile still lines up with what the market is paying today. With the share price last closing at C$52.15, long term holders and new buyers alike are asking if that tag is adequately grounded in the profits the business generates.
- The 77.0% rise over three years has created substantial value for longer term investors, so it now matters whether that performance is supported by the earnings power of Brookfield's underlying investments.
- Recent commentary from investor Bill Ackman highlighting Brookfield's role in physical infrastructure that may benefit from artificial intelligence projects can influence how much earnings durability and growth investors are prepared to factor into the current valuation.
- There is a second opinion on Brookfield worth weighing. See what analysts think Brookfield's shares could be worth.
For investors, the debate is whether Brookfield's current share price is appropriately aligned with its earnings compared with the industry average.
If you want a wider set of ideas that link earnings power with what the market is paying, a focused stock screen is a useful second step after Brookfield. You can begin with 7 high quality undervalued stocks.
Does Brookfield Look Pricey on Earnings?
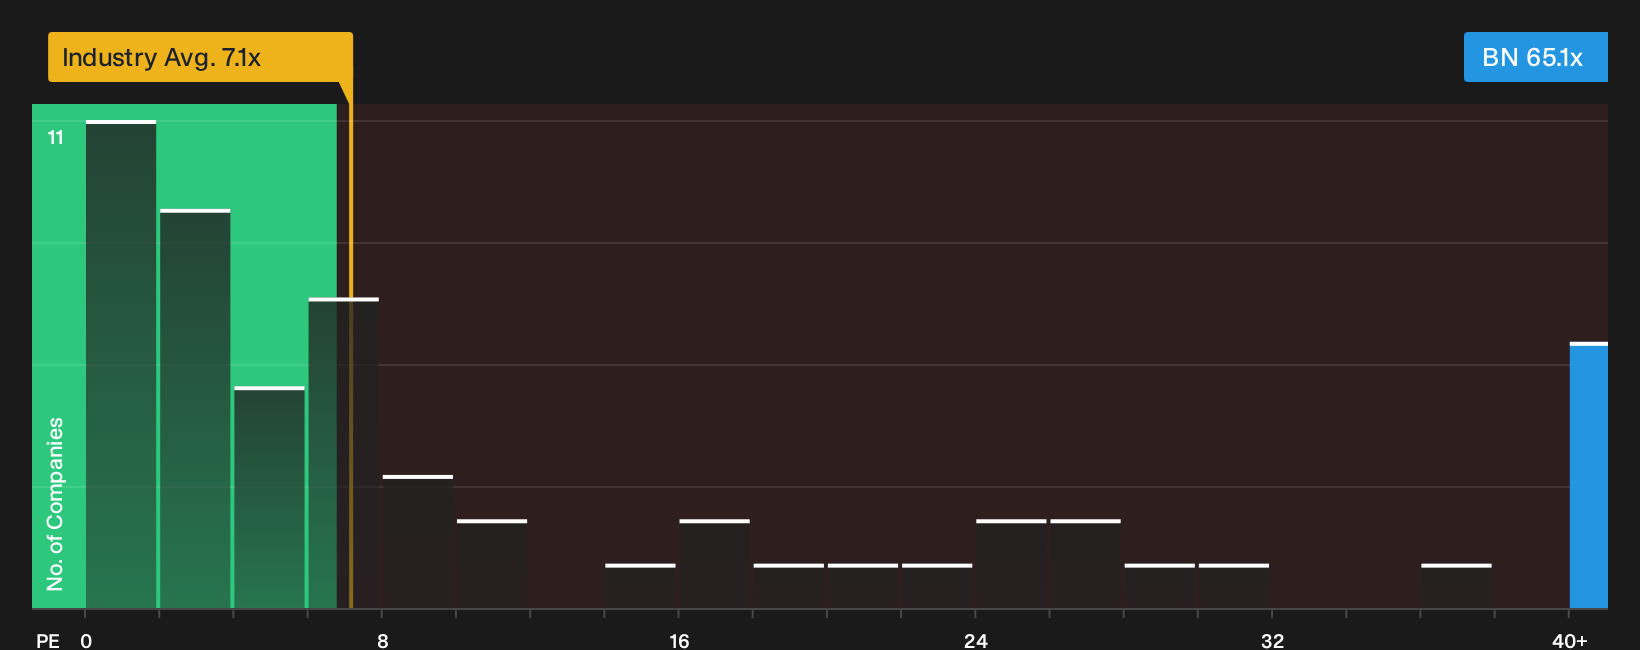
P/E has traction for Brookfield because investors watch reported earnings closely for a capital markets group of this size. On this yardstick the stock trades on about 65.1x earnings, which is far above both the broader capital markets industry average of roughly 7.1x and the peer average of about 16.2x. That kind of gap signals that buyers are willing to pay a heavy premium for each dollar of Brookfield’s current profit.
Bill Ackman’s recent comments flagging Brookfield as a potential beneficiary of artificial intelligence infrastructure help explain why sentiment can support such a rich multiple. Yet even with that context the shares screen as overvalued against sector norms. The valuation model here heavily penalises Brookfield’s patchy free cash flow record, so the extreme gap on P/E looks less like a fine tuning issue and more like a warning that the stock is very expensive on this framework. That puts the burden on investors to judge whether Brookfield’s asset mix, fee streams and balance sheet quality make that premium worthwhile in their own portfolios. Explore the numbers behind Brookfield's P/E valuation.
The Brookfield Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Brookfield valuation puzzle leaves off and explain which future paths for growth, margins and earnings would need to occur for the stock to be worth materially more or materially less than today’s price. Each narrative on Brookfield sits on the Community page and turns fair value into a clear, testable view of the business that you can track as the story develops over time.
One of the top community narratives on Brookfield: 36% undervalued
"The return comes from compounding earnings, any narrowing of the discount is the accelerant, not the engine..."
Discover why this Narrative puts Brookfield at 36% undervalued.
One more Brookfield check that belongs beside the P/E story
Price and earnings only tell part of Brookfield's picture, because the research flags specific risk checks that could change how you weigh everything you have just read. Take a closer look at 2 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com