
Learn Why The Bull Case For Bank OZK (OZK) Could Change Following Dividend Increase
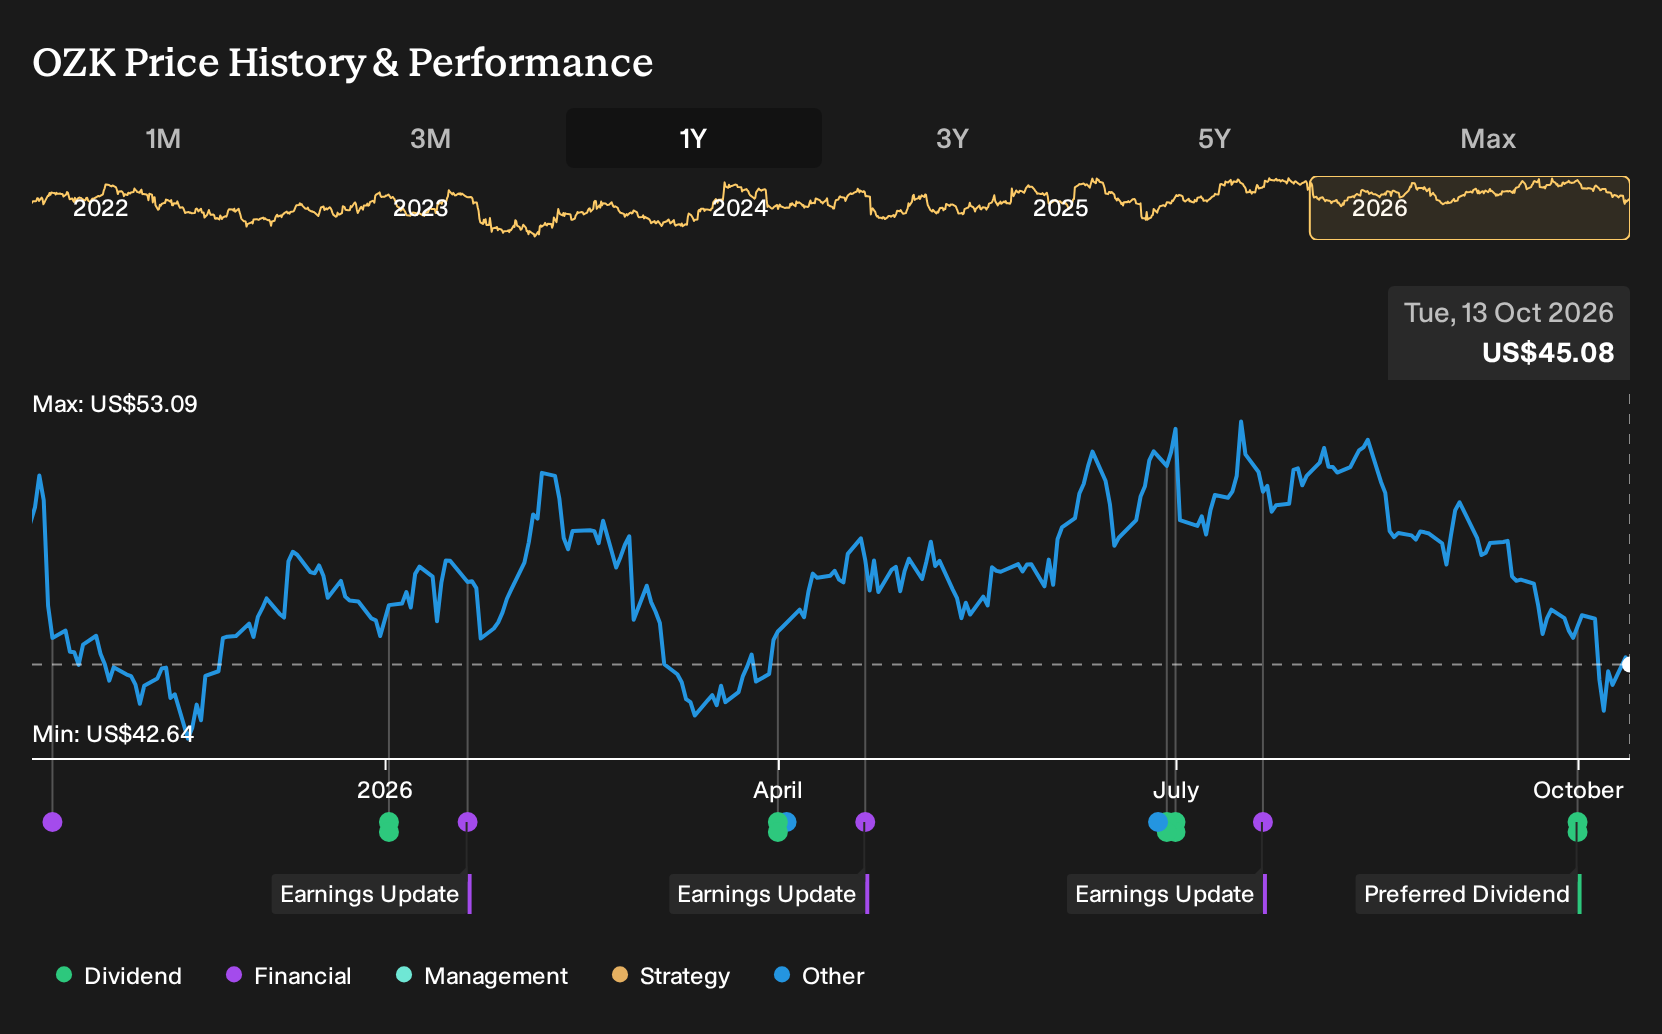
- Bank OZK declared a quarterly cash dividend of $0.49 per common share and $0.28906 per Series A preferred share, with record dates in October and November 2026 and payments scheduled later that month.
- The 65th consecutive quarterly common dividend increase highlights Bank OZK's ongoing focus on capital return as it prepares to report new quarterly earnings.
- This article examines how Bank OZK's long dividend increase streak and latest payout decision fit within its broader investment narrative.
Scan beyond Bank OZK and explore additional income ideas in our hand picked list of 8 dividend fortresses for investors who want yield with staying power.
Bank OZK Investment Narrative Recap
To own Bank OZK, you need to be comfortable with a real estate heavy lender that is actively trying to rebalance toward more diversified Corporate and Institutional Banking and fee income. The key near term swing factor is how quickly that shift offsets slower Real Estate Specialties Group growth and cautious guidance around net interest income.
The biggest current risk is that elevated commercial real estate repayments and concentrated office and life science credit issues persist, which could pressure earning assets, net interest margin and provisions. The fresh dividend news does not materially change that equation. It mainly reinforces that management still sees capital levels as supportive of ongoing payouts.
The most relevant announcement in that context is the latest quarterly common dividend of US$0.49 per share, the 65th consecutive increase. A rising ordinary payout, alongside a separate Series A preferred dividend at 4.625%, indicates that Bank OZK is still committing cash to income focused holders while managing regulatory capital needs.
For you as a shareholder, the link back to catalysts is straightforward. If Sun Belt expansion, Corporate and Institutional Banking buildout and fee businesses keep gaining traction, sustaining or gradually lifting dividends can remain part of the story. If RESG credit stress or repayment levels worsen from here, that same capital return profile could face pressure.
What The Current Forecasts Assume For Bank OZK
Analysts are effectively tying Bank OZK's richer dividend stream to a set of concrete operating assumptions that stretch out to 2029. The story is simple on the surface. Forecasts lean on steady revenue expansion, some profit margin giveback and only a modest step up in earnings over the next few years.
On the top line, the current consensus pencils in revenue growth of 9.5% a year over the next 3 years. That pace sits against a backdrop of Sun Belt oriented lending and fee businesses that need to keep pulling their weight even as Real Estate Specialties Group volumes adjust. For income focused investors, the key link is that this revenue path is the engine analysts are counting on to support dividend checks alongside any buybacks.
Profitability assumptions are less generous. Margins are expected to move from 43.5% today to 33.8% in roughly 3 years. That kind of step down suggests analysts are building in some pressure from funding costs, mix shift away from higher yielding construction loans, or extra credit and operating expenses. It also means the model does not require aggressive margin expansion to make the math work on dividends, which may appeal if you prefer a more cautious base case.
On earnings, the consensus pins current profits at US$675.1 million and looks for US$690.2 million by around October 2029. That is an increase of about US$15 million over the period. For a shareholder, that is hardly a breakaway jump. It points to a thesis that mixes moderate earnings progress with support from a shrinking share count and ongoing cash returns rather than a pure growth sprint.
Those per share dynamics matter if you own Bank OZK for income and capital return together. Analysts expect the share count to decline by roughly 2.54% per year over the next 3 years. Buybacks at that level can lift earnings per share and potentially make a flat to slightly rising earnings pool feel more powerful on a per share basis, which ties back into the case for sustaining dividends.
Valuation assumptions round out the picture. Forecasts use a discount rate of 7.24% in the Simply Wall St workup and a P/E of 9.7x on the 2029 earnings estimates, compared with a current multiple of 7.0x and an 11.4x P/E for the broader US Banks industry. For you, that gap frames how much rerating room the analysts think exists if Bank OZK hits its revenue, earnings and diversification goals while keeping its dividend streak intact.
Bank OZK's narrative projects US$2.0b revenue and US$690.2 million earnings by 2029. This setup assumes 9.5% yearly revenue growth and an earnings increase of about US$15 million from US$675.1 million today.
Uncover why Bank OZK's fair value indicates a 19% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Not every analyst sees Bank OZK’s dividend streak as the anchor of the story. The most cautious voices focus on RESG repayments staying high, which they think could cap revenue even after this dividend move. Before the news, the lowest forecasts still had revenue reaching about US$2.0b and earnings near US$682.6 million by 2029. That gap with consensus shows how far opinions can stretch. Consider using this range of views to compare several viewpoints before deciding how this dividend fits your own thesis.
Explore 3 other Bank OZK fair value estimates, including one that suggests as much as 11% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bank OZK research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Bank OZK. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank OZK's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bank OZK?
You do not need to stop with Bank OZK. If you want to stress test your income or total return plan, it can help to line this story up against a wider mix of high conviction watchlist candidates.
The Simply Wall St Screener lets you scan for opportunities that match your own risk, income and quality preferences. Here are a few angles you might want to run with next.
- If you want potential upside with a margin of safety focus, start by scanning our 32 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect them.
- For investors who put balance sheet strength first, filter for a list of solid balance sheet and fundamentals (25 results) where financial resilience and funding flexibility are central to the story.
- If you enjoy finding stories before they are widely followed, look through our 20 high quality undiscovered gems that pair solid metrics with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com