
Insmed (INSM) Stock Looks About Right Following Raised 2026 Revenue Guidance
Insmed has seen sharp swings in recent months, yet over the past few years the share price has moved a long way from where it started. This naturally raises a basic question for investors about whether today’s valuation lines up with its sales. With new respiratory therapies progressing and fresh data on the way, the market is constantly updating its expectations, but the underlying revenue base is easier to measure than the mood around the stock.
- Over the last 3 years, Insmed has delivered a very large share price gain of 276.6%, which puts a lot of weight on whether its current sales can carry that step up in value.
- Recent updates around Brensocatib revenue and higher future revenue expectations, along with ongoing work on drugs like TPIP, may support a view that the company’s top line could play a bigger role in justifying what investors are paying today.
- Your read on Insmed is one view; the desks covering it have another. See what analysts think Insmed's shares could be worth.
The stock’s next move may depend on whether Insmed’s present share price is adequately supported by the revenue it is currently generating and what that implies for a sales based valuation multiple.
For context on how other businesses with different balance sheet profiles look when you filter by clear rules rather than headlines, you can also scan solid balance sheet and fundamentals stocks screener (25 results).
Where Does Insmed Sit on Sales?
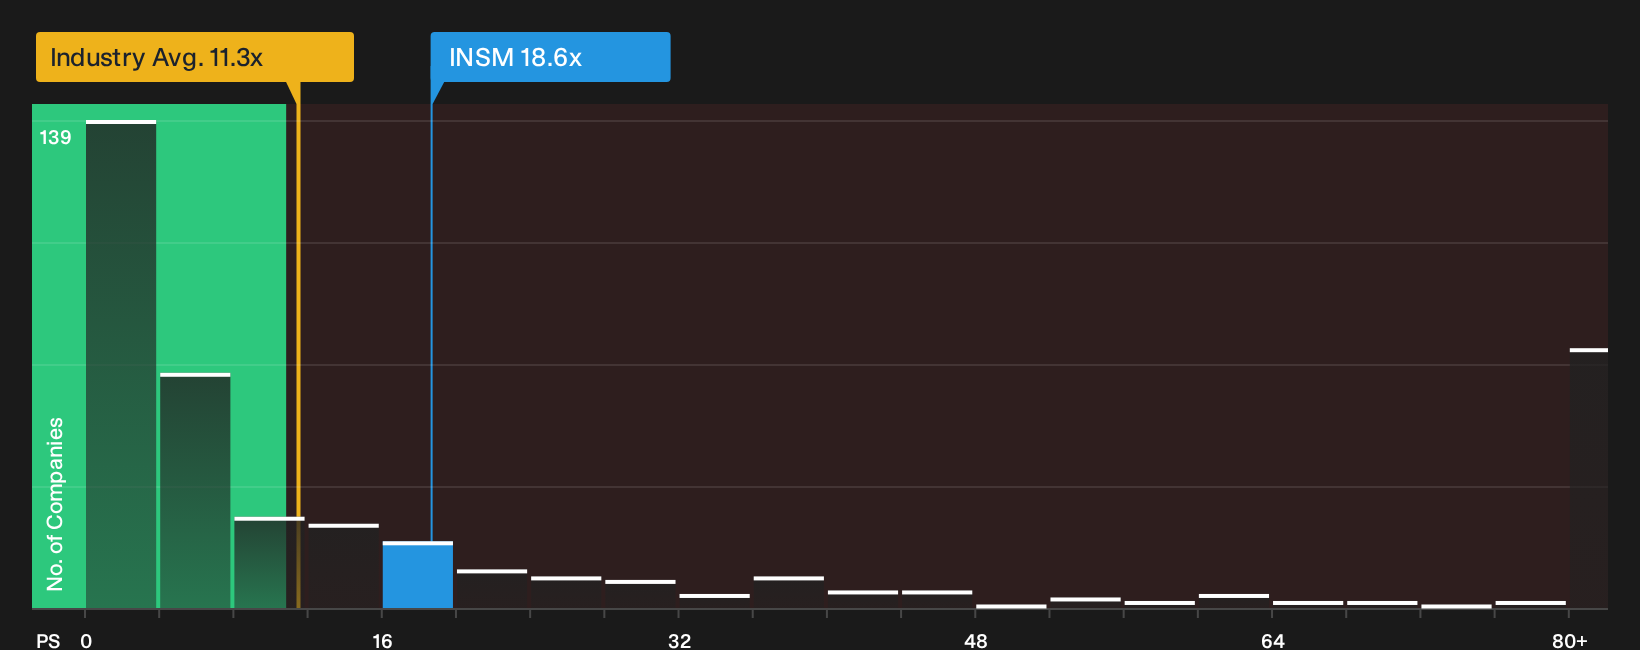
The P/S ratio is a useful lens for Insmed because the business is still investing heavily and reported free cash flow is not yet a steady anchor. On this measure, the stock trades at a P/S of 18.6x, which is higher than both the wider biotech industry average of 11.3x and the peer group on 7.2x. The market is clearly assigning a premium valuation to each dollar of Insmed’s revenue relative to many respiratory therapy and biotech comparables.
Because the model based fair P/S multiple points to the level you might expect once growth, margins, market size and risk are weighed together, Insmed’s current 18.6x sits slightly above that reference point rather than far away from it. The raised 2026 Brensocatib revenue guidance helps explain why investors are still prepared to pay a relatively full P/S multiple despite sector benchmarks sitting lower. Explore the numbers behind Insmed's P/S valuation.
The Insmed Narrative: What Would Justify Today's Price?
Narratives pick up where the P/S puzzle leaves off for Insmed. They explain which paths for growth, profitability and earnings would need to occur for the stock to appear meaningfully cheaper or more expensive than it does today. Each scenario links its figures to a clear view on how Insmed's future scale, margins and risks might change, providing something concrete to revisit as new information becomes available.
One of the top community narratives on Insmed: 51% undervalued
"The anticipated U.S. launch of brensocatib in bronchiectasis in the third quarter of 2025 is a major catalyst, expected to significantly increase revenue..."
Discover why this Narrative puts Insmed at 51% undervalued.
One more decision point on Insmed that valuation alone does not answer
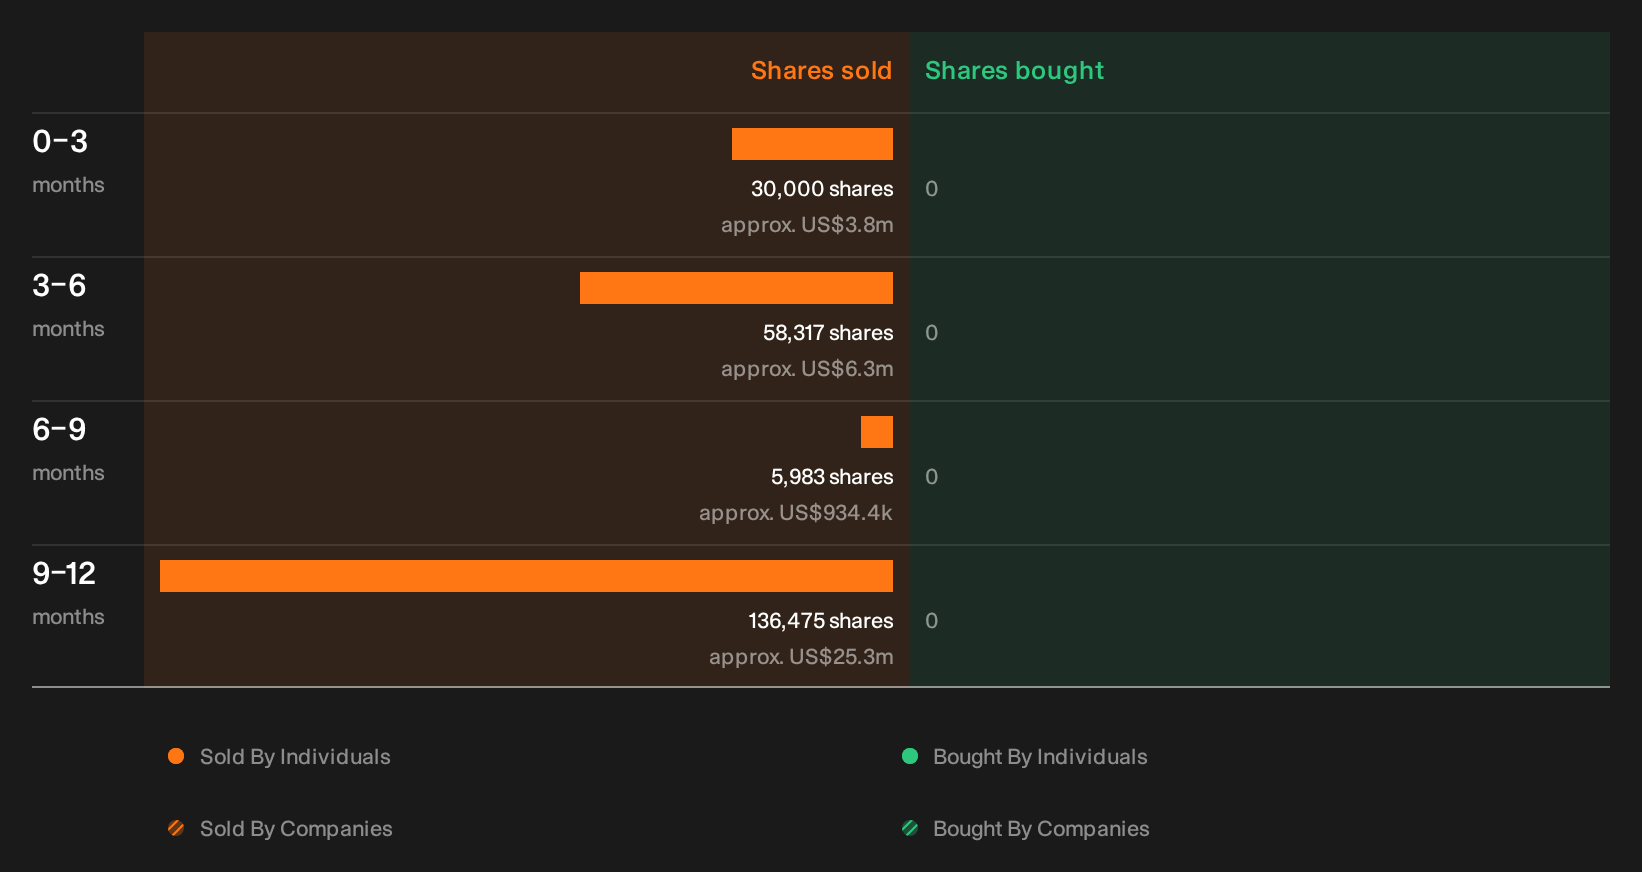
Price to sales, growth stories and sector comparisons only tell part of the story for Insmed, because recent transactions by people inside the business raise a separate question that readers may want to inspect closely. See the recent insider selling flagged for Insmed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com