
Is Alphabet (GOOGL) Undervalued After Its Unity AI Platform Deal?
Alphabet (GOOGL) is back in focus after Google and Unity announced a new AI powered game creation platform, raising fresh questions about how cloud services, AI tools, and content ecosystems contribute to the stock’s long term story.
The Unity announcement comes after a busy run for Alphabet, with fresh AI model releases, major clean energy and data center power deals, and new ETF and single stock product launches pulling the stock back into the spotlight. Despite a recent 90-day share price return that is down 4.62% and some legal noise around Gemini timelines, the share price is up 12.26% year to date. The 1-year total shareholder return of 44.51%, alongside a 3-year total shareholder return of 155.62% and a 5-year total shareholder return of 149.34%, points to momentum that investors are still treating as very much intact.
Scan beyond Alphabet and explore how other AI heavyweights and under the radar compounders are positioned in our curated list of 32 high quality undervalued stocks.
Alphabet’s AI deals, legal overhangs, and Berkshire interest now all sit inside a US$4.29b market value and a 44.51% 1-year total return. Is most of the upside already banked, or is valuation still leaving meaningful headroom?
Most Popular Narrative: 74.6% Overvalued
Alphabet closed at $353.78 while the most followed narrative on the stock pins fair value closer to $202.62, so the story centers on whether investors are paying far ahead of that estimate today.
What makes it hard is not the rate. It is the size. Growing revenue at nearly seventeen percent a year for eleven years from a base above $400 billion is without precedent at this scale, because at some point you run out of world.
Then I ran a second test, and this is the one that settled it for me. Suppose the returns on all that new spending were not thirteen percent but marvellous beyond any reasonable hope. Suppose they were infinite. On the same revenue path, the shares still come to $257.39, which is about twenty eight percent below the market price. That result is precise and it is useful. Today's price is not a bet on better returns. It is a bet on a substantially bigger company.
See why 257 investors see Alphabet as 75% overvalued.
Result: Fair Value of $202.62 (OVERVALUED)
Still, a faster than expected drop in search advertising or tougher remedies from ongoing antitrust cases could quickly challenge this overvaluation story.
Find out about the key risks to this Alphabet narrative.
Another View: Alphabet Through The SWS DCF Lens
The narrative crowd sees Alphabet as heavily overvalued, yet the SWS DCF model tells a very different story. On that cash flow view, the stock at $353.78 sits below an estimated value of $509.08. This suggests the market is pricing in more caution than the model.
For anyone weighing which story to trust, the gap between narrative fair value and our cash flow work raises a simple question. Is the crowd underestimating how much cash Alphabet can generate, or is the model giving too much credit to those future dollars, given earnings are forecast to edge down 0.2% a year over the next 3 years?
Look into how the SWS DCF model arrives at its fair value.
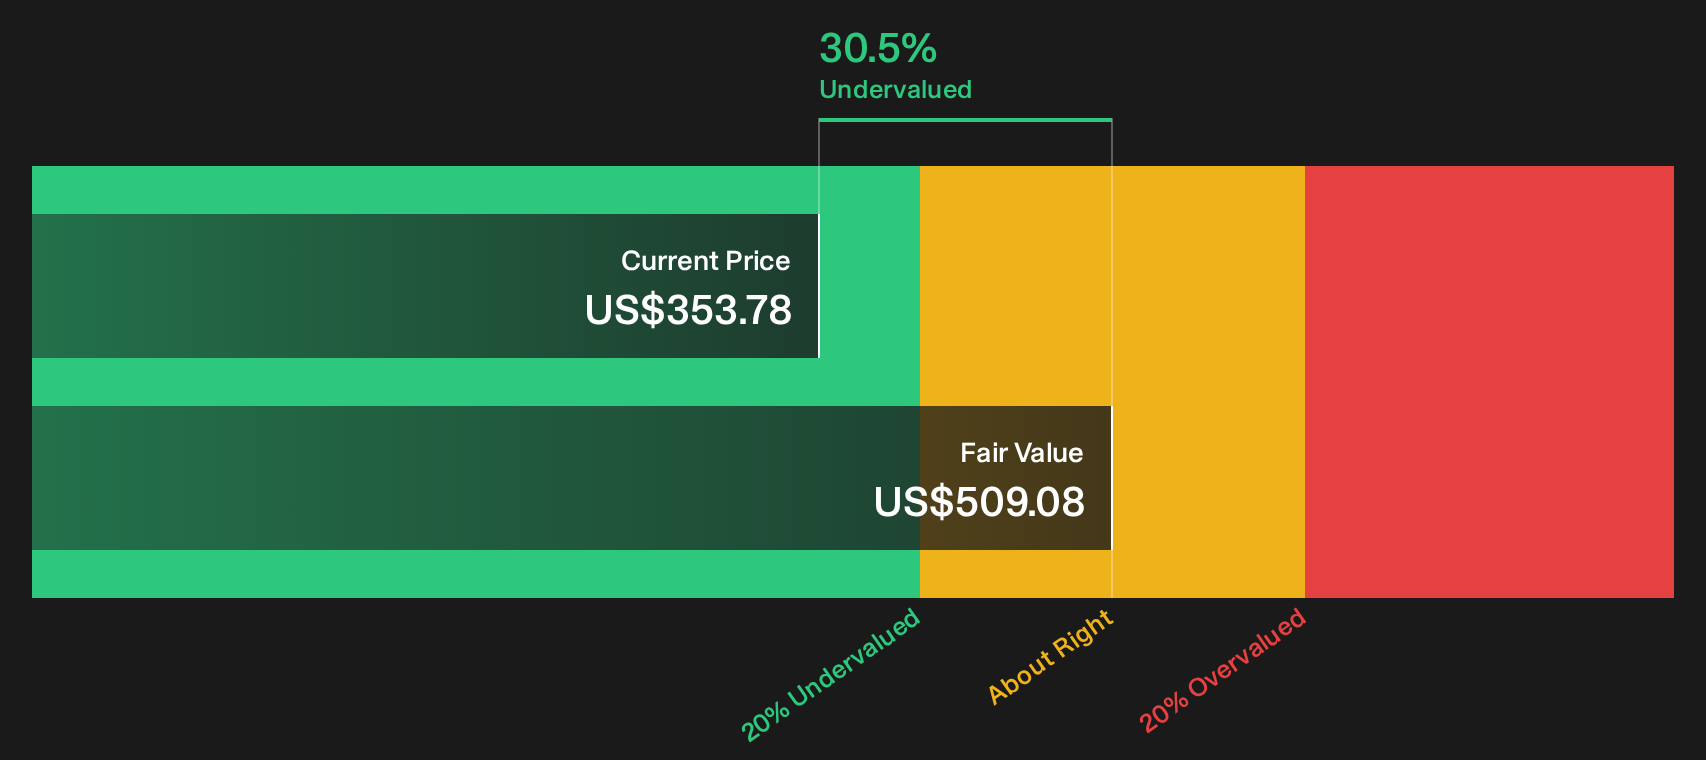
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Alphabet for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Alphabet’s value story are clear. Move quickly, test the numbers for yourself, and weigh up the 4 key rewards and 2 important warning signs.
Looking for more Alphabet investment ideas?
If you stop with just Alphabet, you risk missing other opportunities that fit your style, your risk tolerance, and your need for diversification.
- Target steady cash generators by scanning a list of solid balance sheet and fundamentals (25 results) that focuses on resilience when conditions get tougher.
- Hunt for mispriced opportunities by working through a 32 high quality undervalued stocks that filters for quality first and low expectations second.
- Stack potential income streams by reviewing a 8 dividend fortresses that highlights businesses prioritising regular cash returns to shareholders.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com