
3 Growth Companies Insiders Are Betting On
The United States market remained flat over the last week but has seen a 14% rise over the past year, with earnings forecasted to grow by 17% annually. In this environment, companies with strong growth potential and high insider ownership can be particularly appealing as they may indicate confidence from those closest to the business.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Upstart Holdings (UPST) | 14.0% | 69.5% |
| Standard Nuclear (STDN) | 18.8% | 64.2% |
| Sable Offshore (SOC) | 11.4% | 76% |
| Precigen (PGEN) | 11.7% | 54% |
| Nu Holdings (NU) | 22.8% | 22.3% |
| Himax Technologies (HIMX) | 29.1% | 70.2% |
| Figure Technology Solutions (FIGR) | 21.4% | 32.4% |
| Energy Vault Holdings (NRGV) | 10.5% | 67.3% |
| Dave (DAVE) | 16.6% | 24.1% |
| Almonty Industries (ALM) | 10.8% | 57.2% |
We're going to check out a few of the best picks from our screener tool.
John Marshall Bancorp (JMSB)
Simply Wall St Growth Rating: ★★★★★☆
Overview: John Marshall Bancorp, Inc. is the bank holding company for John Marshall Bank, offering banking products and financial services in various regions including Arlington and the District of Columbia, with a market cap of $322.04 million.
Operations: The company generates revenue primarily through its banking segment, which amounts to $66.91 million.
Insider Ownership: 12.7%
John Marshall Bancorp exhibits strong growth potential with revenue projected to grow at 75.6% annually, outpacing the US market. Its earnings are also expected to rise significantly, surpassing market averages. Insider activity shows substantial buying over the past three months, indicating confidence in its prospects. Recent executive changes include Brandon C. Lorey as CEO and plans for a dividend increase post-transaction closure, reflecting strategic positioning for future expansion and shareholder value enhancement.
- Click here to discover the nuances of John Marshall Bancorp with our detailed analytical future growth report.
- According our valuation report, there's an indication that John Marshall Bancorp's share price might be on the expensive side.
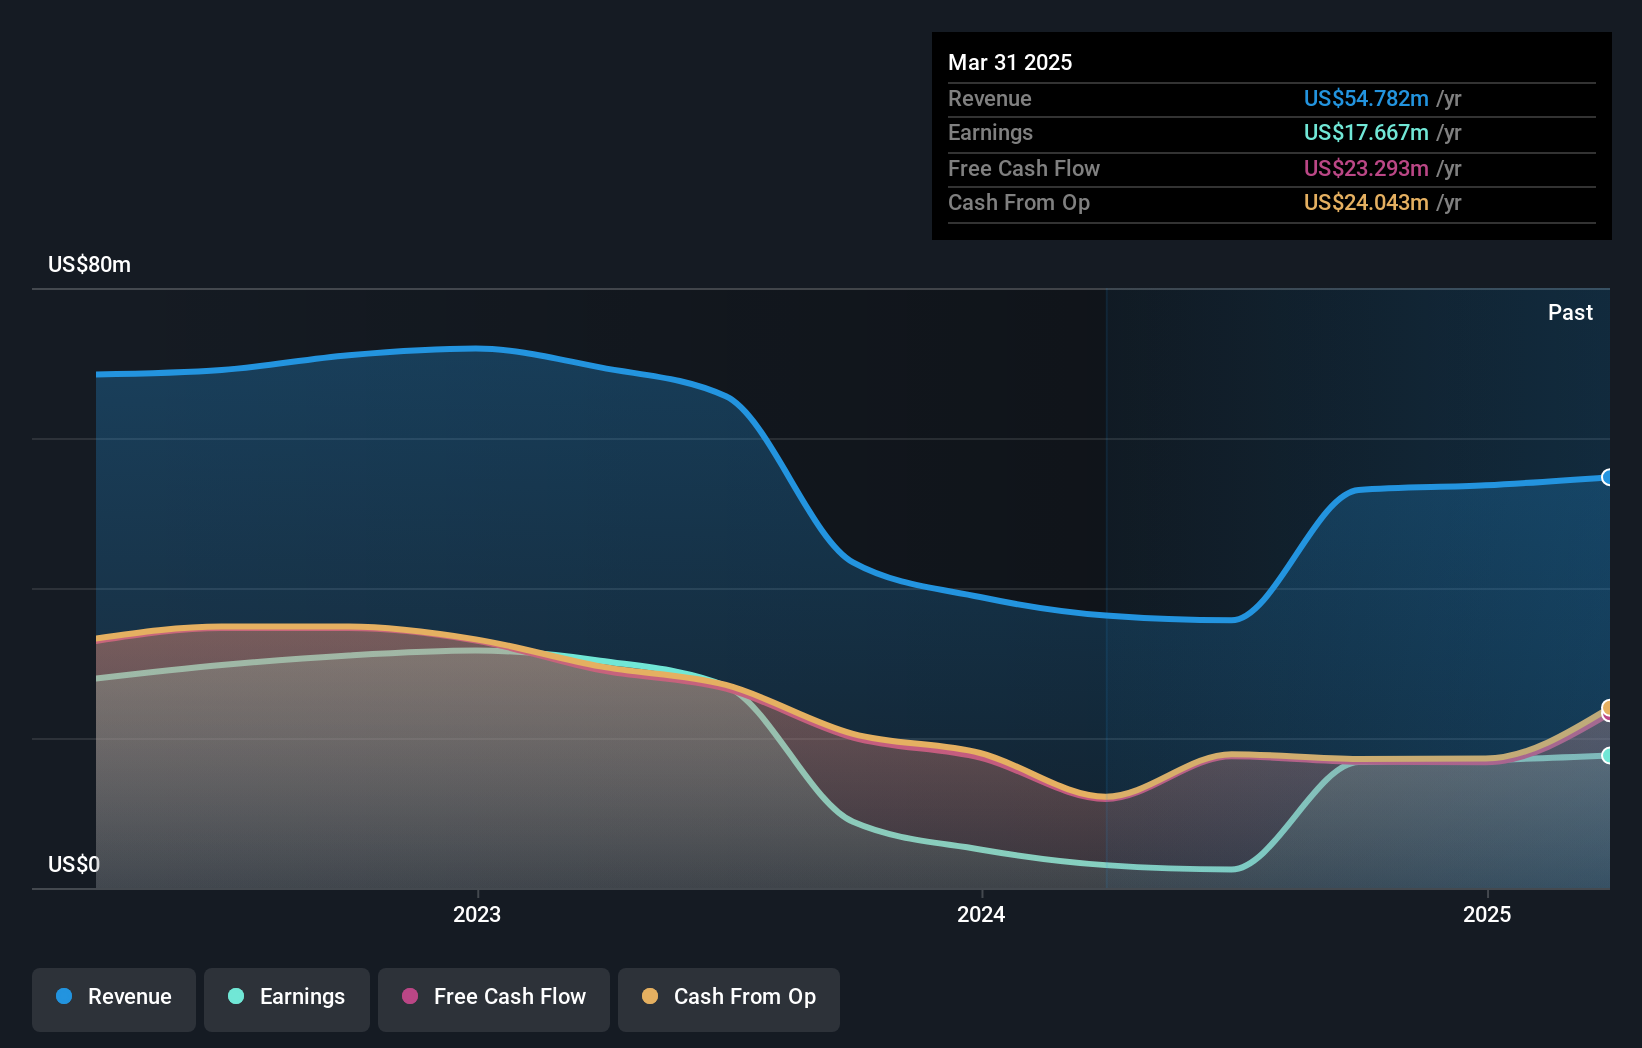
Energy Vault Holdings (NRGV)
Simply Wall St Growth Rating: ★★★★★★
Overview: Energy Vault Holdings, Inc. develops and deploys utility-scale energy storage solutions across various regions including the United States, Switzerland, and Australia, with a market cap of approximately $565.52 million.
Operations: The company generates revenue primarily from its Electric Equipment segment, amounting to $225.87 million.
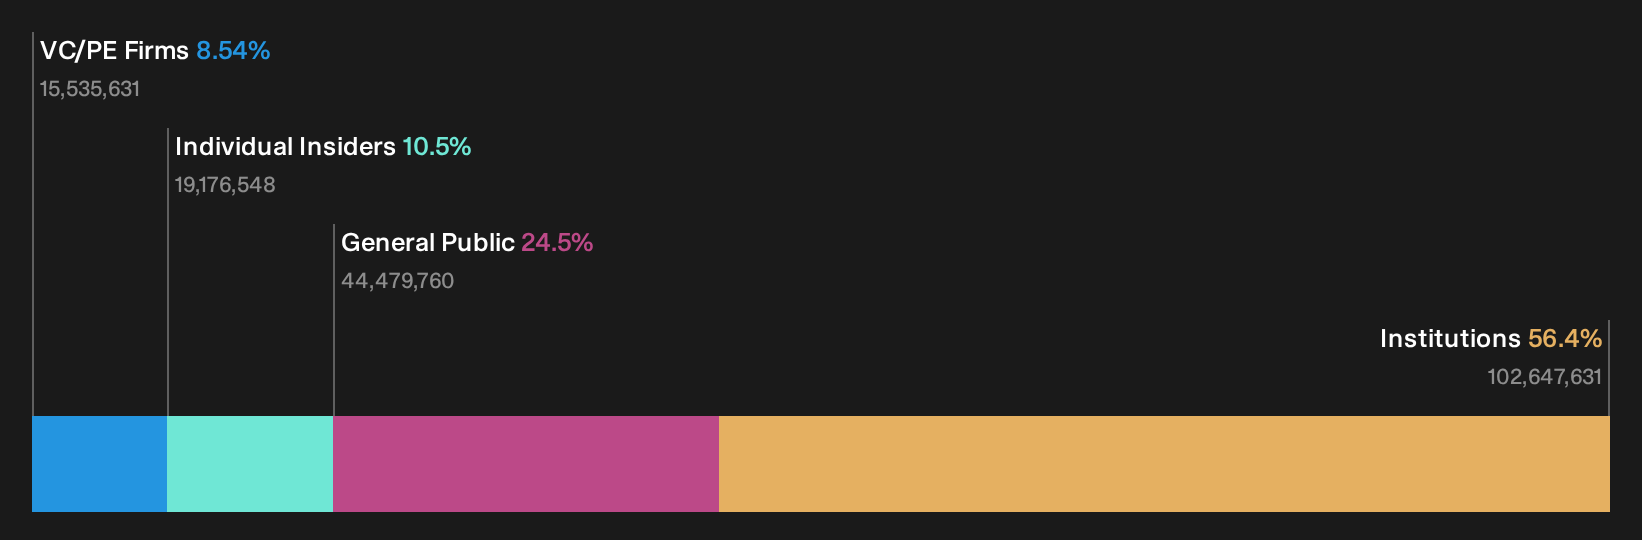
Insider Ownership: 10.5%
Energy Vault Holdings is advancing its growth trajectory with substantial insider ownership and strategic expansions, such as the 125 MW Stoney Creek BESS project in Australia. Despite a volatile share price, revenue is forecast to grow at 26% annually, surpassing market averages. The company recently secured significant power generation capacity for AI infrastructure projects and raised its full-year revenue guidance to US$270–310 million. However, it faces challenges like limited cash runway and no substantial recent insider buying.
- Click to explore a detailed breakdown of our findings in Energy Vault Holdings' earnings growth report.
- The valuation report we've compiled suggests that Energy Vault Holdings' current price could be inflated.
Waterdrop (WDH)
Simply Wall St Growth Rating: ★★★★★☆
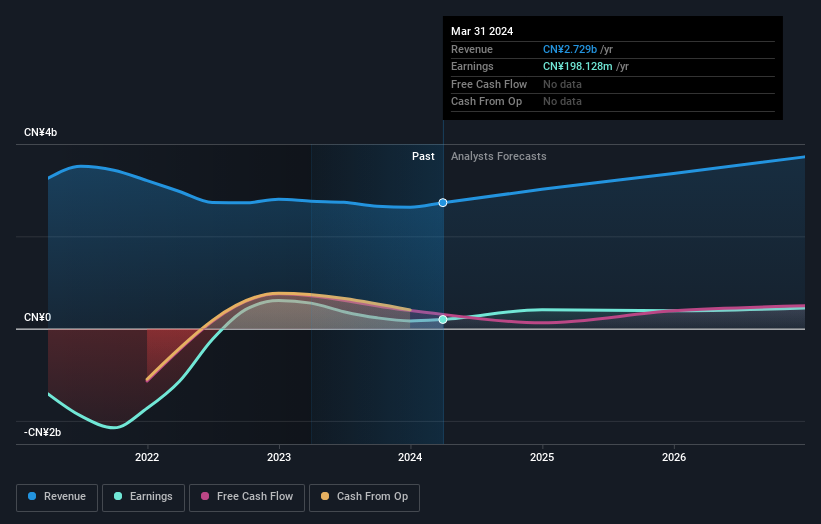
Overview: Waterdrop Inc. operates as an online insurance brokerage in the People’s Republic of China, connecting users with insurance products, and has a market cap of approximately $366.49 million.
Operations: The company's revenue primarily comes from its insurance segment, generating CN¥4.66 billion, with an additional CN¥251.42 million from crowd funding services.
Insider Ownership: 23.1%
Waterdrop's growth potential is underscored by its earnings forecast to grow at 21.3% annually, outpacing the US market average. The company trades significantly below its estimated fair value and shows promising revenue growth, expected to exceed 20% per year. Recent earnings reports highlight a substantial sales increase but a slight decline in net income compared to last year. Despite no recent insider trading activity, Waterdrop maintains competitive relative value within its industry.
- Dive into the specifics of Waterdrop here with our thorough growth forecast report.
- The valuation report we've compiled suggests that Waterdrop's current price could be quite moderate.
Summing It All Up
- Unlock our comprehensive list of 189 Fast Growing US Companies With High Insider Ownership by clicking here.
- Seeking Other Investments? This technology could replace computers: discover the 25 stocks are working to make quantum computing a reality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com