
What Merck Doubters Got Wrong
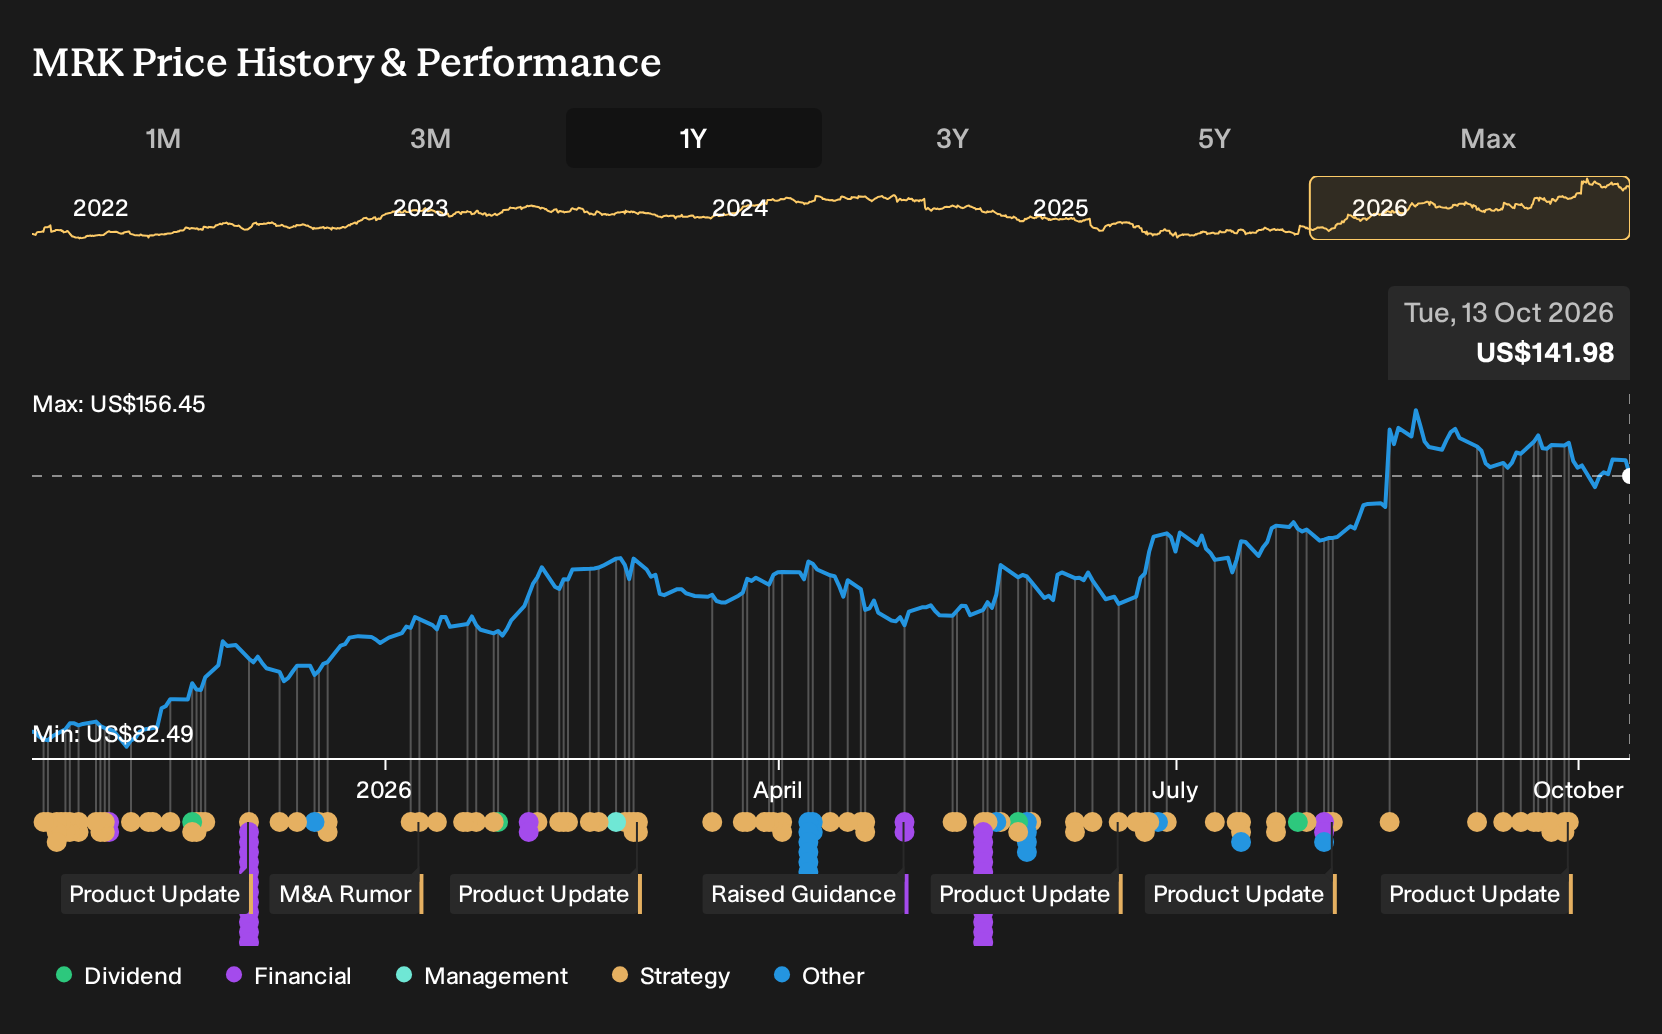
If you had watched Merck’s quarterly reports over the past year, the picture looked messy. Revenue ticked up while profits swung to a loss as acquisition charges hit the income statement. Holding Merck over the past year would have returned 72.5%, including dividends. That gain sits beside falling reported margins and heavy deal making. If you were deciding whether to buy on 13 October 2025, what did the record really suggest you were being paid for?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
This theme extends beyond Merck. See which of 33 healthcare AI stocks may still merit a closer look.
The Argument You Would Have Been Weighing Up On Merck
The shares cost US$85.7 at the start of the period. Anyone looking at Merck then had to decide which story about the next few years felt more reasonable.
The bullish narrative pointed to a Fair Value of US$102. It relied on assumptions that Merck could grow revenue 4.2% a year, lift profit margins to 33.7%, and still trade on a 12.3x P/E after three years.
The bearish view put Fair Value at US$74. That case assumed a 2.8% revenue growth rate, profit margins of 27.3%, and a 12.1x P/E over a longer five year stretch, with acquisition execution a key risk.
What The Merck Evidence Actually Tested
Merck’s biggest proof point for the bullish case came from product progress. Multiple new oncology approvals and positive late stage trial wins for Keytruda combinations and sacituzumab tirumotecan supported the idea of a broader cancer portfolio. The numbers told a harsher story. Revenue moved from US$15,806m to US$16,607m while net income shifted from profit to a US$1,335m loss and net margin fell to -8.0%. The evidence pointed in both directions.
The whole period rested on one assumption: that higher sales and a deeper drug pipeline would translate into wider margins. When assessing another pharma group with a similar pitch, track whether net income and margin move in the same direction as new approvals and acquisitions rather than taking the growth story at face value.
What Merck’s Current Price Already Assumes
Merck now trades at US$142 after a 72.5% gain over the past year. The selected Narrative argues that its Fair Value sits below that level, largely because a lot of confidence is already priced into the oncology and broader drug portfolio story.
Anyone paying today’s price would need to believe Merck can turn a concentrated set of late stage assets into a wide, durable earnings base despite recent regulatory and safety setbacks.
"The main thing that has to go right is for Merck to turn its broad late stage pipeline and recent product launches like LIPFENDRA, WINREVAIR, sac TMT and tulisokibart into a diversified growth engine that meaningfully offsets KEYTRUDA concentration and upcoming generic pressure across the portfolio."
One Narrative disagrees with today's price. → See where this Narrative says Merck should trade
Where Merck’s Story Connects Outward
Merck’s oncology and vaccine focus points toward a wider pattern in drug development. Patients needing cancer and immune therapies often depend on several large drug makers.
One of those specialists is pushing into obesity treatments and antibody drug conjugates. It is also working on new vaccines and complex immune therapies.
The same long term forces that influence Merck’s pipeline, such as aging populations and chronic disease, shape that effort as well.
If that parallel approach gains traction, the other group could influence how investors view obesity medicines, oncology pipelines and future vaccine demand across big pharma.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 27% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com