
Toronto Dominion Bank (TSX:TD) Could Be 7% Undervalued Following Its Mortgage AI Expansion
Toronto-Dominion Bank (TSX:TD) recently expanded its use of agentic AI across mortgage funding and discharge, automating document checks and information coordination to speed up workflows while maintaining a human-in-the-loop review model.
These AI investments arrive alongside other capital moves at Toronto-Dominion Bank, including recent share repurchases and a fresh fixed income offering. The share price is at CA$167.83 after a 1-day share price return of 2.22% and a year-to-date share price return of 29.28%. The 1-year total shareholder return of 55.05% and 5-year total shareholder return of 133.84% may indicate longer term momentum that investors may see as reflecting both improving efficiency and changing perceptions of risk around the bank's growth plans.
Scan how Toronto-Dominion Bank's AI push compares with other financial institutions by reviewing a hand-picked set of list of solid balance sheet and fundamentals (8 results) that may interest you if you like this story.
Bulls see Toronto-Dominion Bank using AI and buybacks to justify a richer multiple, while skeptics view efficiency gains and capital returns as already reflected. Which side do the current valuation markers lean toward?
Most Popular Narrative: 7% Undervalued
Toronto-Dominion Bank's most followed narrative pegs fair value at CA$180.07, a little above the last close at CA$167.83. This frames the current AI and capital return story as slightly underpriced by the market.
The main requirement is that TD turns its strong capital position and large AI and cost reduction programs into sustained efficiency improvements that more than offset higher AML remediation and growth spending.
See why 182 investors see Toronto-Dominion Bank as 7% undervalued.
Result: Fair Value of CA$180.07 (UNDERVALUED)
Still, the narrative around Toronto-Dominion Bank can crack if AI efficiency gains stall or if AML remediation and other regulatory costs run higher than expected.
Find out about the key risks to this Toronto-Dominion Bank narrative.
Another View On Toronto-Dominion Bank’s Valuation
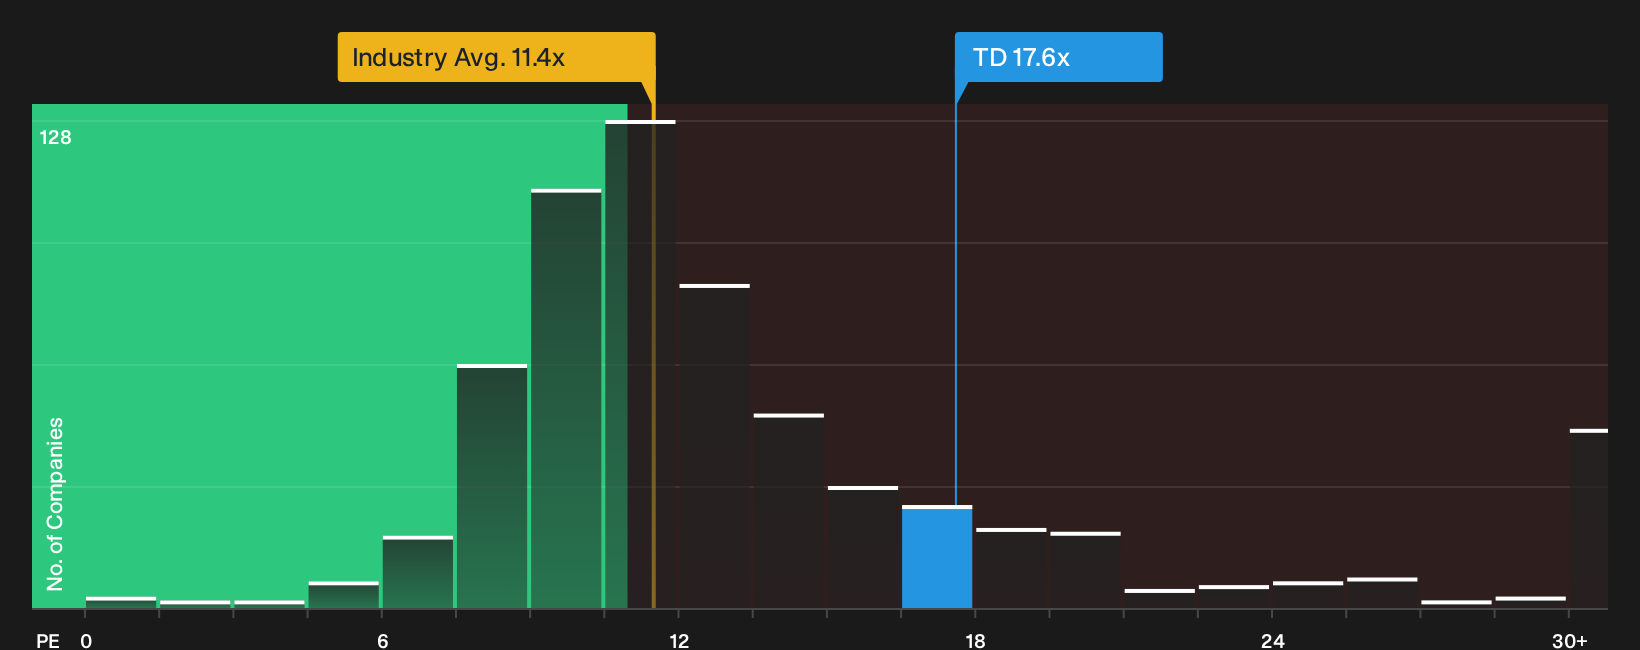
The narrative around Toronto-Dominion Bank frames the shares as modestly undervalued relative to fair value of CA$180.07. The P/E picture tells a tougher story. TD trades at 17.6x earnings, richer than the North American banks average at 11.4x, peer average at 16.9x, and above its own fair ratio of 16.5x. That gap suggests investors are already paying a premium. How comfortable are you with that pricing if the upbeat scenario on AI, buybacks and growth does not fully land?
For a closer look at how this pricing premium fits into a fuller valuation breakdown, including where the fair ratio could pull the P/E over time, See what the numbers say about this price — find out in our valuation breakdown..
Here is how TD’s valuation stacks up visually against industry peers on earnings multiples today
Next Steps
Curious whether the optimism around Toronto-Dominion Bank fits your own risk and reward trade off? Move quickly from story to numbers and see how the positives stack up in the 3 key rewards.
Looking for more Toronto-Dominion Bank style investment ideas?
If Toronto-Dominion Bank has sharpened your focus on quality, do not stop here. Broader idea generation can help you stress test your views and uncover fresh angles.
- Zero in on quality at a discount by scanning 7 high quality undervalued stocks that pair stronger fundamentals with pricing some investors may be overlooking.
- Strengthen your income stream by reviewing 2 dividend fortresses that aim to combine higher yields with more resilient payouts.
- Dial back risk while staying invested by checking 8 resilient stocks with low risk scores that score better on balance sheets and volatility controls.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com