
Can China Longyuan Power Group (SEHK:916) Justify Its Valuation Following Stronger Solar Output?
China Longyuan Power Group (SEHK:916) has updated investors on its September 2026 operating data, reporting 5,666,639 MWh of power generation, with solar output rising 20.21% and wind generation up 3.20% year on year.
That operational update has landed alongside a modest rebound in China Longyuan Power Group’s shares. The latest HK$5.41 close is tied to a 1-day share price return of 3.24% and a 7-day share price return of 2.56%, even as the year-to-date share price return has fallen 19.97% and the 1-year total shareholder return has declined 32.37%. This signals short-term momentum building against a weaker multi-year track record that includes a 5-year total shareholder return down 65%.
Scan beyond China Longyuan Power Group and compare its recent momentum with 43 power grid technology and infrastructure stocks to help you spot other grid-focused plays related to shifts in the renewable generation mix.
China Longyuan Power Group is delivering solid power output while the share price is still working through a long stretch of weak returns. After this latest bounce, are you paying a fair price for that franchise, or a premium?
Preferred Price-to-Earnings of 10.5x: Is it justified?
On current numbers, China Longyuan Power Group is trading on a P/E of 10.5x, which sits below both the Hong Kong market and the Asian renewable energy peer group. That puts a relatively low earnings multiple against a share price that has delivered weak returns over one and five years.
The P/E ratio compares what you pay for each HK$1 of earnings to what those profits are today. For a power generator like China Longyuan Power Group, investors often use P/E because cash generation and profitability are central to how they judge the business, and earnings forecasts are available to anchor expectations.
Here, the current P/E of 10.5x is slightly lower than the wider Hong Kong market on 10.7x, and it is also below the peer average on 12.4x. That suggests the market is pricing China Longyuan Power Group’s profit stream at a discount to similar renewable energy stocks, even though analyst forecasts point to earnings growth of 17.7% a year, ahead of the broader Hong Kong market expectation of 10.7% a year. Relative to an estimated fair P/E of 12.9x, the current multiple also sits meaningfully lower. This is the kind of gap that could close if the market moves closer to that reference level.
Explore the SWS fair ratio for China Longyuan Power Group.
Result: Price-to-Earnings of 10.5x (UNDERVALUED)
Still, the long stretch of falling 1 year and 5 year returns, along with exposure to China focused regulation and policy shifts, could easily derail the rerating story.
Find out about the key risks to this China Longyuan Power Group narrative.
Another View: SWS DCF model points the other way
There is a different read on China Longyuan Power Group when you switch from earnings multiples to the SWS DCF model. On that lens, the current HK$5.41 price sits above an estimated future cash flow value of HK$3.70, which frames the shares as overvalued rather than cheap.
That gap highlights a basic trade off for investors. Earnings based metrics flag a discount against peers, while a cash flow driven approach implies limited margin of safety at today’s level. Which yardstick do you trust more when the signals pull in opposite directions?
Look into how the SWS DCF model arrives at its fair value.
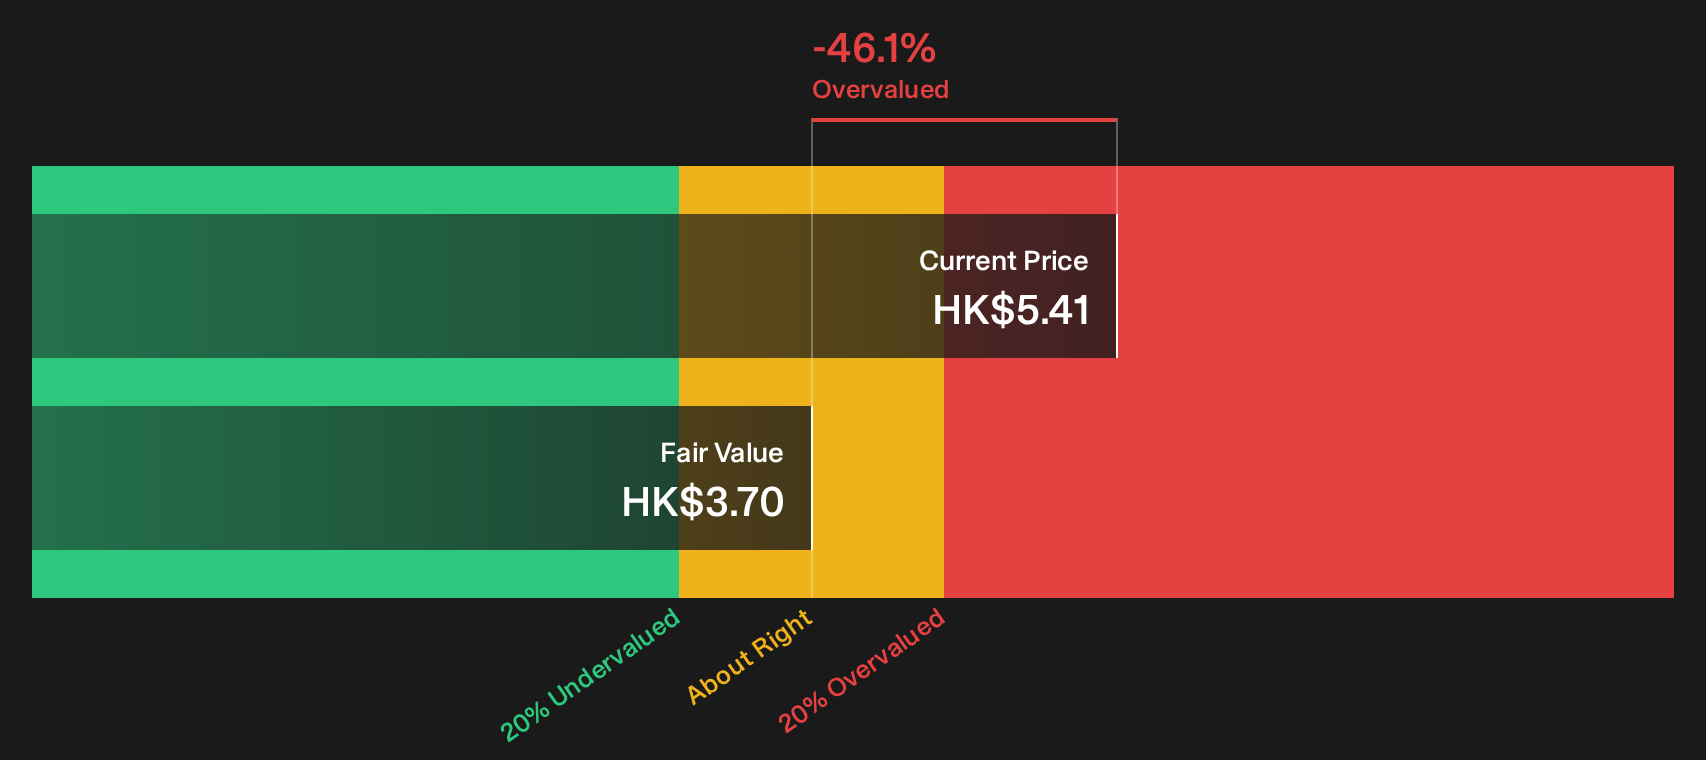
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Longyuan Power Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 185 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The split message on China Longyuan Power Group is clear, with pressure from past returns on one side and operational and valuation signals on the other. Act while the data is fresh, run the numbers yourself, and see how the story looks through your own lens by weighing 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond China Longyuan Power Group?
Do not stop at China Longyuan Power Group. Use this valuation work as a springboard and line up a watchlist that genuinely reflects where you want your money working.
- Target potential mispricing and focus on quality with companies that screen as attractively valued through the 185 high quality undervalued stocks.
- Build a portfolio that aims for resilience by focusing on businesses with stronger finances through the list of solid balance sheet and fundamentals (203 results).
- Give your income goals a serious shot by scanning for higher yielding opportunities filtered through the 217 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com