
MonotaRO (TSE:3064) Could Be 9% Below Fair Value As September Sales Jump
September sales jump puts MonotaRO’s recent share move in context
MonotaRO (TSE:3064) reported preliminary non-consolidated September 2026 sales of ¥30,136 million, compared with ¥26,558 million a year earlier. This data point has sharpened attention on the stock’s recent price moves.
The strong September sales update follows a sharp near term rebound, with a 1 month share price return of 16.5% and a 3 month share price gain of 17.9%. This has pushed MonotaRO higher even though the year to date share price return is still down 3.4%. Longer term holders have seen a 22.4% 1 year total shareholder return and roughly 90.9% over three years, suggesting momentum has been rebuilding after a weaker five year total shareholder return of about a 7% decline.
Scan other fast moving industrial and capital goods stocks showing similar momentum to MonotaRO with our curated 73 high quality undiscovered gems list.
After a sharp rebound in both sales and share price, MonotaRO now sits at a different starting point for new capital. Does the current valuation still offer an appealing trade off between risk and potential reward?
Price-to-earnings of 32.1x: Is it justified for MonotaRO?
MonotaRO trades on a P/E of 32.1x, while the last close sits at ¥2,321. As a result, the shares carry a clear premium to both industry peers and the stock’s own estimated fair ratio.
The P/E ratio compares the current share price to earnings per share. For a business like MonotaRO, which runs an online MRO products platform, that metric effectively shows how much investors are willing to pay today for each unit of current profit.
Recent data points show earnings grew 21.7% over the past year and 16.3% per year over five years, with high quality earnings and a Return on Equity of 29.1%. Earnings and revenue are both forecast to grow faster than the wider JP market, and management’s model suggests the shares trade at about a 9.2% discount to an intrinsic cash flow value of ¥2,555.83. In contrast, the current 32.1x P/E is described as expensive compared with both the JP Trade Distributors industry average of 10.6x and the peer average of 11.6x. It is also materially higher than an estimated fair P/E of 20x that the market could move towards over time.
That premium multiple is therefore not just slightly higher than the sector. It is almost three times the industry level and well above the 20x fair ratio estimate, which signals investors are already paying up heavily for the growth and profitability profile that MonotaRO currently delivers.
Explore the SWS fair ratio for MonotaRO..
Result: Price-to-earnings of 32.1x (OVERVALUED)
Still, the MonotaRO story carries risk if high growth expectations baked into a 32.1x P/E fade, or if online MRO competition starts to squeeze pricing power.
Find out about the key risks to this MonotaRO narrative.
Another view on MonotaRO’s valuation
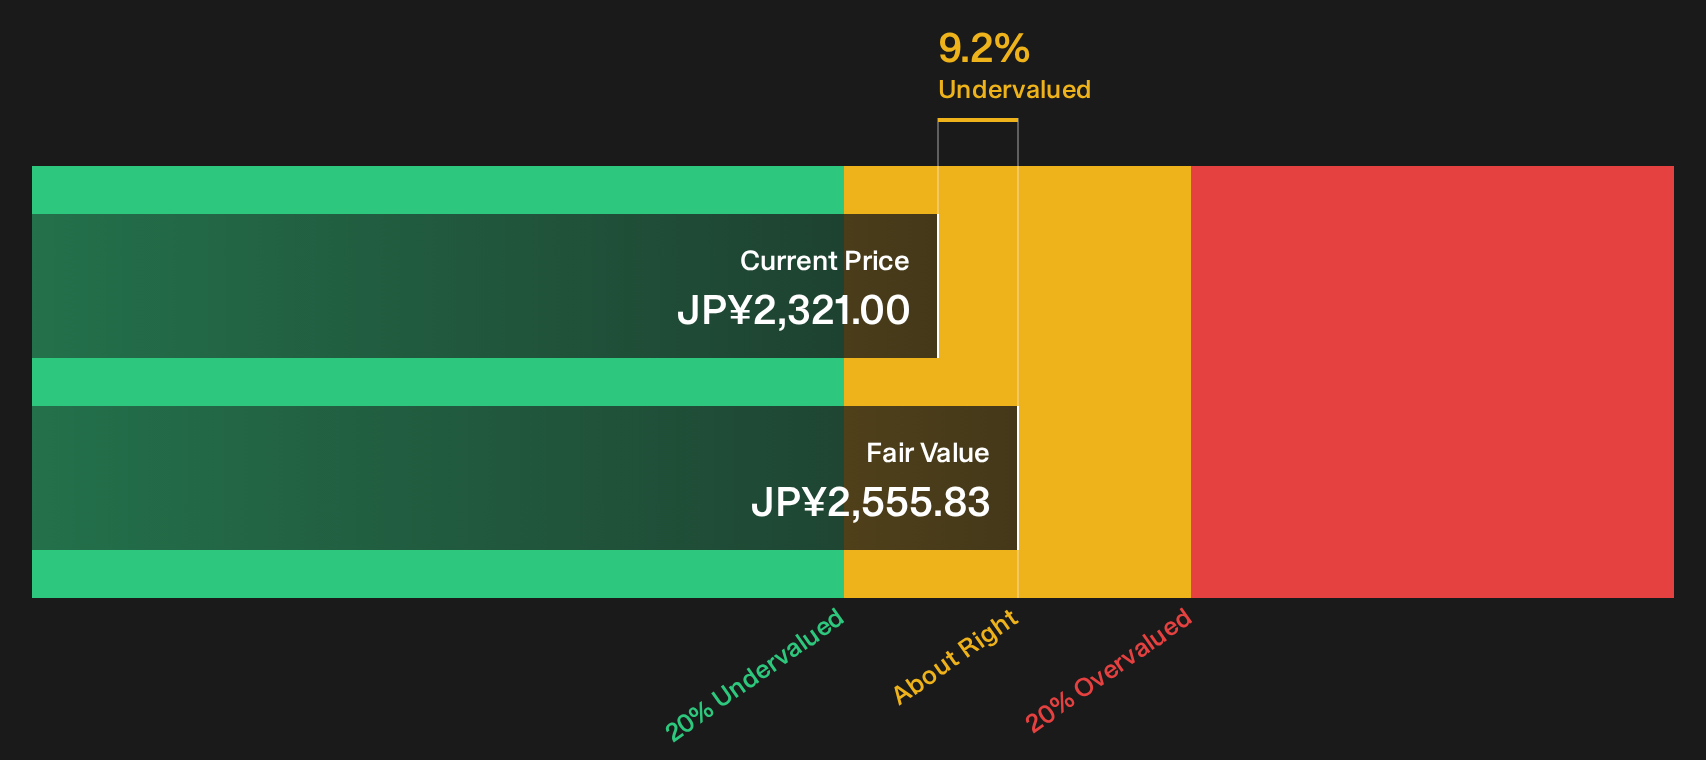
The P/E points to a rich price tag, yet the SWS DCF model tells a slightly different story. On that cash flow view, MonotaRO at ¥2,321 sits about 9.2% below an estimated value of ¥2,555.83. This frames the premium multiple as less extreme than it first appears. The question is whether you trust earnings-based signals or cash flow estimates more when they disagree.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out MonotaRO for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this MonotaRO story feels finely balanced, move quickly from reading to checking the figures yourself and pressure test the assumptions that matter most to you. To see which specific potential upsides our work highlights, review the 3 key rewards
Looking for more MonotaRO investment ideas beyond this stock?
If MonotaRO sits on your radar, do not stop here. Use the Simply Wall St screener to find other opportunities before they move without you.
- Target resilience by scanning a 22 resilient stocks with low risk scores that can help cushion your portfolio when individual positions misfire.
- Hunt for quality at a reasonable price by checking a 14 high quality undervalued stocks that pairs strong fundamentals with more modest valuations.
- Build staying power into your income stream by reviewing a 27 dividend fortresses that may support more consistent cash returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com