
British Founder Led Stocks To Own In October 2026
UK inflation recently reached 3.7% as energy costs climbed, reminding every household how quickly macro shocks can hit day to day budgets. That kind of backdrop puts a spotlight on businesses where founders still call the shots and often think in decades, not quarters. This article walks through three founder-led UK stocks from our screener that may help you focus on long term alignment rather than short term headlines.
The three stocks highlighted here offer a compelling starting point if you want exposure to founder led businesses where leadership is deeply invested in the outcome. However, if you want the names that matter most, these 8 top founder-led companies are the strongest companies we've found.
Fevertree Drinks (AIM:FEVR)
Fevertree Drinks builds its premium mixer story around founder influence, with Tim Warrillow and Charles Rolls shaping the Fever Tree brand that now sells tonics, gingers, sodas and cocktail mixers across the UK, US and Europe, and carries a market value of about £978 million.
For a screener built around long term founder commitment, Fevertree Drinks puts a human imprint on a very everyday habit: the mixers poured into home cocktails and bar serves.
"Although Fevertree Drinks is broadening its range beyond tonic and reports that the wider portfolio now represents nearly half of group sales, a further shift in consumer taste away from mixers could leave the company with high exposure to flavours that fail to scale."
The real swing factor now is whether one unseen pressure on profitability quietly tightens or eases over the next few years.
That pressure is where your edge can come from, and the full narrative for Fevertree Drinks shows how founder alignment, brand strength and cost trends could be quietly reshaping the story.

Computacenter (LSE:CCC)
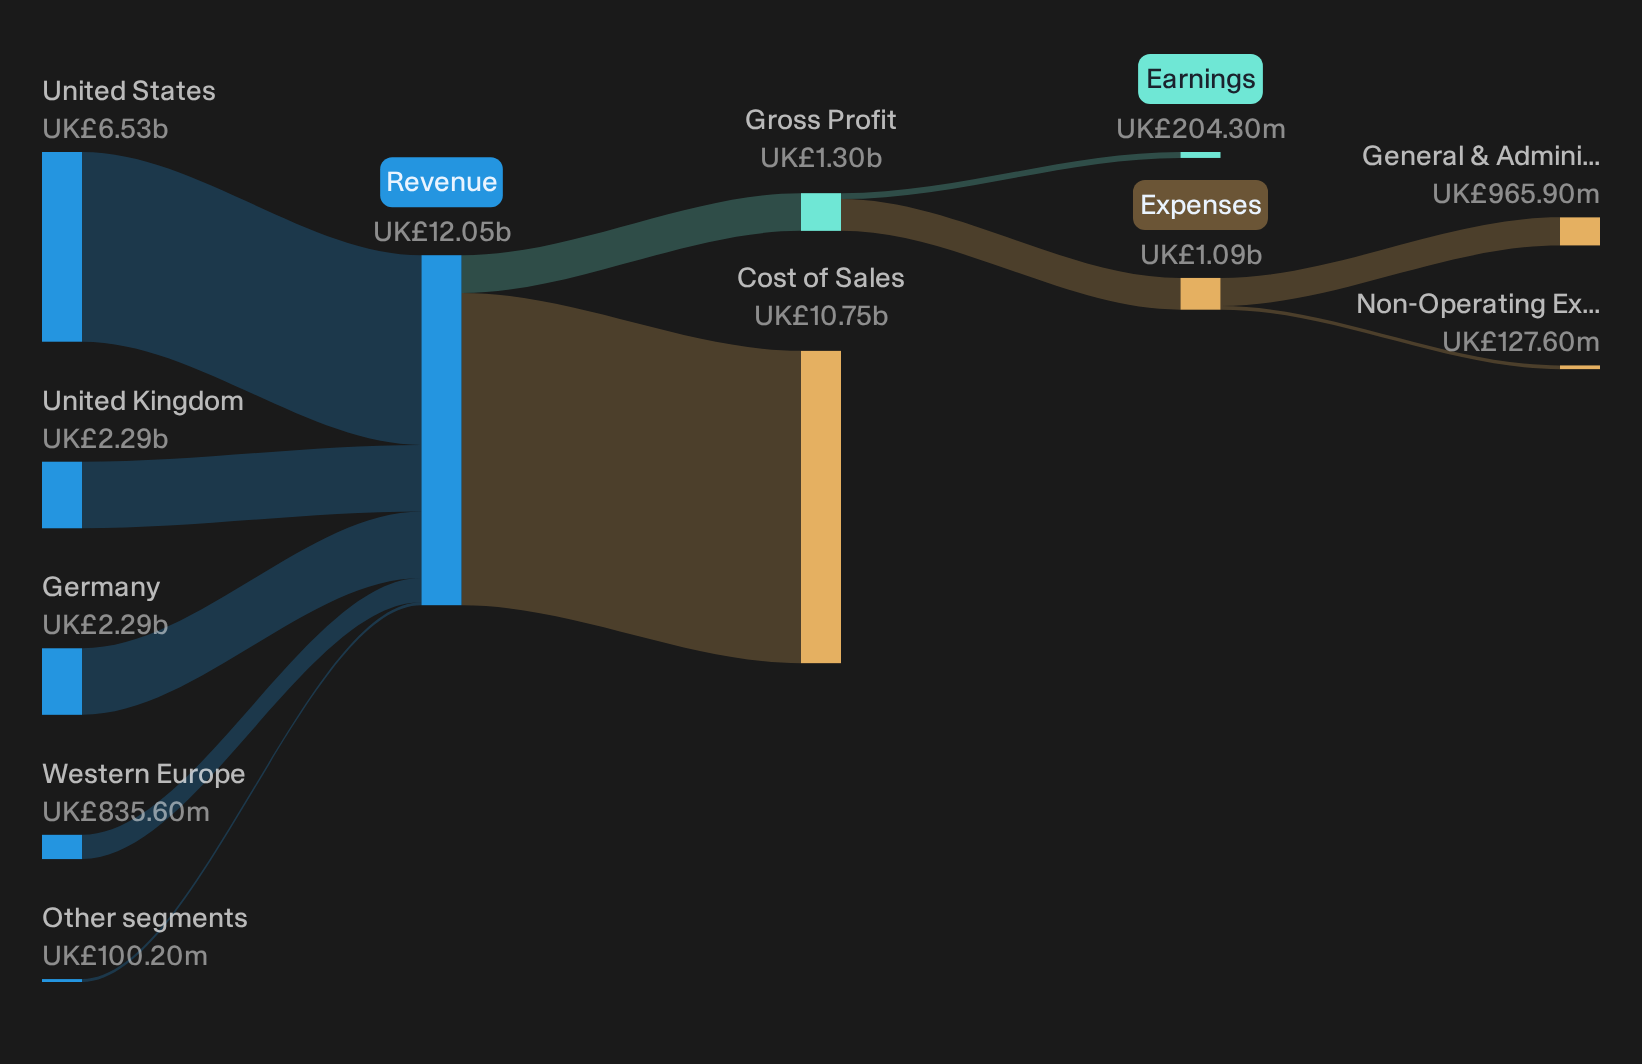
Computacenter runs large scale IT sourcing, support and managed services for corporate and public sector clients, with about £12.1b from Computer Services and a market value near £6.0b. Its long duration outsourcing contracts reflect a legacy minded service culture rather than a quick turn project shop.
Computacenter may appeal to investors who value founder style continuity more than charismatic branding. Longstanding managers steer a £12.1b services operation that focuses on recurring workplace and infrastructure outsourcing. This model can be sensitive to changes in contract profitability, which could have a significant impact on investor outcomes.
That contract sensitivity is exactly what you can unpack further in the analysis report for Computacenter and see how recurring deals and margins might be decoupling.
Foresight Group Holdings (LSE:FSG)
Foresight Group Holdings runs infrastructure and private equity funds that back real assets and founder-led businesses, with founder alignment most visible in its £50 million private equity arm alongside £115 million from real assets, and the group carries a market value near £488 million.
Foresight Group Holdings speaks directly to the Founder-Led Companies theme because its private equity arm is built around backing founders with long-term capital, then reinforcing that alignment with active ownership and disciplined capital decisions that reward patient shareholders.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is described as a potential driver of compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
What really matters now is how one quiet shift in where Foresight Group Holdings earns its next pound of fees shapes that compounding story.
That shift in fee mix is exactly what the full narrative for Foresight Group Holdings unpacks, revealing how compounding, capital recycling and risks might be quietly accelerating the Foresight Group Holdings story.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. By the time a theme hits headlines, the early entry window can be closing fast. Track breakouts under the radar for now and act while conditions still look favorable.
- Target income that does more of the heavy lifting and scan a curated set of 2 dividend fortresses built around durability and consistent cash returns.
- Spot momentum where cash generation already backs the story and review 39 profitable AI stocks that aren't just burning cash that pair AI exposure with real earnings support.
- Rotate toward sturdier balance sheets before stress shows up in prices and work through a list of solid balance sheet and fundamentals (9 results) that filters for financial resilience first.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com