
Seven & i Holdings (TSE:3382) Lifts Guidance And Dividend As Fair Value Still Looks In Sight
Seven & i Holdings (TSE:3382) has put fresh numbers on the table by issuing full year earnings guidance and lifting its second quarter dividend, giving investors new detail on profit expectations and cash returns.
Recent trading gives a mixed read on momentum for Seven & i Holdings. The share price is up 0.68% over the past day and 1.58% over the past week, yet down 12.06% year to date, while total shareholder return over five years is 39.63%. This points to stronger rewards for long term holders than the short term chart suggests.
Compare this move at Seven & i Holdings with other hand picked retailers adjusting guidance and payouts by scanning our 14 high quality undervalued stocks that pair solid balance sheets with compressed valuations.
Seven & i Holdings is signaling confidence through guidance and a higher dividend, yet the share price is still lagging this year. Does that combination add up to a genuinely attractive valuation today?
Most Popular Narrative: 11% Undervalued
On the widely followed narrative, Seven & i Holdings carries a fair value estimate of ¥2,256.9 against a last close of ¥1,998.5. This frames that earnings guidance and dividend lift against a modest valuation gap built on a 5.87% discount rate.
Execution of business portfolio transformation, including divestitures of underperforming superstore, department store, and banking operations, will free up capital for reinvestment in the more profitable and scalable convenience segment, raising return on equity (ROE) and group profitability over time.
Leadership changes and a renewed focus on comprehensive profit enhancement and cost structure reform across both Japan and international operations are laying the groundwork for structural earnings growth, with the potential to lift consolidated net income and support long term EPS expansion.
See why 3 investors see Seven & i Holdings as 11% undervalued.
Result: Fair Value of ¥2,256.90 (UNDERVALUED)
Still, Seven & i Holdings faces pressure from rising expenses that could squeeze margins and slow restructuring progress, which might delay any payoff from portfolio changes.
Find out about the key risks to this Seven & i Holdings narrative.
Another View: Seven & i Holdings Through a Market Multiple Lens
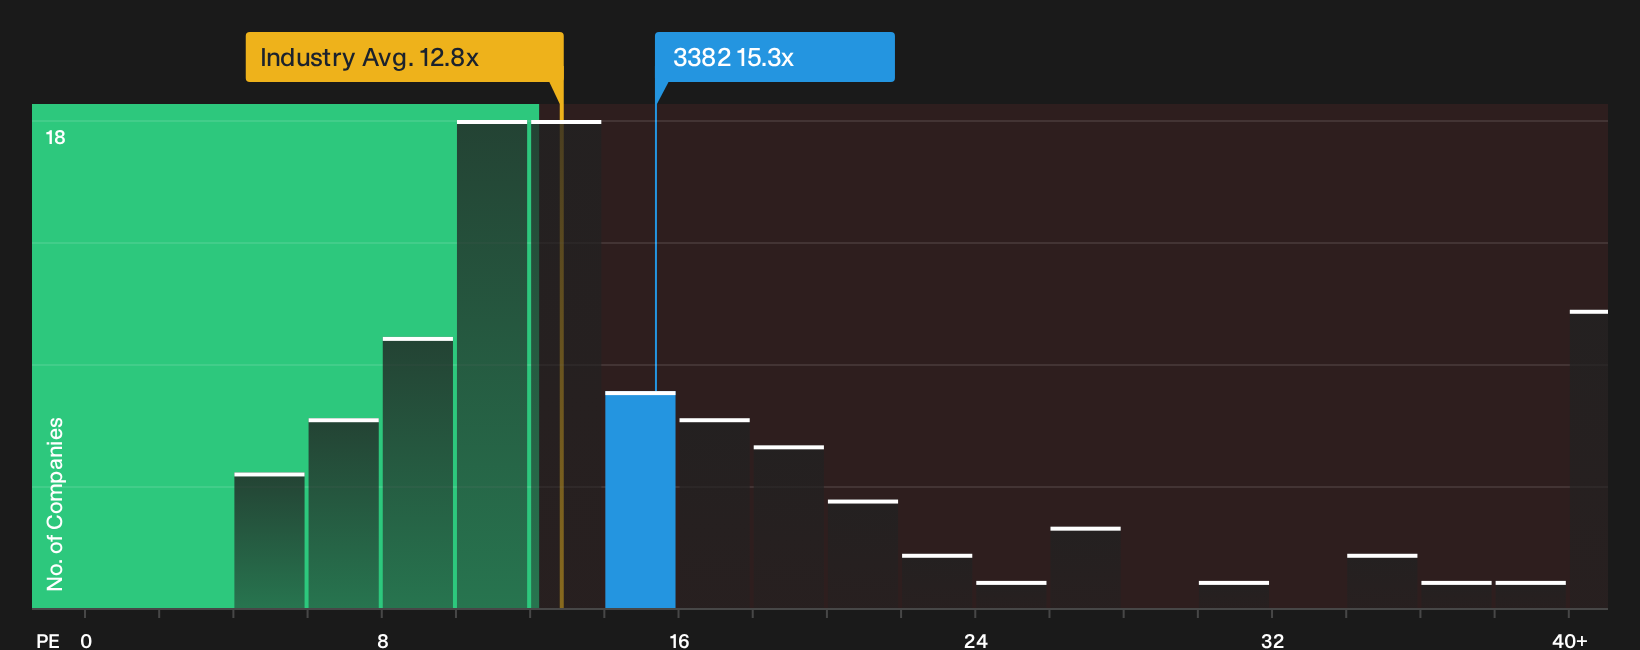
There is a twist when you shift from that narrative fair value to how the market is actually pricing Seven & i Holdings today. The shares trade on a P/E of 15.3x, above the JP consumer retailing industry on 12.8x and peers on 14.3x, yet only slightly below a fair ratio of 15.7x. That mix points to limited margin of safety on this metric, so how much faith do you want to place in the longer term story?
To see how this price tag stacks up against the underlying earnings profile and peer group in more detail, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals can create noise around Seven & i Holdings. For a clearer view, check the full picture now and weigh both the upside and the caution flags by reviewing 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Seven & i Holdings?
If Seven & i Holdings has caught your attention, do not stop there. Broaden your watchlist now and give yourself more options before the next move.
- Target reliable cash generators by checking companies offering resilient payouts through the 27 dividend fortresses.
- Hunt for quality at a discount by reviewing the 73 high quality undiscovered gems that pair solid fundamentals with limited attention from the market.
- Prioritize capital preservation and steadier journeys by scanning the 22 resilient stocks with low risk scores that focus on resilience when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com