
3 Reasons Perella Weinberg Partners (PWP) Valuation Looks Hard To Ignore As Summerfield Joins
Perella Weinberg Partners (PWP) has drawn fresh attention after appointing former Citi Managing Director Hamish Summerfield as a Partner in its Financial Services business, where he will focus on advising global asset management clients.
Recent trading has been mixed for Perella Weinberg Partners, with the share price delivering a 30-day return of 8.86% and a 7-day gain of 3.67%, while the year-to-date share price return is down 8.26%. Over a longer stretch, total shareholder return has declined 17.10% over the past year but remains positive at 70.22% over three years and 27.72% over five years. This indicates that longer term holders are still sitting on gains even as near term momentum has been rebuilding around news such as the Summerfield appointment.
Spot similar advisory firms that could be building momentum around leadership moves like Perella Weinberg Partners by reviewing our hand picked 20 high quality undiscovered gems.Perella Weinberg Partners now sits at an interesting crossroads. Has the recent rebound and leadership news already done most of the work, or is there still clear upside left in the valuation story ahead?
Price-to-Earnings of 53.7x: Is it justified for Perella Weinberg Partners?
On recent prices around $16.10, Perella Weinberg Partners is trading on a P/E of 53.7x, which suggests the stock is priced richly compared to both peers and the broader US Capital Markets industry.
The P/E ratio compares the share price to earnings per share and is a quick way to see how much investors are willing to pay for each dollar of profit. For an advisory firm like Perella Weinberg Partners, that multiple often reflects how confident the market is in the durability of its fee income and the potential for earnings to scale as revenue grows.
In this case, the business carries a 53.7x P/E against a peer average of 10.1x, implying the market is paying more than five times the peer valuation for the same unit of earnings. Against the wider US Capital Markets industry at 37.6x, the gap is still wide. This points to a stock that is priced more aggressively than sector norms rather than sitting near a level the market could move towards.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 53.7x (OVERVALUED)
Still, the story around Perella Weinberg Partners can fray quickly if fee activity cools or if the premium P/E multiple compresses toward sector levels.
Find out about the key risks to this Perella Weinberg Partners narrative.
Another View on Perella Weinberg Partners’ Valuation
The rich P/E for Perella Weinberg Partners is only one lens. Our DCF model presents a different perspective, with an estimated future cash flow value of $2.63 per share compared with a market price of $16.10. That indicates a stock trading well above this model’s output. So which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
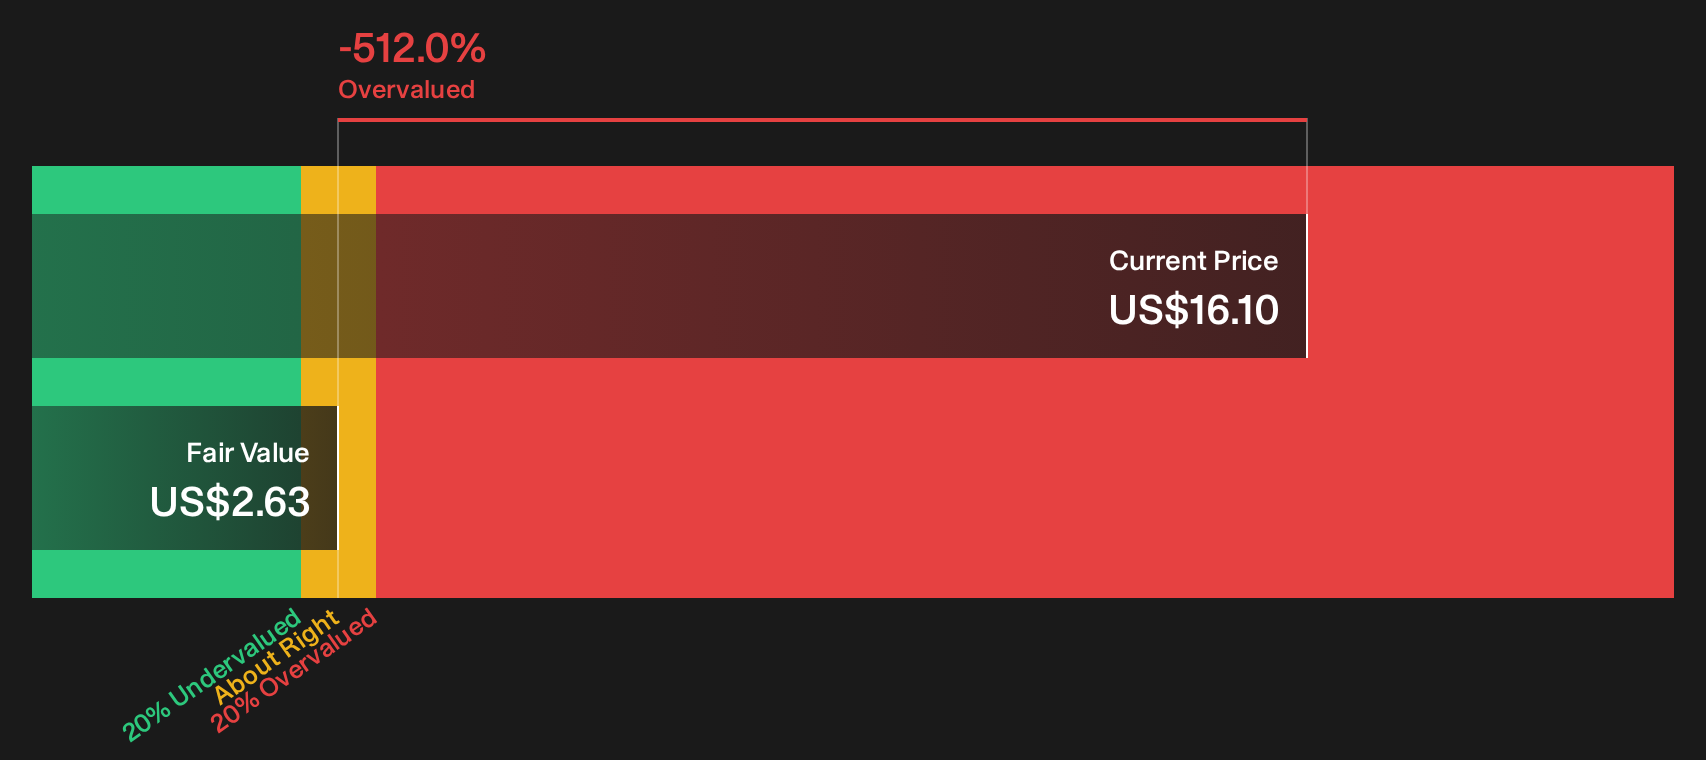
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Perella Weinberg Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Perella Weinberg Partners is clearly split, with both risks and rewards on the table. It makes sense to review the data yourself and move quickly while the facts are fresh in mind. To see both sides laid out in one place, start with the 1 key reward and 3 important warning signs
Looking for more investment ideas beyond Perella Weinberg Partners?
Do not stop with Perella Weinberg Partners. Use fresh data and clear filters to uncover other opportunities that fit your style before the rest of the market catches on.
- Target potential mispricing by scanning a curated pool of quality candidates through the 32 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses in the 8 dividend fortresses.
- Reduce portfolio stress by concentrating on financially resilient companies using the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com