
Top 3 Dividend Stocks To Watch In October 2026
Inflation running at 3.7% in the latest September CPI report keeps pressure on interest rates and keeps cash yields tempting. That also makes reliable dividend payers with strong balance sheets more valuable, especially those offering income above 5%. Instead of chasing volatile stories, you can lean on companies that have kept payouts coming through rough markets. This article breaks down three such high-yield veterans from this income-focused screen.
The three stocks covered below are only a sample, as the full Dividend Aristocrats screen surfaced another 216 income plays with similarly resilient payout histories and balance sheets that may interest income investors.
If you want to identify which of those established dividend payers align best with your risk tolerance and income goals, head straight into the Dividend Aristocrats screener to filter and analyze the highest conviction candidates.
Lonking Holdings (SEHK:3339)
Overview: Lonking Holdings manufactures and finances wheel loaders, excavators, road rollers and forklifts, supplying construction and infrastructure projects in China and overseas.
Operations: Lonking generates about CN¥12.3b from construction machinery sales, with roughly CN¥8.1b from Mainland China and CN¥4.2b from international customers.
Market Cap: HK$13.0b
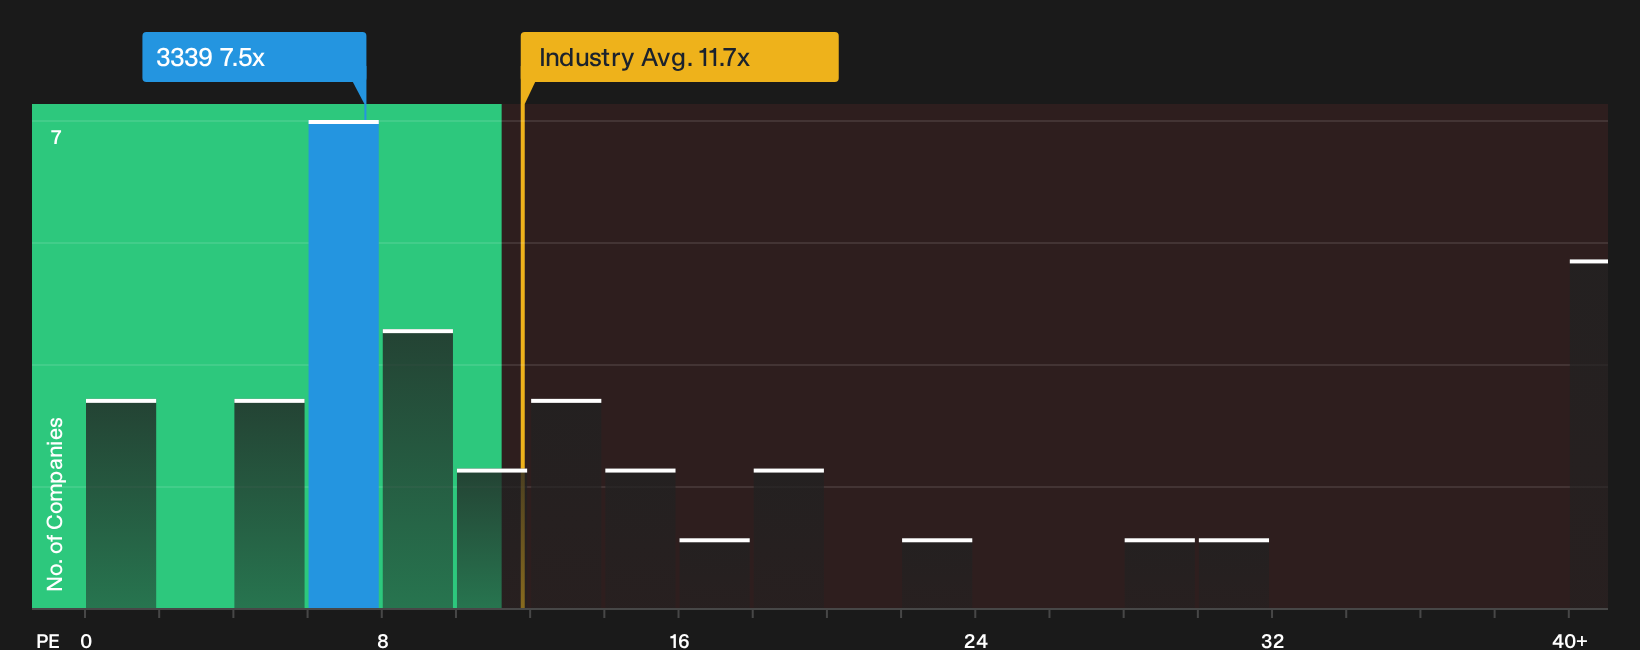
Income investors looking at the Dividend Aristocrats theme may be drawn to Lonking Holdings because its wheel loaders, excavators and forklifts already support recurring cash flow from construction projects. A P/E of 7.5x and improving earnings provide some valuation appeal if dividend stability improves and one unresolved pressure on its payouts moves in the right direction.
If that payout pressure matters to you, scan the 3 key rewards and 1 important warning sign to see what could shift Lonking Holdings from a cautious hold to an income workhorse.
China Hongqiao Group (SEHK:1378)
Overview: China Hongqiao Group is a large aluminum producer that turns bauxite into molten aluminum, ingots and foils that underpin its high dividends.
Operations: The group generates about CN¥168.8b from manufacturing and selling aluminum products, with roughly CN¥155.2b coming from customers in the PRC.
Market Cap: HK$209.7b
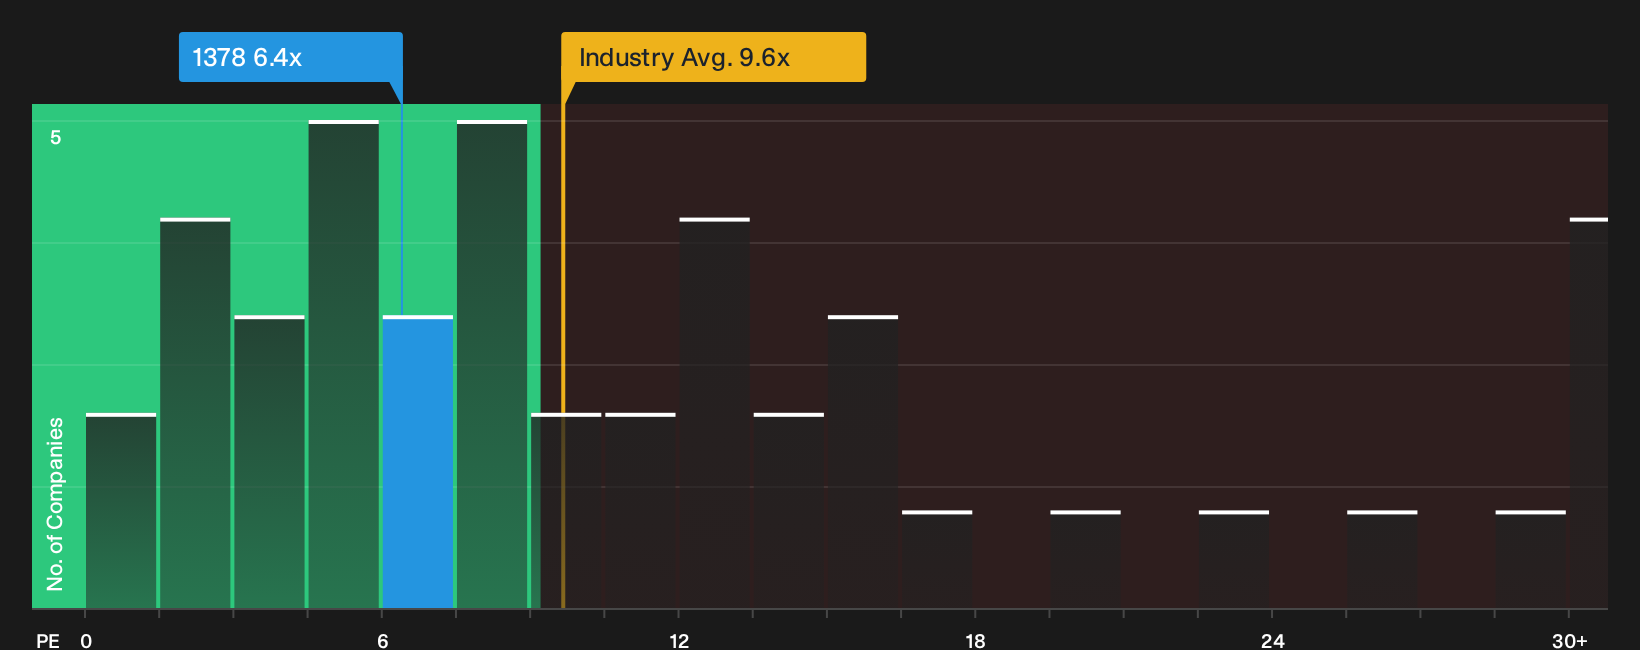
China Hongqiao Group combines high aluminum driven cash generation, a 6.4x P/E and 20.7% ROE in a high-yield dividend setting, backed by recent interim earnings strength and debt redemptions that reduce funding strain. However, the appeal of those payouts now hinges on what happens if a single key assumption breaks in its aluminum and power economics.
If that single assumption is what you are weighing, walk through the 4 key rewards and 1 important warning sign to see how China Hongqiao Group's yield could decouple from its aluminum economics.
Cathay Pacific Airways (SEHK:293)
Overview: Cathay Pacific Airways runs international passenger and cargo flights, using airline operations to fund regular cash dividends that can support high yields.
Operations: Cathay Pacific generates about HK$119.3b from its main airline segment, with HK$71.3b earned in Chinese Mainland, Hong Kong and Taiwan.
Market Cap: HK$84.8b
Cathay Pacific Airways appeals to income-focused investors because its core passenger and cargo routes generate the cash that supports dividend payouts. However, the ability to maintain distributions at 5% or higher depends on how its airline economics respond to global trade conditions and cost pressures.
"Yet what loomed already large over Cathay currently becomes uglier by the week, that is the veritable trade war between the US and China."
The key issue now is how an unresolved combination of cost and demand pressures may influence the relationship between Cathay Pacific Airways' earnings capacity and its future payouts.
Those cross currents matter, so read the full narrative for Cathay Pacific Airways to see how Cathay Pacific Airways could turn today’s pressure into tomorrow’s accelerating income story.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities do not sit still. Breakout momentum can get caught quickly once the crowd notices. Scan these under the radar ideas while it matters and get in early.
- Target durable income from companies built to keep paying by running a curated pool of higher yield candidates through the 219 dividend fortresses.
- Spot early movers in electrification and infrastructure by checking the curated 43 power grid technology and infrastructure stocks before those grid enablers stop trading like under the radar ideas.
- Hunt for early leaders in a complex niche by tracking the focused 32 best rare earth metal stocks while these specialists are still priced like overlooked suppliers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com