
How Investors Are Reacting To Waters (WAT) AI Lab Automation Launch
- Waters Corporation recently introduced Waters AI Link for its waters_connect Software and joined Anthropic's Model Hardware Standard research program to let AI agents control its LC-MS instruments and connected lab automation.
- This move pushes Waters deeper into customers' AI-heavy lab workflows, tying instrument usage, consumables consumption, and informatics spend more tightly into a single platform.
- We will look at how Waters' investment narrative is influenced by deeper AI driven instrument control through Waters AI Link.
Scan how Waters is wiring AI directly into lab hardware, then compare it with handpicked peers using 92 AI infrastructure stocks that are part of the same automation and data-center buildout wave.
Waters Investment Narrative Recap
To stay comfortable owning Waters, you need to believe the core lab instrumentation and software engine remains healthy while the BD Biosciences and Diagnostic Solutions deal moves from heavy lifting into cleaner execution. In the short term, the key swing factor is still how smoothly that integration progresses, especially margin repair after one off items and a 3.6% net profit margin that sits well below last year.
The biggest current risk is that dilution, weaker China trends in the acquired units, or softer pharma and industrial budgets keep weighing on earnings quality even if revenue holds up. Waters AI Link does not change that near term equation on its own. It reinforces the longer term AI workflow story more than the next quarter.
The most relevant recent development for that story is Waters AI Link itself, which plugs the waters_connect Software environment into Anthropic’s Model Context Protocol and Model Hardware Standard. That connects AI agents directly to LC MS instruments and lab automation, giving customers a way to run AI designed experiments and have data loop straight back into models with far less manual effort.
For an investor watching catalysts, this matters because Waters is already closely tied to digital workflows through Empower and chemistry consumables. If AI directed labs gain traction, Waters can lean on an installed base, higher software stickiness, and potentially more recurring column and reagent demand. Execution still has to line up with BD integration and China repair. The AI story only really pays off if those operational pieces stay on track.
What the Current Forecasts Assume About Waters
Waters' analyst narrative points to forecast revenue of US$7.9b and earnings of US$1.4b by 2029. That profile is built on an assumed 19.3% yearly revenue growth rate and an earnings step up from US$166.6m today to US$1.4b, which is an increase of about US$1.2b.
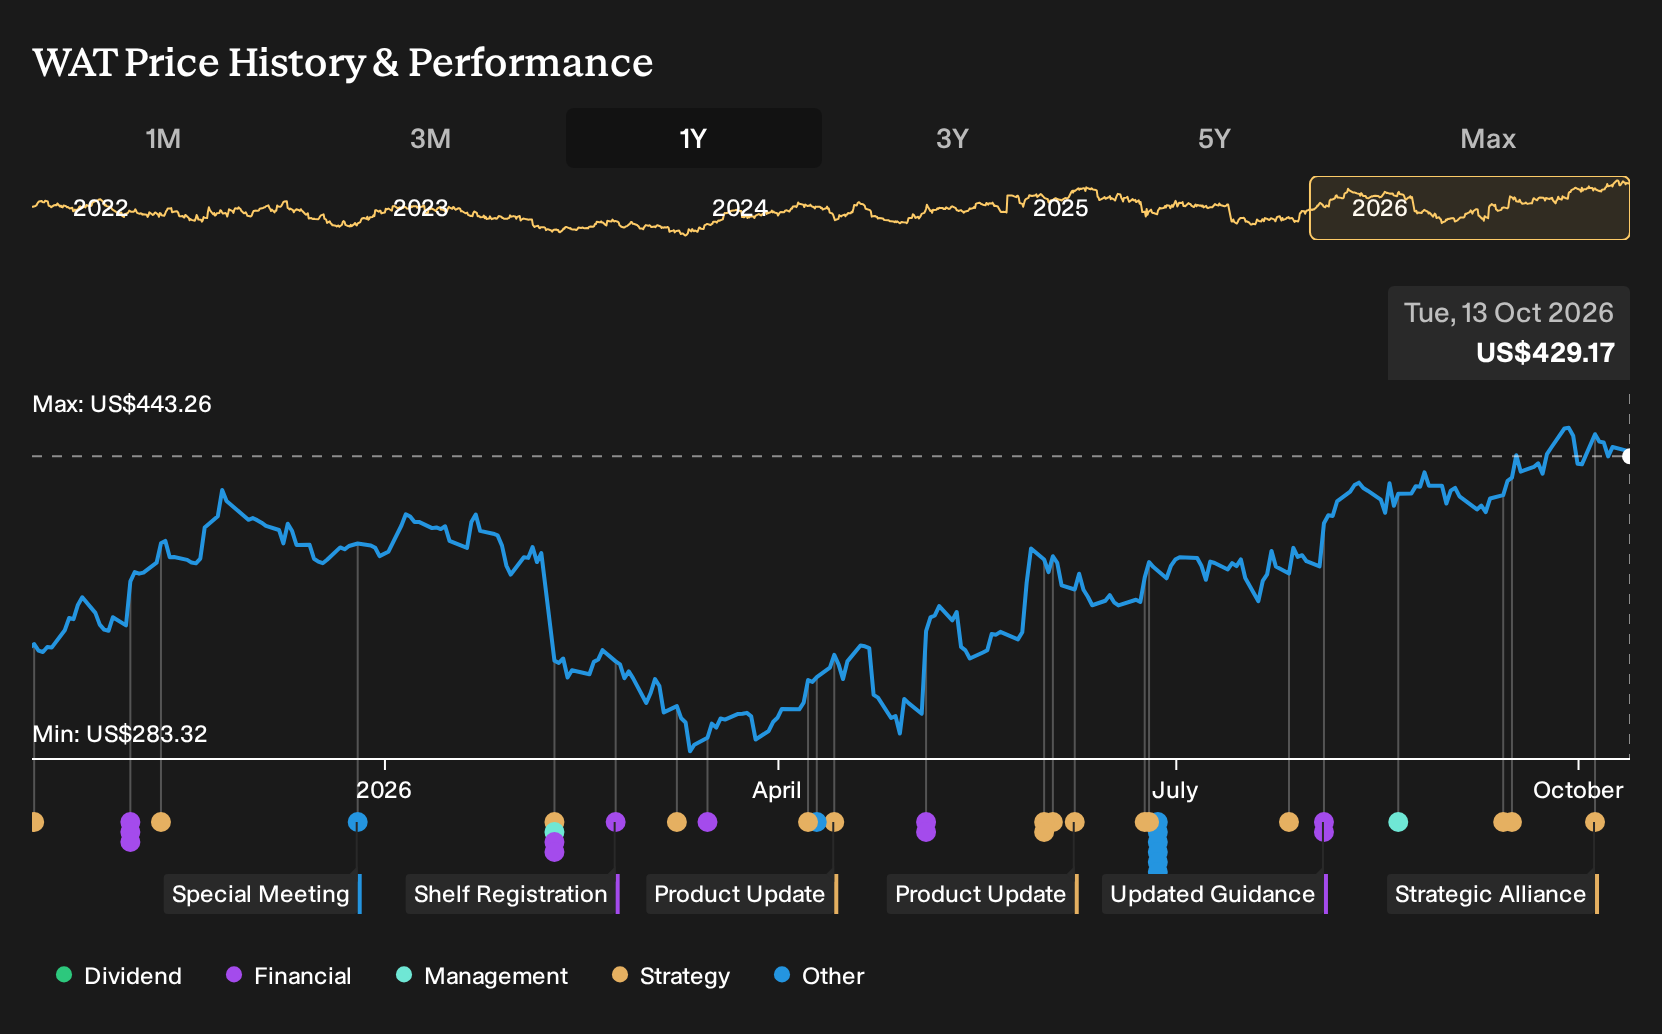
Uncover why Waters' fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You can read Waters AI Link as a potential counterpoint to the most bearish view, which worries about mature product lines and slower capital spending. Those lowest analysts were pencilling in about US$8.1b of revenue and US$1.1b of earnings by 2029, before this news, so their more cautious story may evolve as AI driven workflows gain attention.
Explore 3 other Waters fair value estimates, including one that suggests there could be as much as 8% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own perspective.
- A great starting point for your Waters research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Waters. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Waters' overall financial health at a glance.
Looking for more investment ideas beyond Waters?
If Waters has sharpened your thinking on AI heavy lab workflows but you want a broader watchlist, the Simply Wall St Screener can help you line up other candidates that fit your style, risk tolerance, and time horizon.
- For investors who care most about balance sheet strength and fundamental resilience, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions.
- If your focus is long term compounding potential, broaden your watchlist with a 20 high quality undiscovered gems that are already posting solid metrics but still sit off most radars.
- For those who prefer a calmer ride, narrow your search to a 32 resilient stocks with low risk scores that score well on stability and downside control.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com